EURUSD
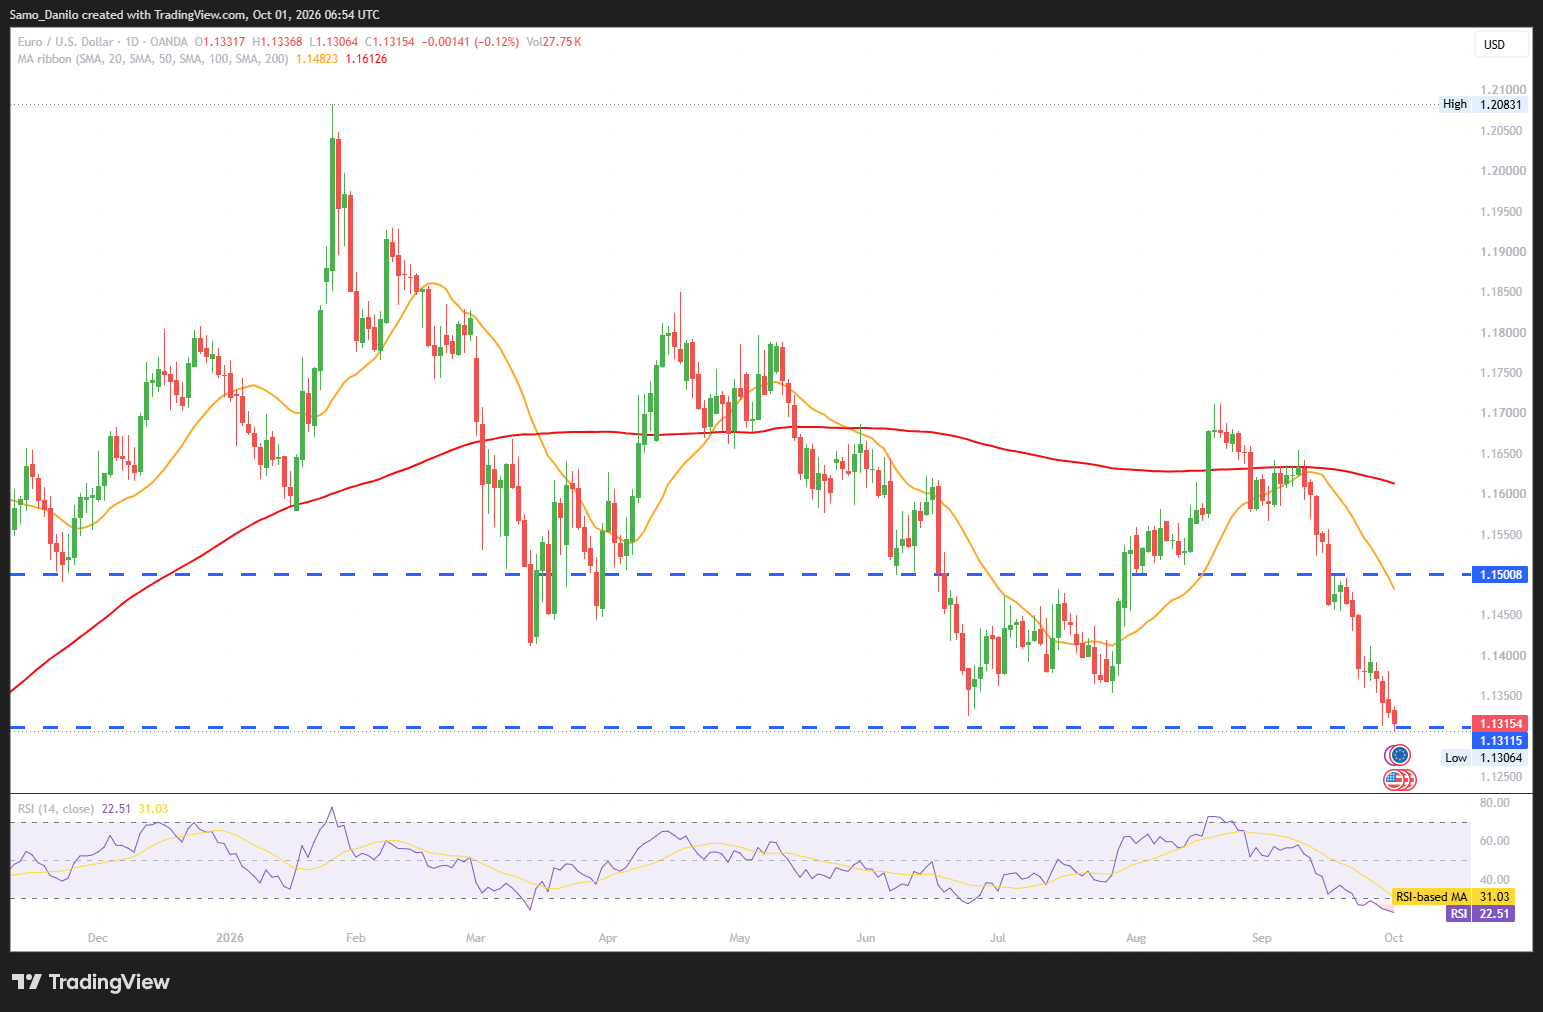
- EUR/USD Price: The EUR/USD pair drifts lower toward 1.1320 during the early European trading session on Thursday.
- ECB's Lagarde: ECB President Christine Lagarde said that rising bond yields could curb economic expansion and limit the extent to which elevated energy costs are passed through to consumer prices.
- Eurozone inflation: Inflation appears to be gaining momentum across the euro area, with HICP readings from France, Italy and Germany on Wednesday coming in well above expectations.
- TD Securities: TD Securities said that resilient growth and persistent inflation pressures are likely to keep the ECB focused on returning interest rates to mildly restrictive territory. The bank expects the Governing Council to deliver a final 25-basis-point hike in December, taking the deposit rate to 2.75%.
- CB speakers: ECB President Lagarde and Executive Board member Isabel Schnabel are scheduled to speak on Thursday, alongside Federal Reserve officials Austan Goolsbee and John Williams.
| SMA (20) | Falling |  | |
| RSI (14) | Falling | | |
| MACD (12, 26, 9) | Falling | | |
Closing statement: EUR/USD remains under pressure near 1.1320 despite stronger euro-area inflation readings that could reinforce expectations for further ECB tightening. The contrasting signals on growth and inflation, together with speeches from key ECB and Fed officials, are likely to drive the pair’s next move.
GBPUSD
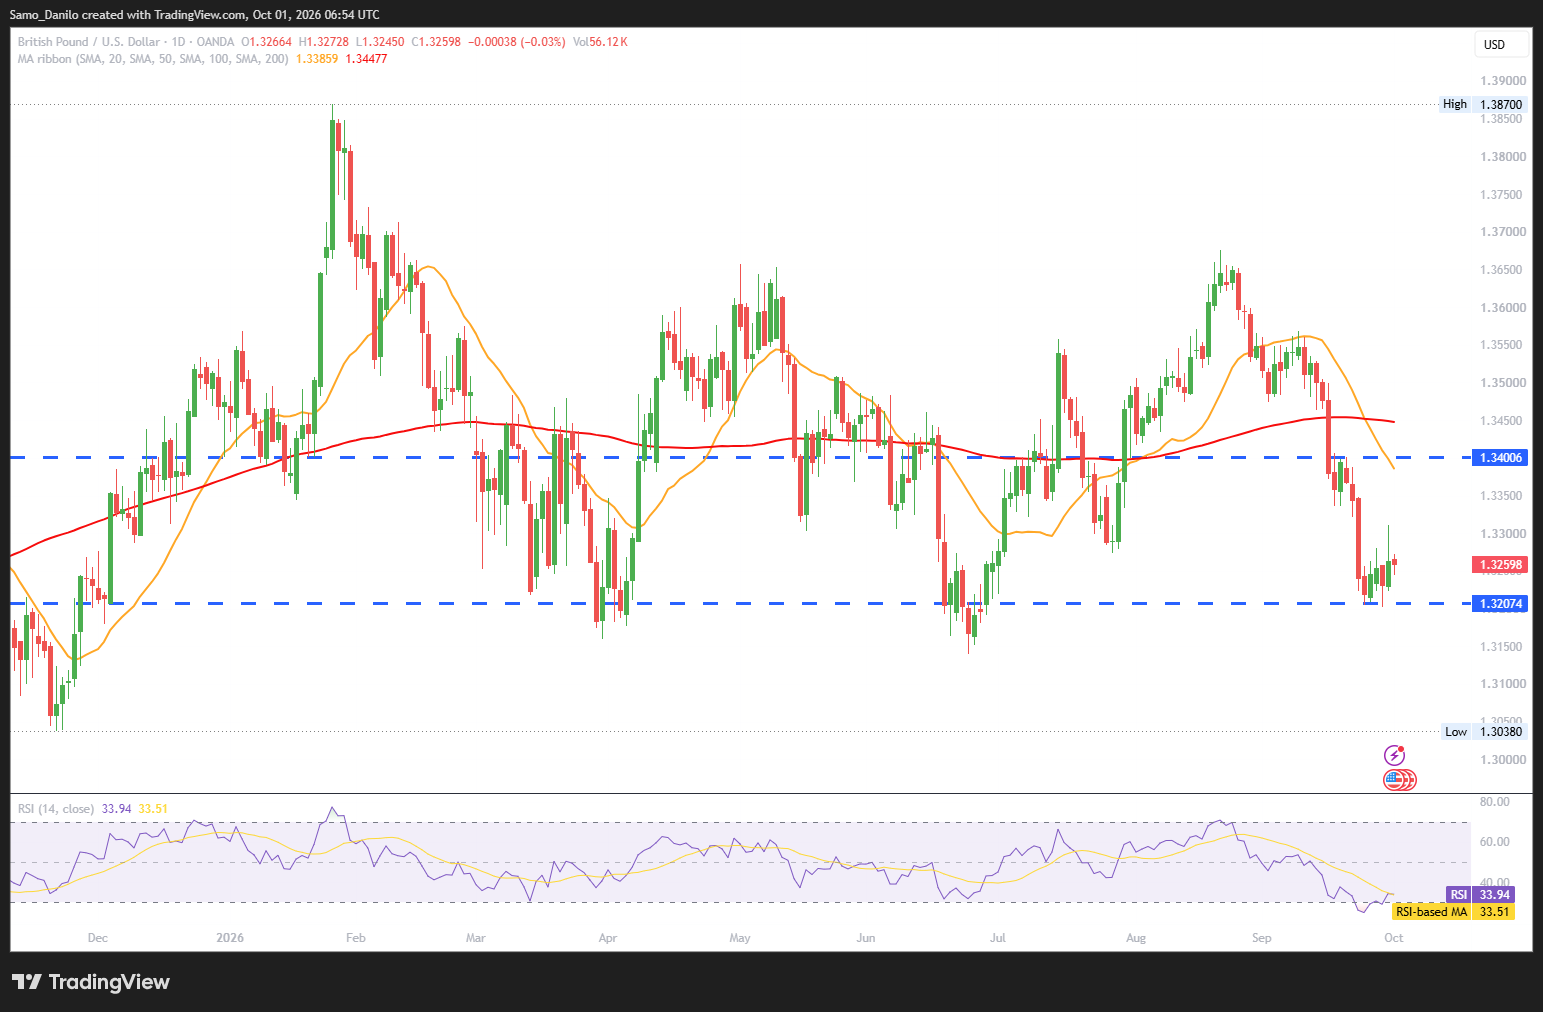
- GBP/USD Price: The GBP/USD pair trades in negative territory around 1.3250 during the early European trading session on Thursday.
- BoE's Taylor: BoE policymaker Alan Taylor said it is unclear whether a single rate hike would be practical for containing inflation without triggering unwarranted market expectations of further increases.
- BoE tightening: According to LSEG-compiled data, traders are pricing in nearly 33 basis points of BoE monetary tightening by year-end and more than 100 basis points by the end of 2027. However, analysts broadly expect a much more limited policy response, creating a notable gap between market pricing and expectations for the BoE’s rate path.
- PCE inflation: The US Personal Consumption Expenditures (PCE) Price Index increased 0.3% month-on-month in August, bringing the annual increase to 3.4%, according to the Bureau of Economic Analysis.
- UK Budget: UK Prime Minister Burnham said the government cannot pursue unfunded plans in the upcoming budget and is considering all options, including fuel duty.
| SMA (20) | Falling | | |
| RSI (14) | Falling | | |
| MACD (12, 26, 9) | Falling | | |
Closing statement: GBP/USD remains under pressure near 1.3250 as uncertainty over the BoE’s future tightening path contrasts with elevated US inflation. Diverging expectations between market pricing and analysts’ forecasts for BoE policy, alongside UK budget developments, are likely to remain key drivers for the Pound.
XAUUSD
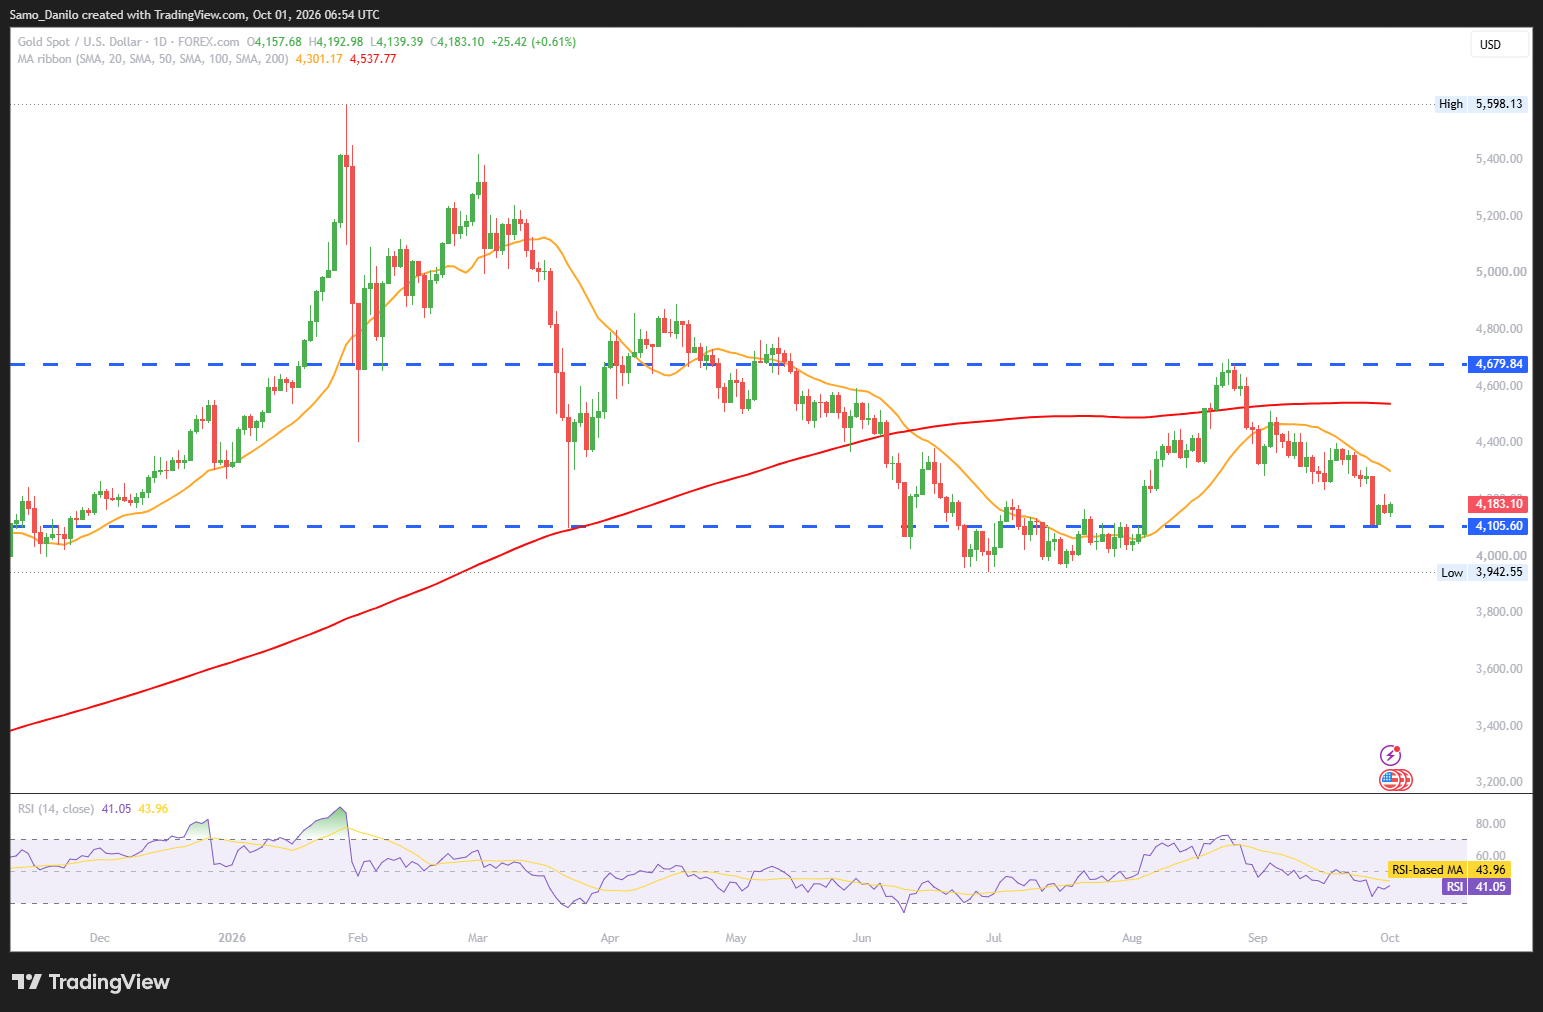
- XAU/USD Price: Gold (XAU/USD) attracts fresh dip-buying around the $4,139 region during Thursday’s European session.
- PCE inflation: US headline PCE inflation eased to 3.4% year-on-year in August, below the 3.7% market consensus, while core PCE declined to 3.0% compared with expectations of 3.3%.
- Rate expectations: According to the CME FedWatch Tool, markets are pricing a 38.2% probability of a 25-basis-point rate hike this month, down from 51% one day earlier.
- Powell’s status: US President Donald Trump said former Fed Chair Powell should be forced to resign from the Federal Reserve Board and suggested that the US government could pursue legal action against him.
- Fed's Kashkari: Fed policymaker Neel Kashkari said inflation remains too high and is running at around 3%, adding that the latest data did not change that assessment.
| SMA (20) | Slightly Falling | |
| RSI (14) | Slightly Falling | |
| MACD (12, 26, 9) | Slightly Falling | |
Closing statement: XAU/USD finds support near $4,139 as softer-than-expected US PCE inflation reduces expectations for an immediate Fed rate hike. However, continued expectations for a December hike and Kashkari’s warning that inflation remains too high could limit the upside, while uncertainty surrounding the Federal Reserve adds another source of volatility.
CRUDE OIL
- Crude Oil Price: West Texas Intermediate (WTI), the US crude oil benchmark, comes under renewed selling pressure during Thursday’s European session, reversing part of the previous day’s modest recovery. Despite the pullback, the commodity remains above the $93.00 level.
- Diesel export: US President Donald Trump said on Wednesday that he is having discussions about a possible ban on diesel exports “every day.” The White House is seeking measures to curb elevated energy prices ahead of the midterm elections, keeping US refined-product policy in focus.
- Diesel supplies: US Energy Secretary Wright said he expects announcements from Europe regarding new diesel supplies soon.
- OPEC+ output: OPEC+ oil producers are reportedly set to maintain their current output targets at Sunday’s meeting. A decision to keep production levels unchanged would leave the group’s existing supply policy intact and provide limited new direction for crude prices.
- Russia's warning: Russian Foreign Ministry spokeswoman Maria Zakharova said weapons factories in Europe producing arms for Ukraine are considered legitimate military targets by Russia.
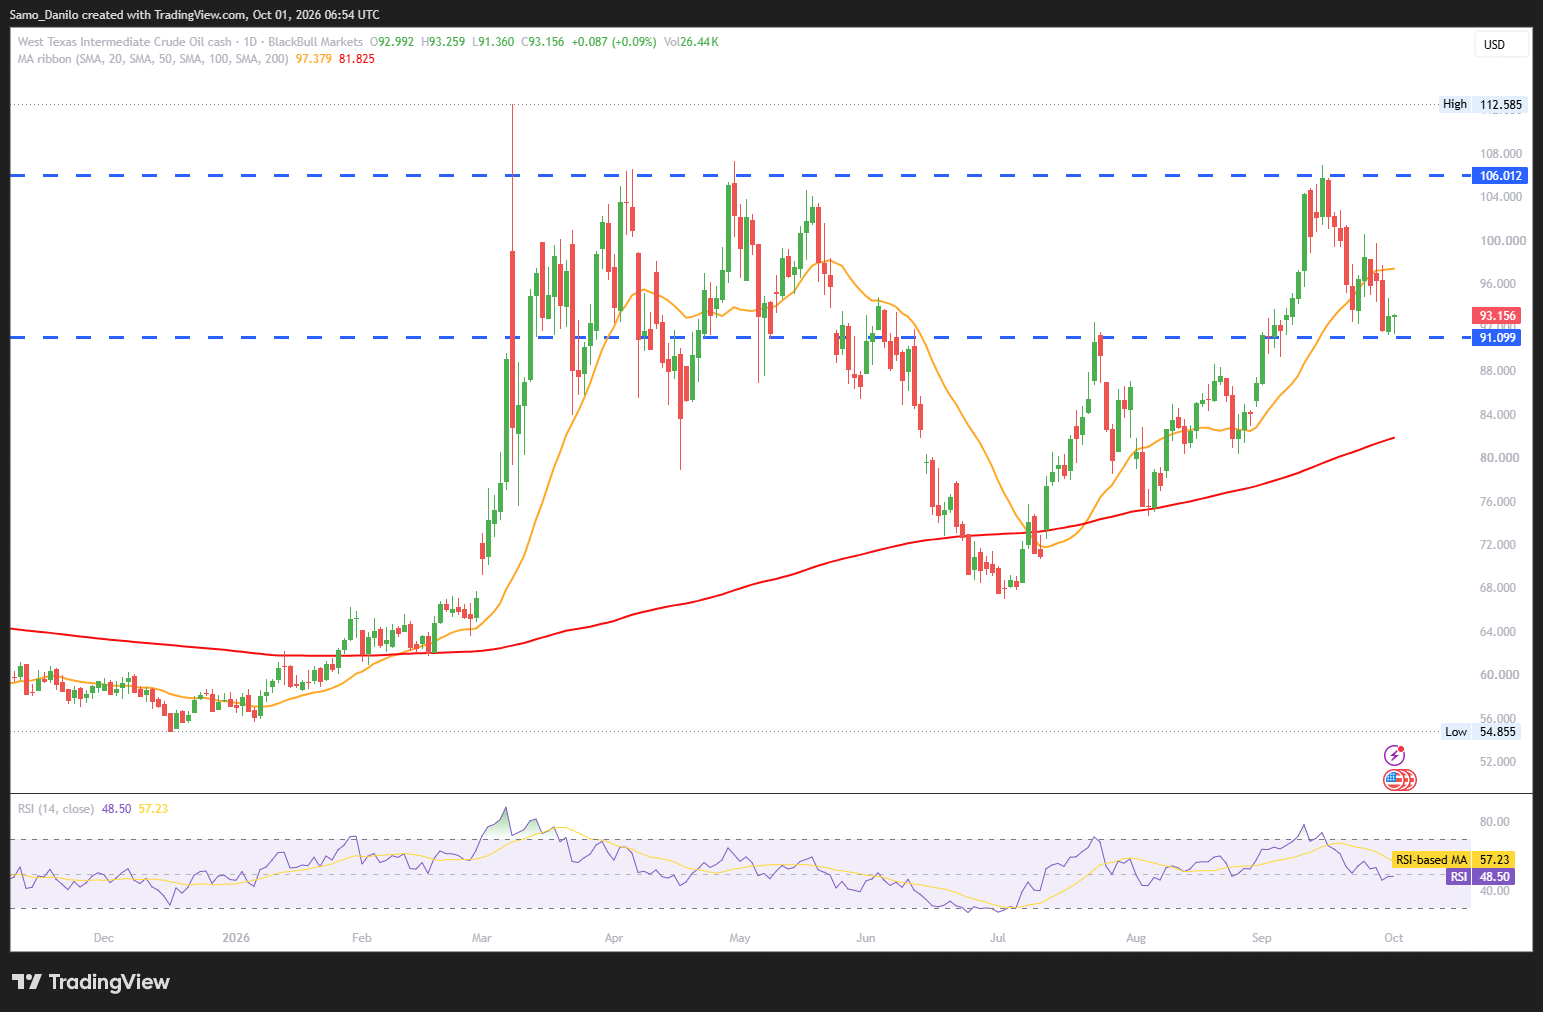
| SMA (20) | Rising |  | |
| RSI (14) | Slightly Falling | |
|
| MACD (12, 26, 9) | Slightly Rising | |
Closing statement: WTI remains above $93.00 despite renewed selling pressure, with US diesel-export policy and expected increases in European diesel supplies shaping the refined-product outlook. Meanwhile, unchanged OPEC+ output targets could limit major supply shifts, while elevated geopolitical tensions remain an important source of potential volatility.
DAX
- DAX 40 Price: The DAX 40 trades lower around the 25,000-point level during Tuesday’s European morning session.
- Eurozone inflation: Inflation came in above expectations in France, Italy and Germany, with French HICP rising to 3.4% year-on-year, Italian HICP reaching 4.1% and German HICP increasing to 3.3%.
- ECB's Schnabel: ECB policymaker Isabel Schnabel said there is no one-to-one link between energy prices and interest rates, stressing that the key issue is how higher energy costs feed into underlying inflation.
- ECB's Lagarde: ECB President Christine Lagarde described France’s debt situation as serious, with public debt at around 120% of GDP, and stressed the need for a credible path toward reducing it.
- Events ahead: The US weekly Initial Jobless Claims report will be released later in the day, alongside several Federal Reserve speakers.
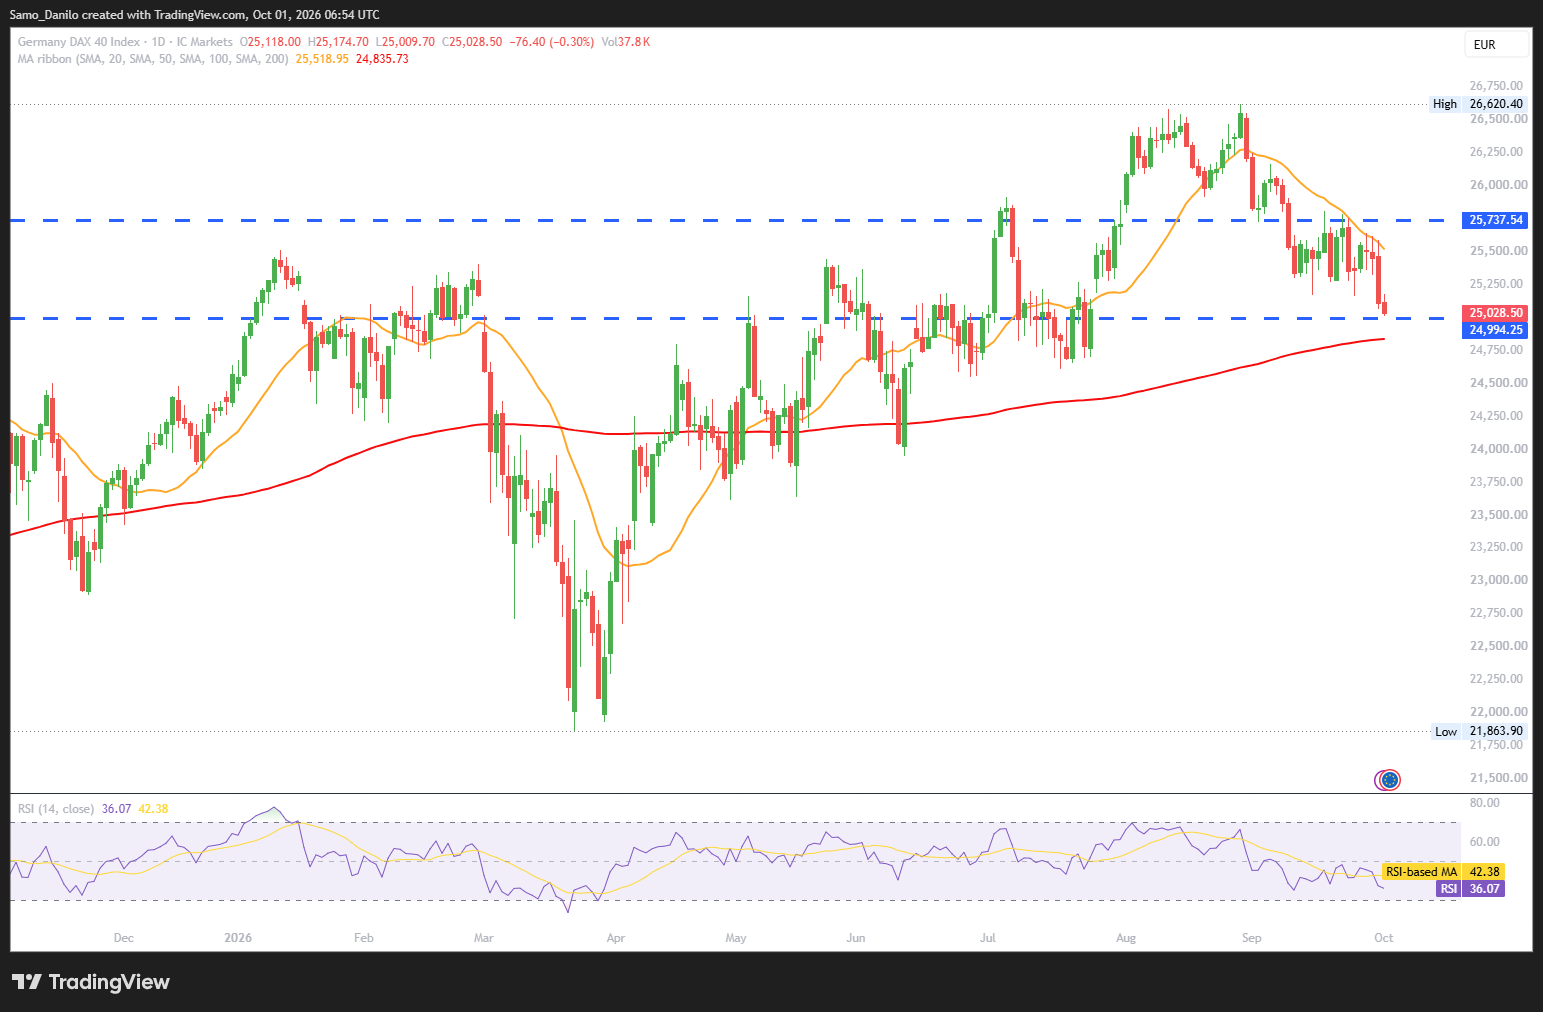
| SMA (20) | Slightly Falling | |
|
| RSI (14) | Falling | | |
| MACD (12, 26, 9) | Slightly Falling | |
Closing statement: The DAX 40 trades near 25,000 as stronger-than-expected euro-area inflation increases attention on the ECB’s policy outlook. Concerns over French public debt and developments in US labour-market data and Fedspeak could add further volatility to the index during the session.