EURUSD
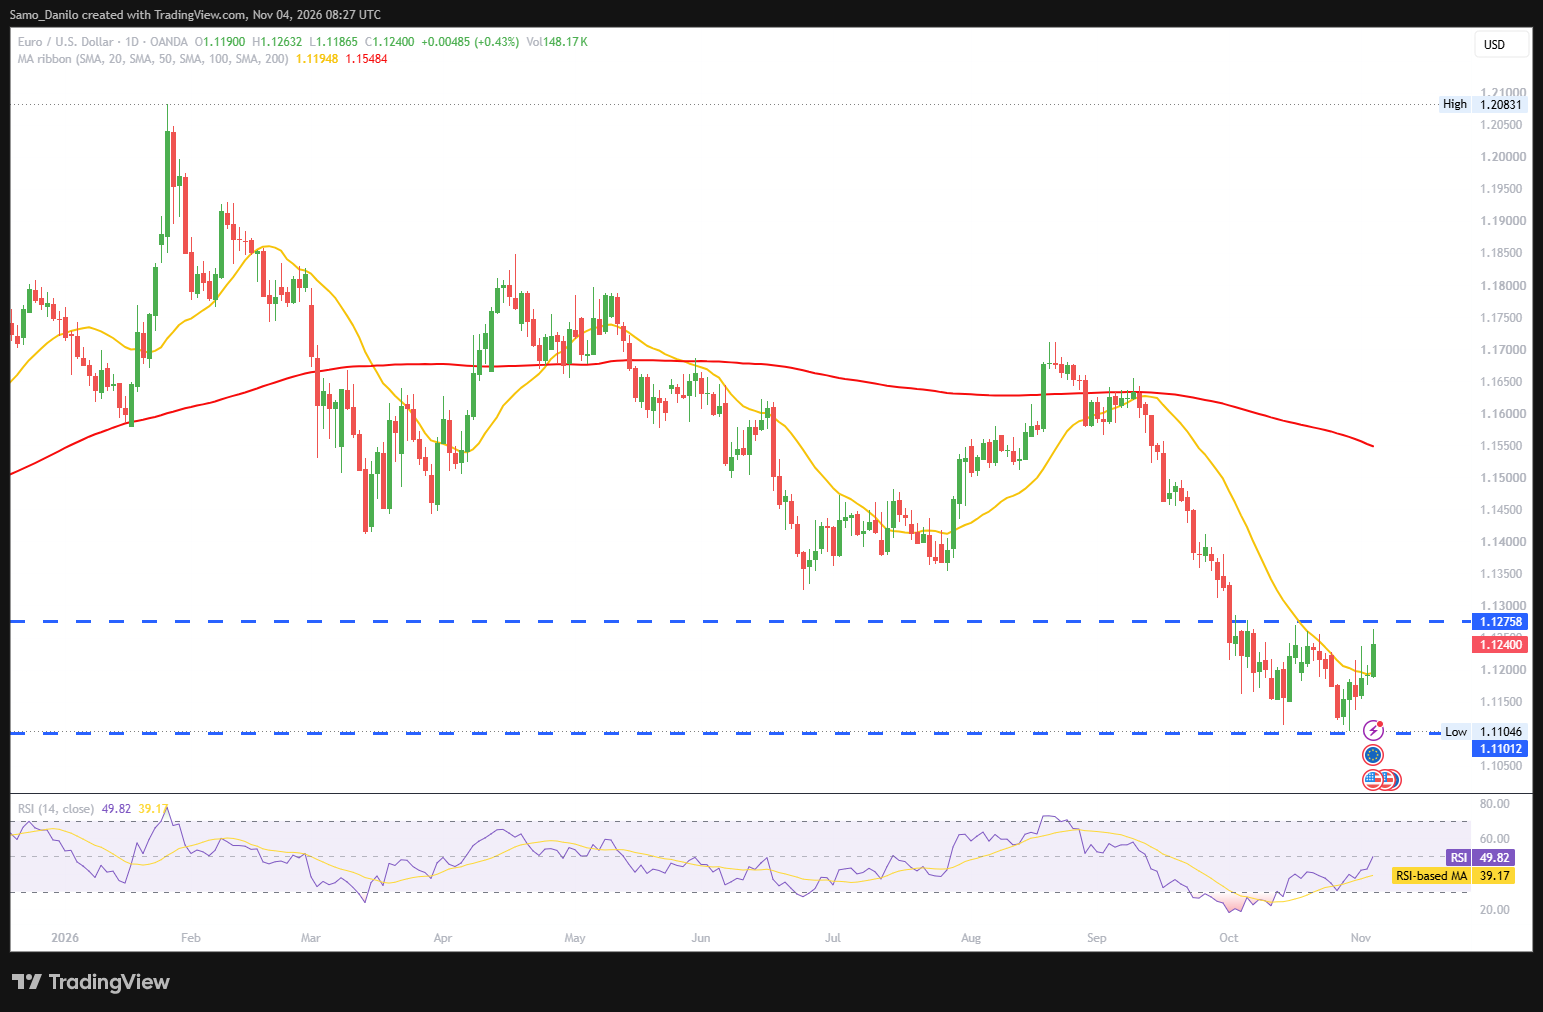
- EUR/USD Price: The EUR/USD pair is trading higher near 1.1240 during Wednesday's early European session, extending its recent positive momentum.
- Midterm elections: Early election results indicate that Democrats have gained control of both the US Senate and the House of Representatives, taking majorities previously held by Republicans. The political shift has put downward pressure on the US Dollar.
- ECB's Nagel: ECB policymaker Joachim Nagel emphasized that the central bank "can and must prevent an energy price spike from causing broad-based inflation." His remarks reinforce the ECB's willingness to respond to second-round inflationary effects and strengthen expectations that monetary policy could remain restrictive.
- Inflation data: Preliminary October inflation figures are scheduled for release, with headline inflation expected to accelerate to 4.0% year-on-year from 3.8%, largely driven by higher energy prices. Core inflation is forecast to remain unchanged at 2.5%, making the composition of the report particularly important for assessing underlying price pressures.
- Employment report: The US ADP private-sector employment report for October is due for release later today. Private-sector employment has added an average of approximately 50,000 jobs per month since May.
| SMA (20) | Falling |  | |
| RSI (14) | Slightly Rising |  |
|
| MACD (12, 26, 9) | Slightly Falling | |
Closing statement: EUR/USD currently maintains a bullish short-term bias, supported by broad US Dollar weakness and a relatively hawkish ECB stance. Overall, the upside scenario remains favoured while the pair holds above 1.1200, although confirmation from today's economic releases will be important.
GBPUSD
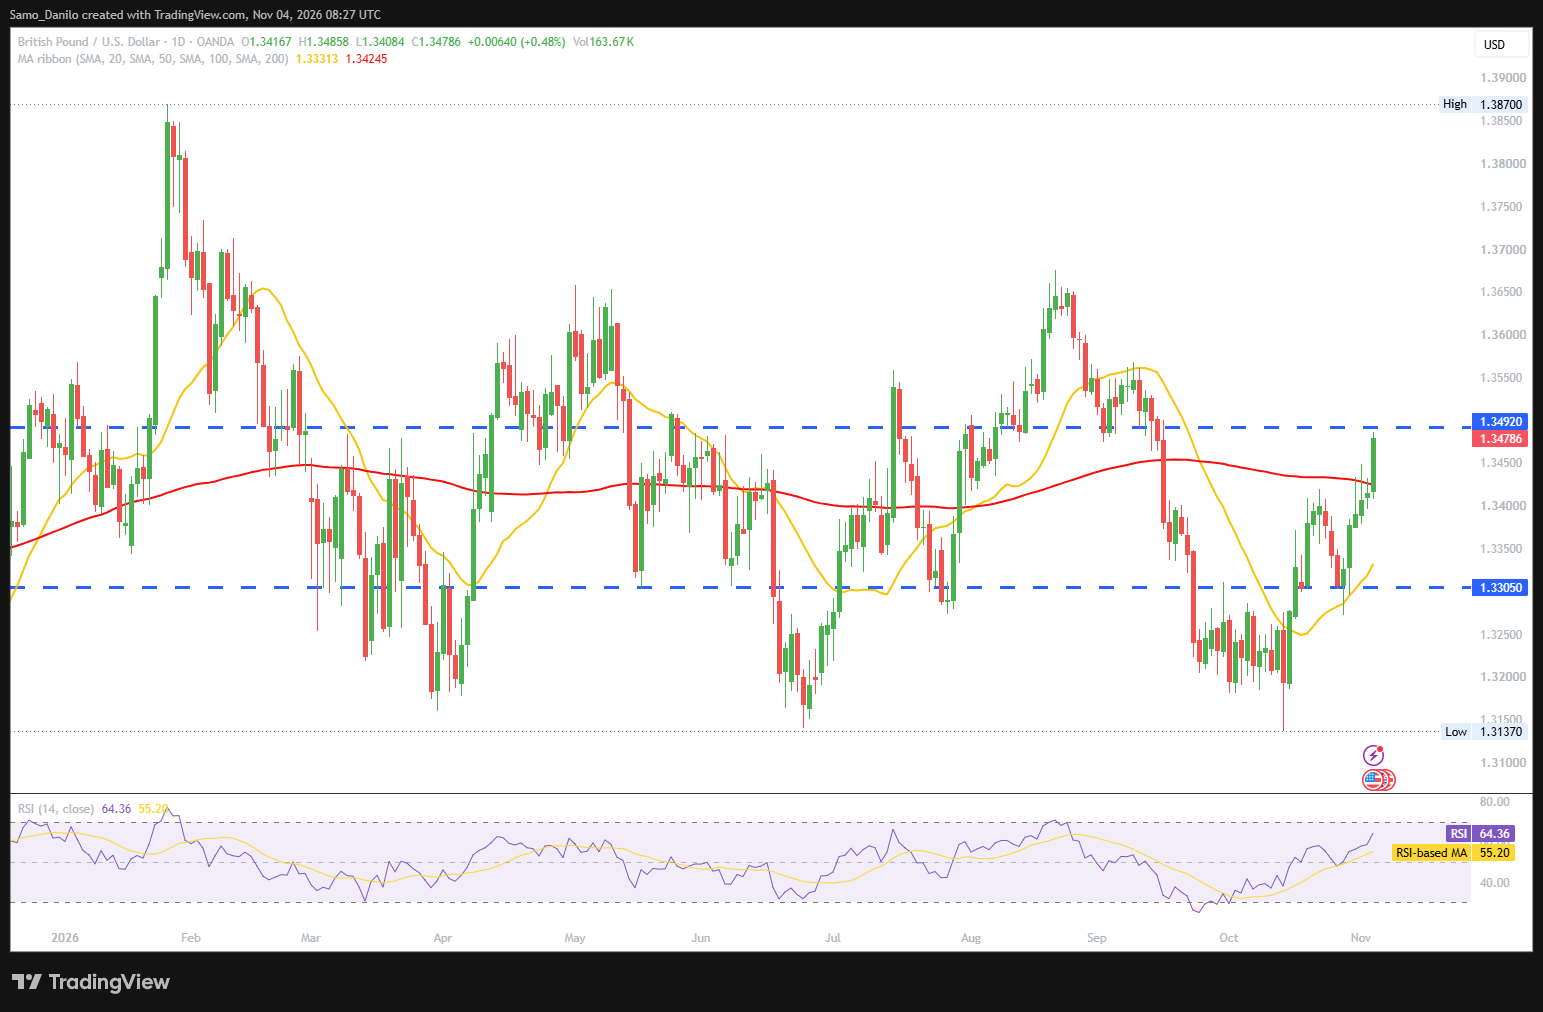
- GBP/USD Price: The GBP/USD pair attracted strong buying interest during Wednesday's Asian session, climbing beyond the mid-1.3400s and reaching its highest level since September 16.
- US-Iran: President Donald Trump told the Financial Times on Tuesday that the US has no immediate plans to strike Iran, increasing optimism over a potential diplomatic resolution to the conflict.
- BoE expectations: The British Pound continues to outperform as concerns surrounding the UK's fiscal position ease following recent budget updates. At the same time, expectations of a Bank of England interest rate hike at Thursday's policy meeting are providing additional support for sterling.
- Shadow MPC: The London Times Shadow Monetary Policy Committee (MPC) voted unanimously, 9–0, in favour of raising interest rates to tackle persistent inflation.
- Cybersecurity risks: The head of the UK's National Cyber Security Centre (NCSC) warned that the country faces a significant rise in cyberattacks over the coming months.
| SMA (20) | Slightly Rising | |
|
| RSI (14) | Rising | | |
| MACD (12, 26, 9) | Slightly Rising | |
Closing statement: GBP/USD maintains a bullish short-term outlook, supported by a weaker US Dollar, easing UK fiscal concerns and growing expectations of a BoE rate hike. A sustained move above the mid-1.3400s could open the way towards 1.3500, particularly if Thursday's decision confirms market expectations. Conversely, a less hawkish-than-expected BoE outcome or a recovery in the US Dollar could trigger profit-taking towards 1.3400 and 1.3350. Overall, the upside scenario remains favoured while the pair holds above 1.3400, with Thursday's policy announcement representing the key near-term catalyst.
XAUUSD
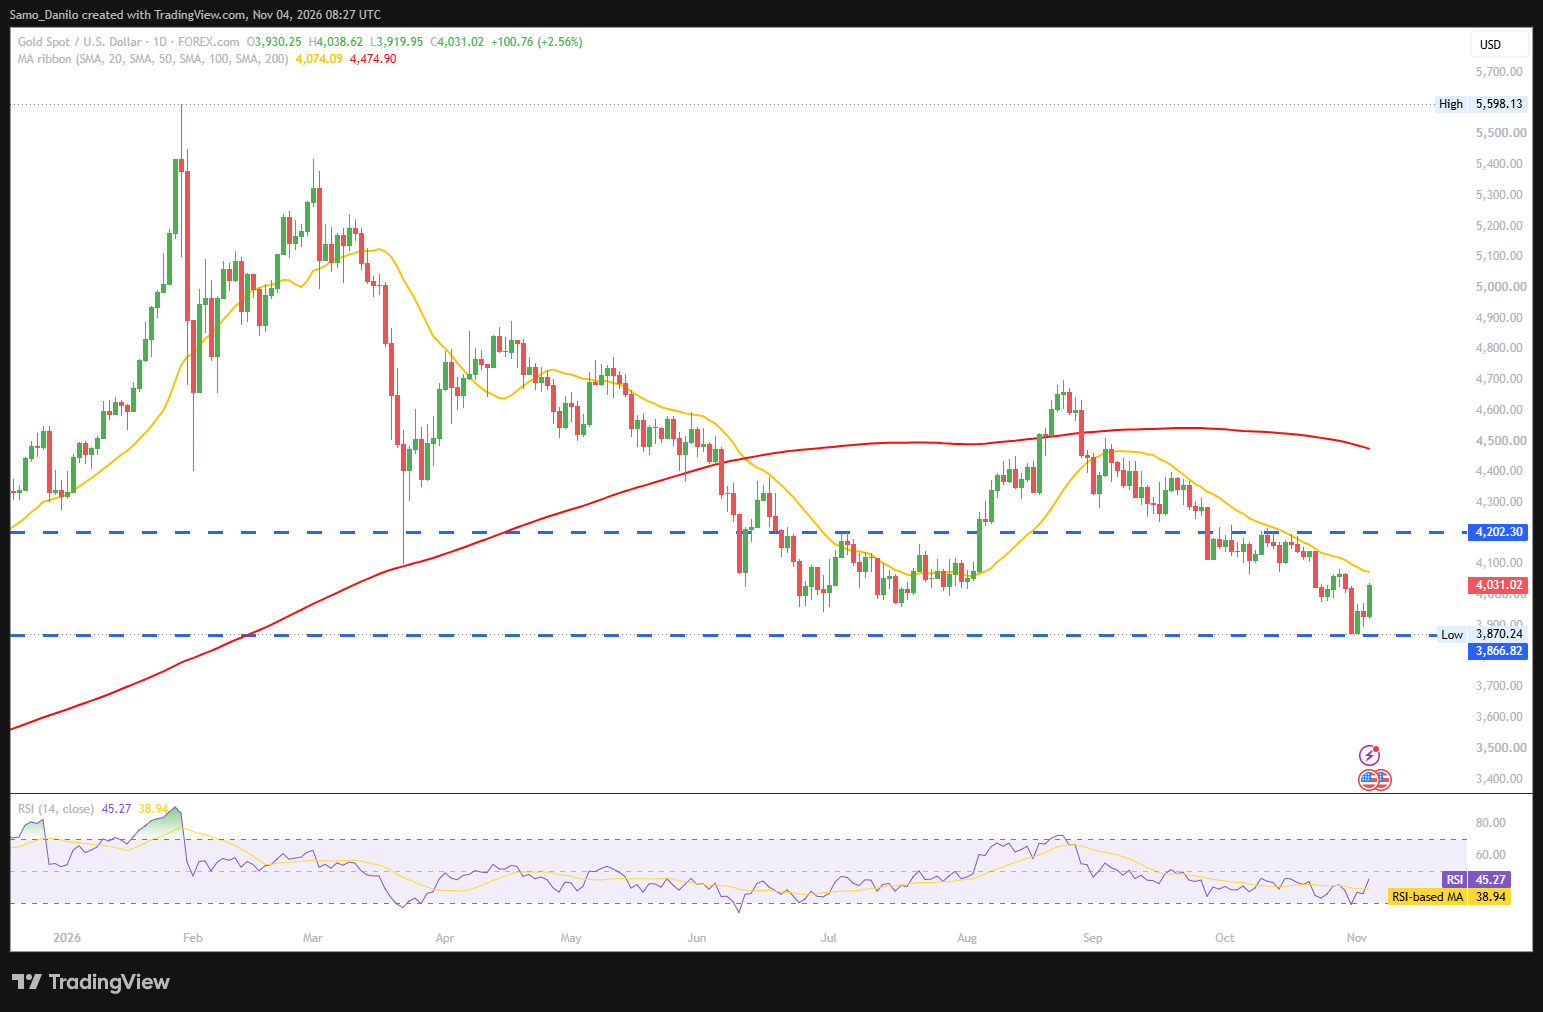
- XAU/USD Price: Gold (XAU/USD) maintained strong intraday gains near its weekly high, trading comfortably above the psychologically important $4,000 level during Wednesday’s early European session.
- US Treasury: The US Treasury is set to release its quarterly refunding announcement, including forward guidance on debt issuance.
- Labour market: The September JOLTS report came in notably stronger than expected, with job openings increasing by 333,000 month-on-month to 7.523 million, compared with the 7.1 million consensus forecast. August figures were also revised higher, suggesting continued resilience in the US labour market and potentially reducing expectations for near-term monetary easing.
- Chinese data: China's October RatingDog Services PMI eased to 50.8 from expectations of 51.7, although it marked the 44th consecutive month of expansion. The Composite PMI stood at 52.0, down from the previous reading of 52.4, indicating that economic activity continued to expand but at a slightly slower pace.
- Data ahead: Market participants are now turning their attention to the US ADP private-sector employment report and the ISM Services PMI, both scheduled for release later in the North American session.
| SMA (20) | Slightly Falling | |
| RSI (14) | Slightly Falling | |
| MACD (12, 26, 9) | Slightly Falling | |
Closing statement: Gold's ability to hold above the $4,000 psychological threshold, supported by a weaker US Dollar, keeps the short-term outlook cautiously bullish. A sustained move above the weekly high could create room for further upside, particularly if upcoming US employment and services data weaken the Dollar and reinforce expectations of monetary easing. Conversely, stronger-than-expected figures and rising Treasury yields could trigger a corrective pullback, with the $4,000 level remaining an important psychological area to monitor.
CRUDE OIL
- Crude Oil Price: West Texas Intermediate (WTI) crude oil was trading lower at approximately $97.10 per barrel on Wednesday morning, extending its recent downward movement.
- Trump's comments: Oil prices came under pressure on Tuesday after President Donald Trump signalled an end to the $4 billion in annual financial support for Israel and stated that he was “not looking to kill tons of people.”
- Strait of Hormuz: Iranian Security Chief Rezaee reiterated that the Strait of Hormuz would only reopen once the United States had acted on Iran's seven conditions.
- Supply risks: Iran's Islamic Revolutionary Guard Corps (IRGC) claimed on Wednesday that four oil tankers were destroyed after hitting naval mines while attempting to navigate a route described as prohibited south of the Strait of Hormuz, according to Reuters.
- Asian crude: Asia's crude oil imports have nearly returned to pre-war levels, reaching 26.39 million barrels per day in October. However, refined fuel imports remain approximately 10% below pre-war volumes, indicating that while crude supply flows have recovered substantially, downstream fuel markets continue to face disruptions.
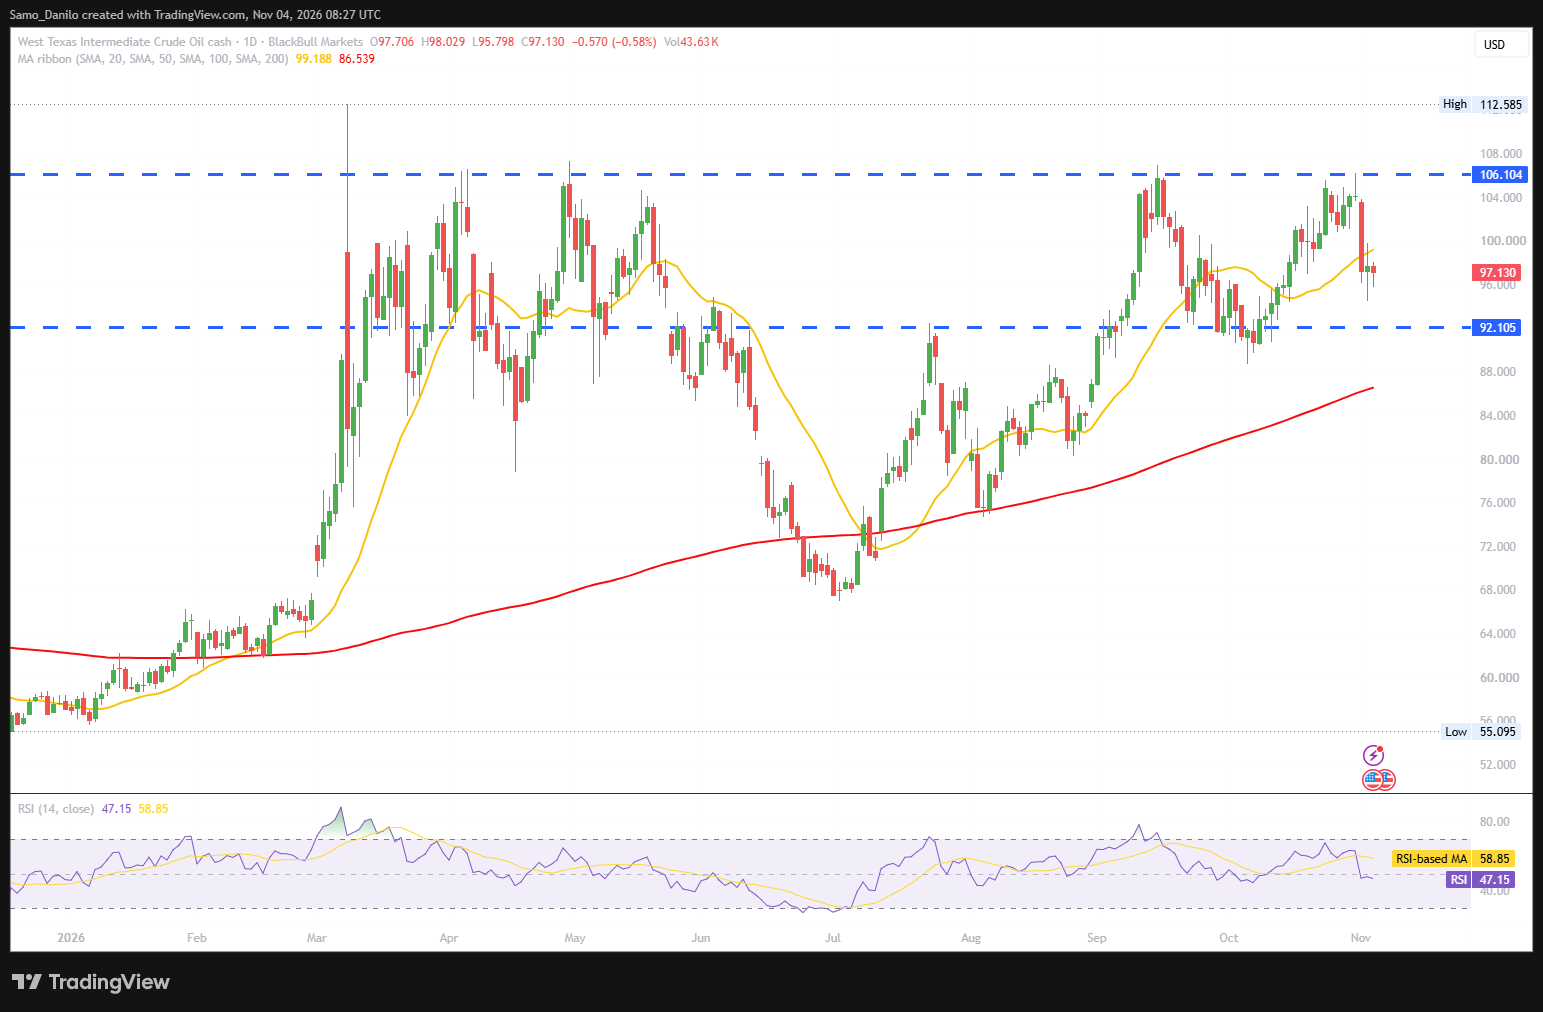
| SMA (20) | Slightly Rising | |
| RSI (14) | Slightly Falling | |
| MACD (12, 26, 9) | Slightly Rising | |
Closing statement: WTI faces conflicting forces, with easing expectations of further military escalation weighing on prices while the unresolved situation around the Strait of Hormuz continues to provide significant supply-side support. In the short term, the market may remain volatile around the $97 level, with further diplomatic progress potentially opening the door to additional downside. Conversely, any confirmed escalation, prolonged closure of the Strait, or further attacks on energy shipments could renew bullish momentum and push prices higher.
DAX
- DAX 40 Price: Germany's benchmark DAX 40 was trading higher at approximately 26,000 points on Wednesday morning, maintaining a positive short-term trend.
- ECB's Nagel: Bundesbank President Joachim Nagel stated that a rate hike in December is very likely to be necessary, adding that the inflation outlook has deteriorated since September.
- BMW forecast: BMW lowered its FY2026 automotive EBIT margin guidance to a range of -0.5% to +0.5%, down from its previous forecast of 1% to 3%, while maintaining its free cash flow outlook above €2.5 billion.
- Europe's competitiveness: The head of Swiss industrial group ABB argued that Germany must take a leading role in restoring Europe's economic competitiveness. He warned that without fundamental reforms, the continent could face the risk of mass unemployment, highlighting broader structural challenges for the German and European economies.
- PMI data: Markets are awaiting the final October Services and Composite PMI readings for the euro area. A marginal upward revision to the Composite PMI is expected, following Monday's manufacturing data, which showed a reading of 52.7 compared with the preliminary estimate of 52.4.
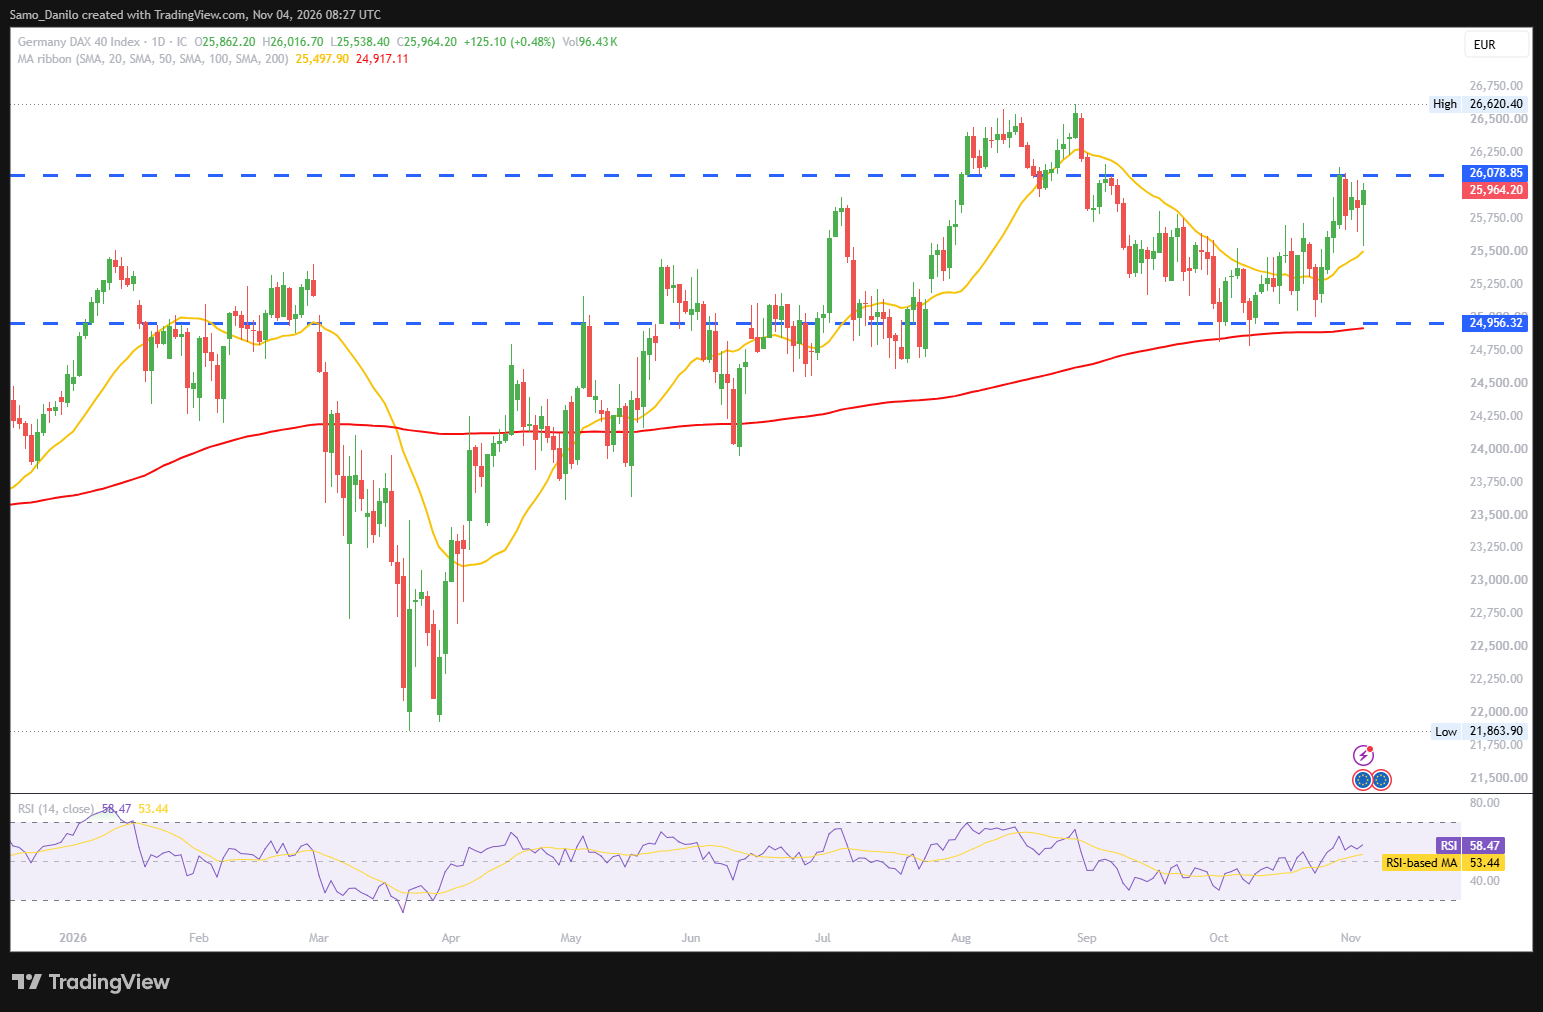
| SMA (20) | Slightly Falling | |
| RSI (14) | Slightly Rising | |
| MACD (12, 26, 9) | Slightly Rising | |
Closing statement: The DAX 40's ability to hold around the 26,000-point level keeps the short-term outlook cautiously positive, although the index faces potential headwinds from the prospect of an ECB rate hike and weakness in the automotive sector. Stronger-than-expected PMI readings could support further upside, while disappointing activity data or renewed concerns over corporate margins could trigger a pullback. A sustained move above 26,000 would strengthen the bullish scenario, whereas failure to hold this area could invite renewed selling pressure.