EURUSD
- EUR/USD Price: The Euro appreciated for the second consecutive session on Thursday, trading around 1.1240 against the US Dollar.
- US Dollar: President Donald Trump defended the intervention in Iran on Wednesday, while Vice President JD Vance stated in a post on X that the war was the main reason behind the Republicans' electoral defeat, adding that Trump had acknowledged this.
- Eurozone inflation: Preliminary figures released on Wednesday showed that consumer inflation accelerated to 4% year-on-year in October. The stronger reading increases pressure on the European Central Bank (ECB) to maintain a restrictive monetary stance, providing additional support for the Euro.
- Employment data: US economic data released on Wednesday provided further evidence of resilient economic momentum, with ADP Employment figures showing an increase of 86,000 private-sector jobs in October, above expectations of 69,000.
- ECB's Schnabel: ECB Executive Board member Isabel Schnabel is scheduled to speak at the ECB's Money Market Conference in Frankfurt.
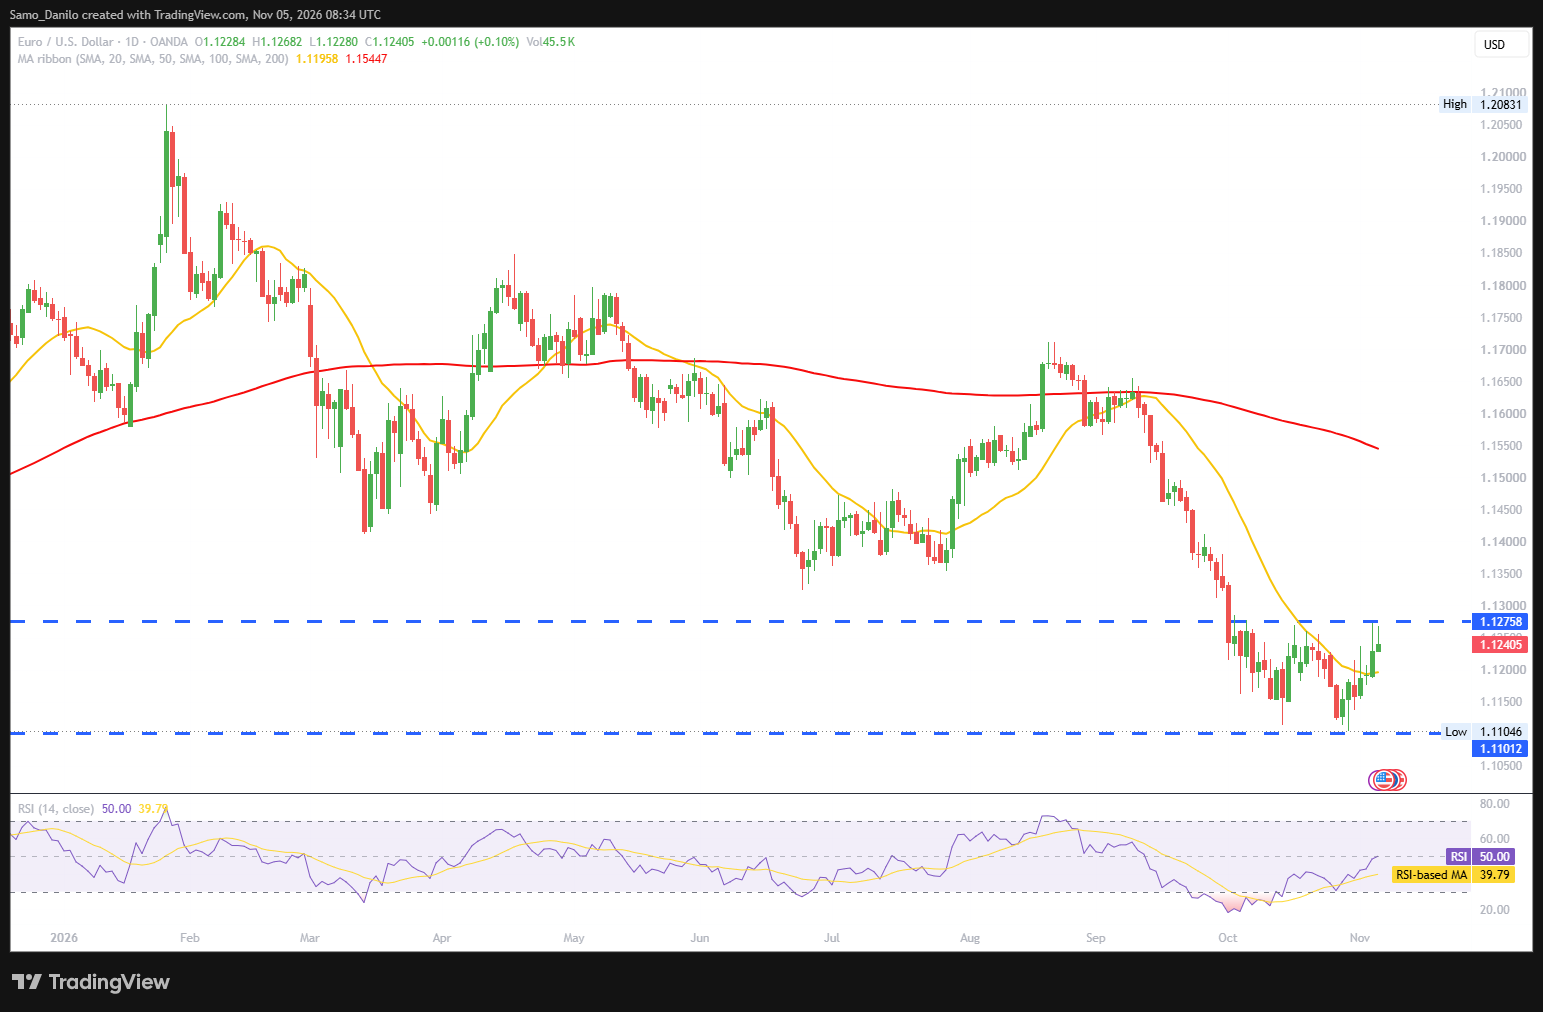
| SMA (20) | Falling |  | |
| RSI (14) | Slightly Rising |  |
|
| MACD (12, 26, 9) | Slightly Falling | |
Closing statement: EUR/USD maintains a cautiously bullish short-term outlook as the pair trades around 1.1240, supported by accelerating eurozone inflation and continued weakness in the US Dollar. A sustained move higher could open the way towards the 1.1300 area, particularly if Schnabel reinforces expectations of a restrictive ECB policy stance. Conversely, a recovery in the Dollar or signs that the ECB may be less aggressive than markets anticipate could trigger a correction, with 1.1200 representing an important psychological support area.
GBPUSD
- GBP/USD Price: GBP/USD was trading in positive territory near 1.3480 during Thursday's early European session, maintaining its recent upward momentum.
- Midterm elections: Democrats secured major victories in several traditionally Republican strongholds, taking control of both the Senate and the House of Representatives. The results represent a significant political setback for President Donald Trump and have contributed to market uncertainty surrounding the US political and economic outlook.
- US Services: The US ISM Services Purchasing Managers Index (PMI) came in slightly below market expectations, although the reading remained consistent with solid economic activity.
- Treasury yields: Ray Attrill, Head of FX Strategy at National Australia Bank, noted that recent market movements, particularly in bond markets, could be directly linked to the political developments, while lower Treasury yields have contributed to a weaker Dollar.
- BoE interest: The Bank of England's November policy decision will be the main event for Sterling traders on Thursday, with economists surveyed by Reuters expecting Bank Rate to rise to 4% from 3.75%. If delivered, this would mark the first interest-rate increase since August 2023, potentially providing significant support for the Pound.
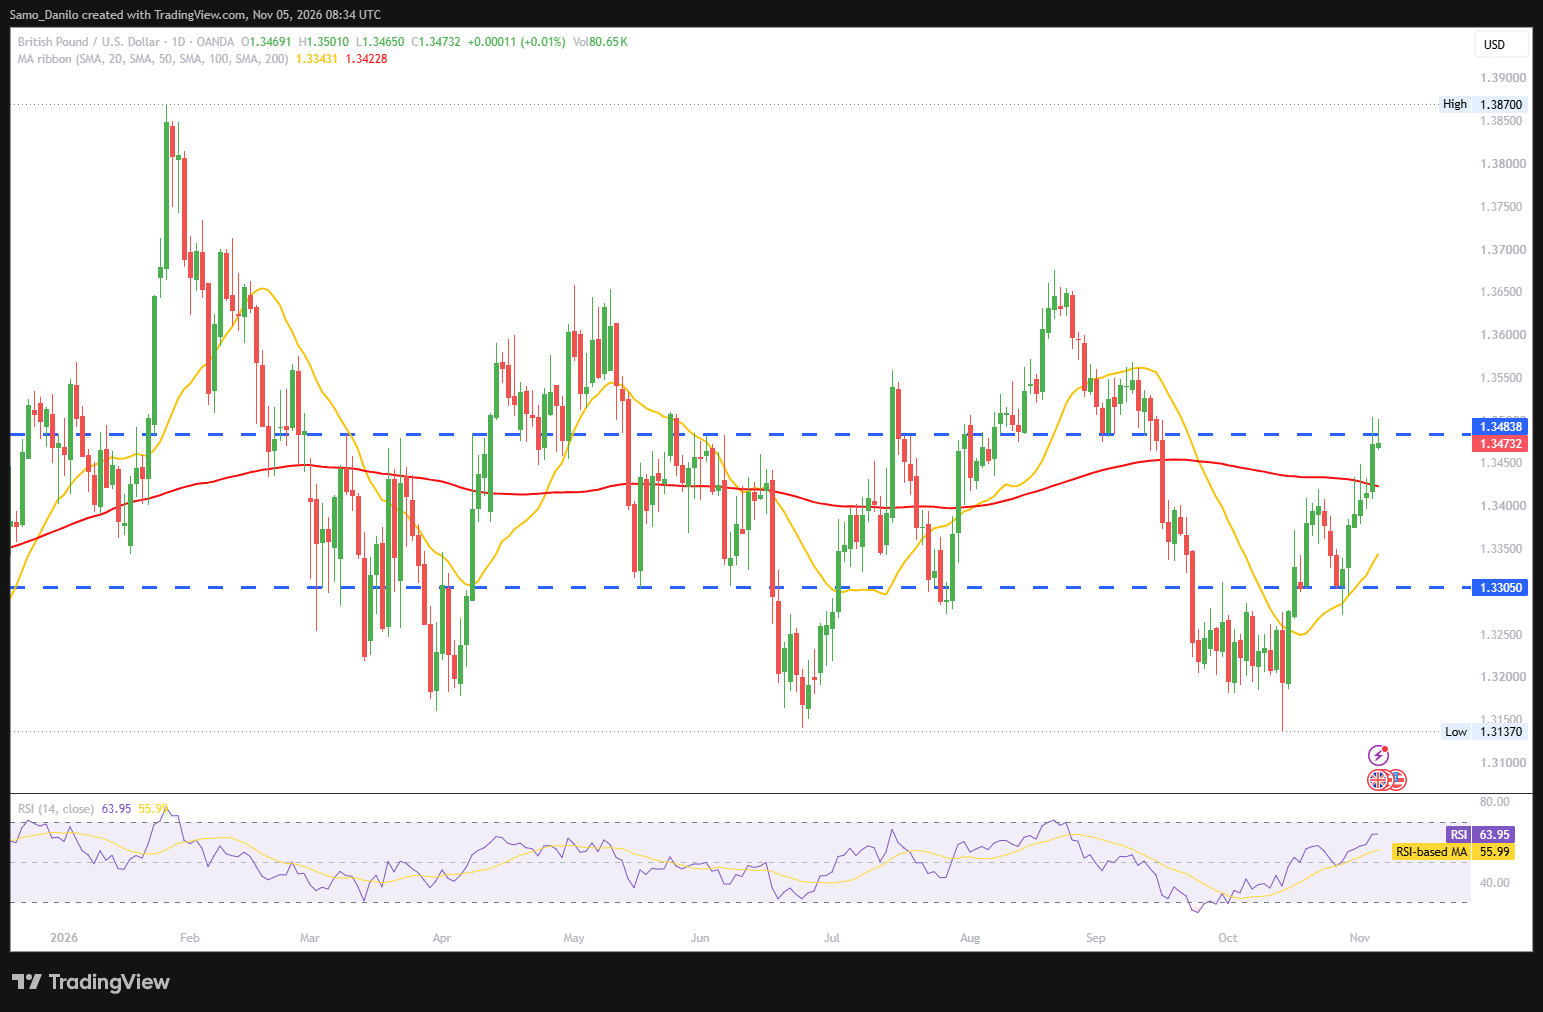
| SMA (20) | Slightly Rising | |
|
| RSI (14) | Rising | | |
| MACD (12, 26, 9) | Rising | | |
Closing statement: GBP/USD maintains a cautiously bullish short-term outlook near 1.3480, supported by broad US Dollar weakness and expectations of a BoE rate increase. A move above the 1.3500 psychological threshold could open the way for further gains, particularly if the BoE delivers the expected hike and signals continued concern over inflation. However, any less hawkish guidance or a recovery in US Treasury yields could trigger profit-taking and push the pair back towards 1.3450 and 1.3400.
XAUUSD
- XAU/USD Price: Gold (XAU/USD) maintained its positive momentum for a second consecutive session on Thursday, trading above $4,100 and near a two-week high during the early European session.
- Iran war: Top Senate Democrat Chuck Schumer vowed on Wednesday to push for an end to the war in Iran, indicating that his party could use its control over government funding to advance this objective.
- US Treasury: The US Treasury's fourth-quarter quarterly refunding announcement introduced no major changes to long-term debt issuance, buyback operations or the guidance surrounding them.
- Fed speakers: Markets will be monitoring comments from Fed officials Hammack, Logan and Barkin, whose respective voting positions change between 2026 and 2027.
- US NFP: Traders may remain cautious ahead of Friday's closely watched US monthly employment report, commonly known as Nonfarm Payrolls (NFP).
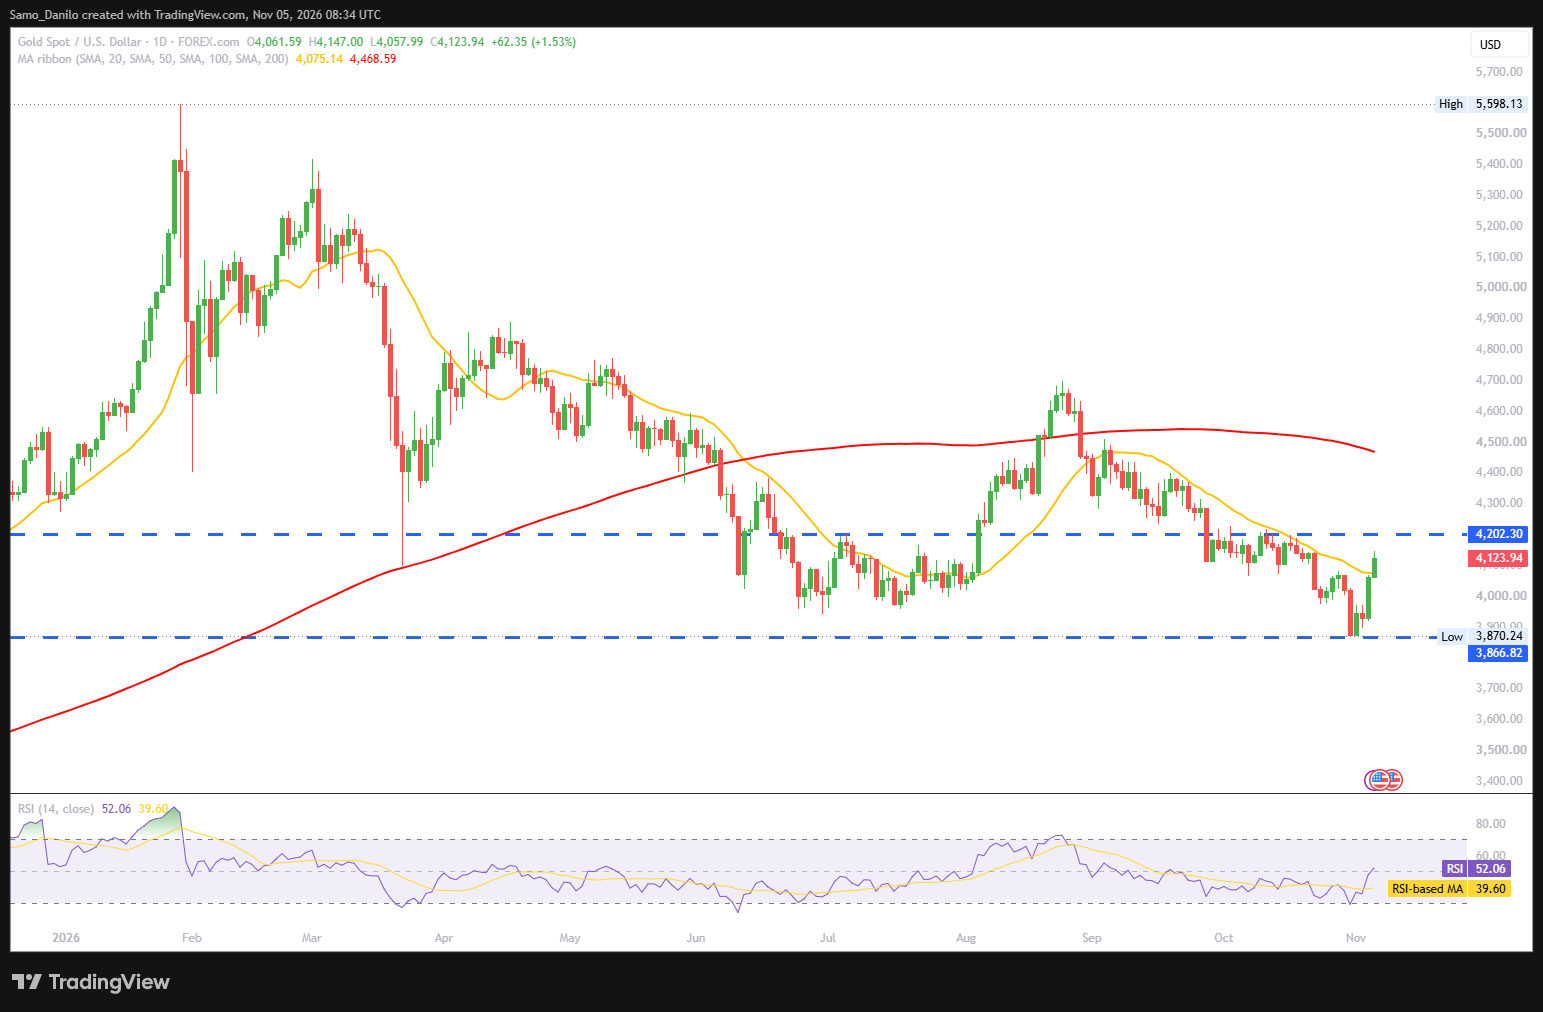
| SMA (20) | Slightly Falling | |
| RSI (14) | Slightly Rising | |
| MACD (12, 26, 9) | Slightly Falling | |
Closing statement: Gold's ability to remain above $4,100 and trade near a two-week high keeps the short-term outlook cautiously bullish. A sustained break above the recent high could create room for further upside, particularly if geopolitical uncertainty persists and upcoming US employment data increases expectations of monetary easing. Conversely, hawkish comments from Fed officials or stronger-than-expected NFP figures could support the US Dollar and Treasury yields, triggering a corrective move towards the $4,100 area.
CRUDE OIL
- Crude Oil Price: West Texas Intermediate (WTI), the US crude oil benchmark, was trading around $88.60 per barrel during Thursday's early European session.
- Midterm results: With no significant new geopolitical headlines, the latest downward move in oil appears largely driven by the Democratic sweep in the US midterm elections. The results have increased expectations of political pressure on the Trump administration to end the Iran conflict.
- Crude production: The latest weekly EIA report indicated that US crude production rose above 14 million barrels per day for the first time, while strategic reserves recorded a small draw. Commercial crude inventories declined by 865,000 barrels in the week ending October 30, compared with a 1.892 million-barrel decrease in the previous week, suggesting that domestic stockpiles continued to tighten despite record production.
- Export routes: The United Arab Emirates currently operates one crude export pipeline that bypasses the Strait of Hormuz and is reportedly planning a third pipeline to expand its transportation capacity. Additional infrastructure would allow more crude to reach international markets without passing through the strategic chokepoint.
- Ukraine-Russia: Melania Trump is scheduled to host Russian and Ukrainian representatives on November 5 following a rare humanitarian ceasefire in Russian-occupied Oleshky, which enabled civilian evacuations and aid deliveries. However, Ukraine has accused Russia of using the pause to reinforce its military positions, while US-mediated peace talks are expected to resume in Abu Dhabi on November 10-11 despite substantial disagreements between Moscow and Kyiv.
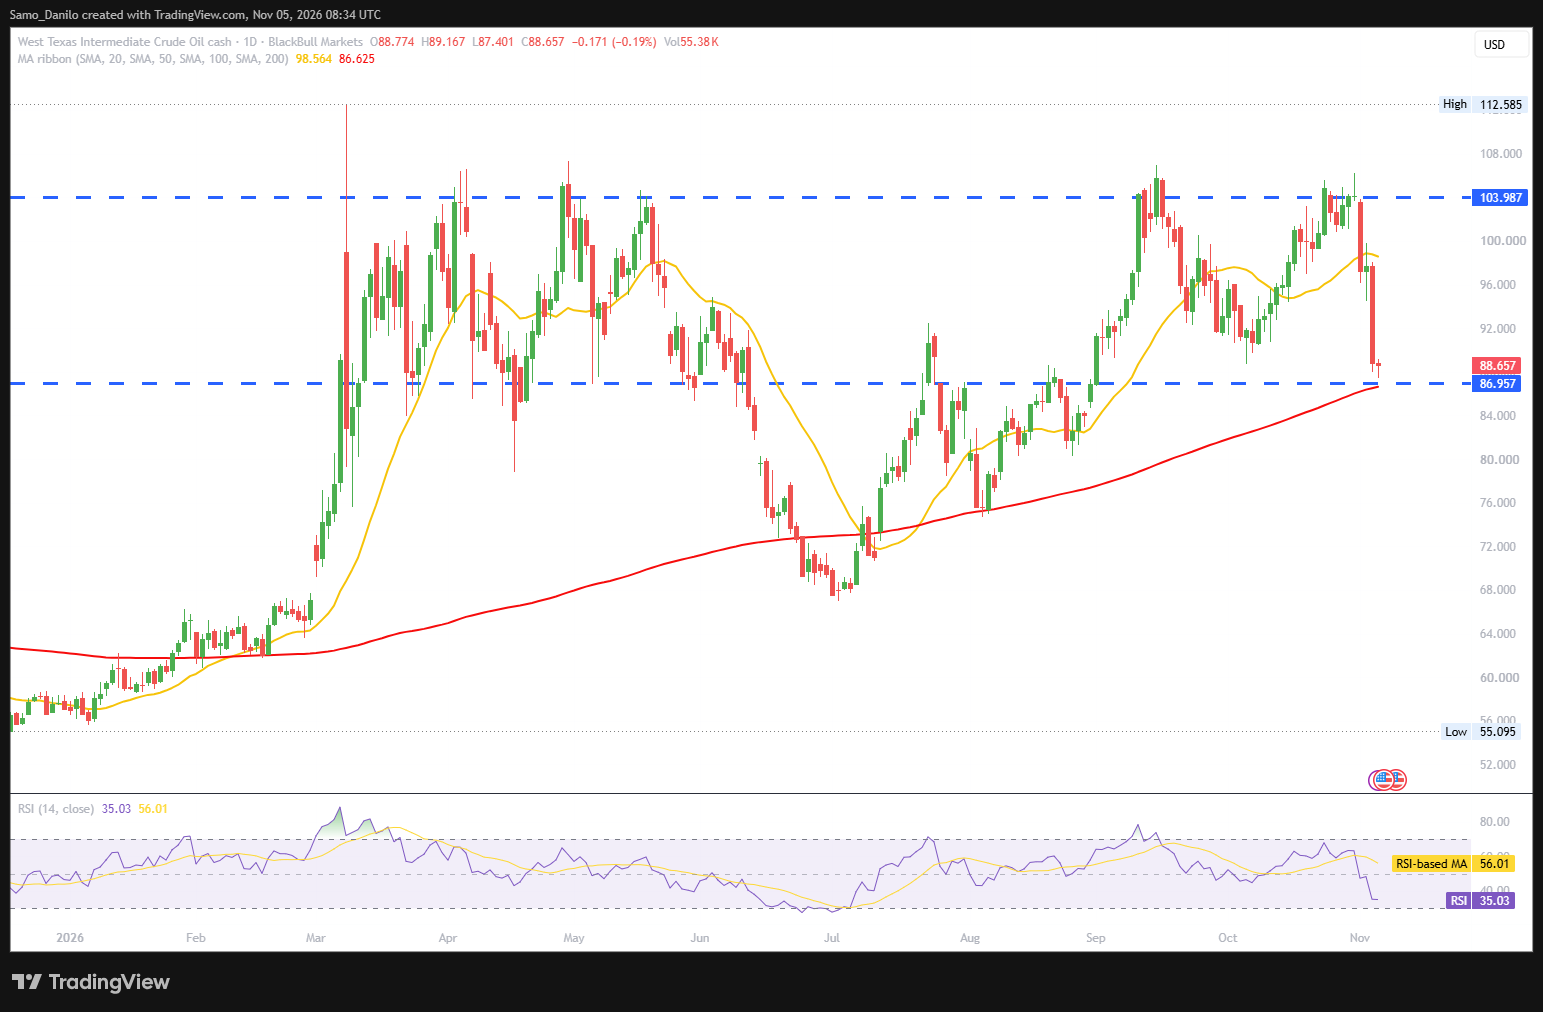
| SMA (20) | Slightly Rising | |
|
| RSI (14) | Falling | | |
| MACD (12, 26, 9) | Slightly Falling | |
Closing statement: WTI faces a cautiously bearish short-term outlook around $88.60, as expectations of reduced geopolitical tensions and record US production are weighing on prices. Further progress towards ending the Iran conflict could reduce the geopolitical risk premium and expose crude oil to additional downside pressure. However, any renewed escalation around the Strait of Hormuz, stronger supply disruptions or a sustained decline in US inventories could quickly revive bullish momentum.
DAX
- DAX 40 Price: Germany's benchmark DAX 40 was trading lower at approximately 26,590 points on Thursday morning, following the fresh all-time high recorded during Wednesday's session.
- Factory orders: German factory orders increased by 4.4% month-on-month in September, recovering from a 10.1% decline in August, which was revised from -10.6%. However, the reading fell short of the 4.8% market expectation, indicating that manufacturing activity is showing signs of recovery but remains uneven.
- Services PMI: The final eurozone Services PMI for October was revised down to 51.4 from the preliminary estimate of 51.7. The downward adjustment was somewhat unexpected following Monday's stronger-than-anticipated manufacturing PMI.
- ECB's Kazaks: ECB policymaker Martins Kazaks stated that interest rates may need to rise if inflationary pressures begin spreading more broadly across the economy. He also indicated that any increases could be gradual, reinforcing expectations that the ECB may maintain a cautious but restrictive approach to monetary policy.
- Corporate earnings: Commerzbank, which is widely viewed as a potential takeover target for UniCredit, is scheduled to release its third-quarter results. Investors will also assess earnings from Siemens Healthineers, DHL and Hochtief for further insight into the performance of key German corporate sectors.
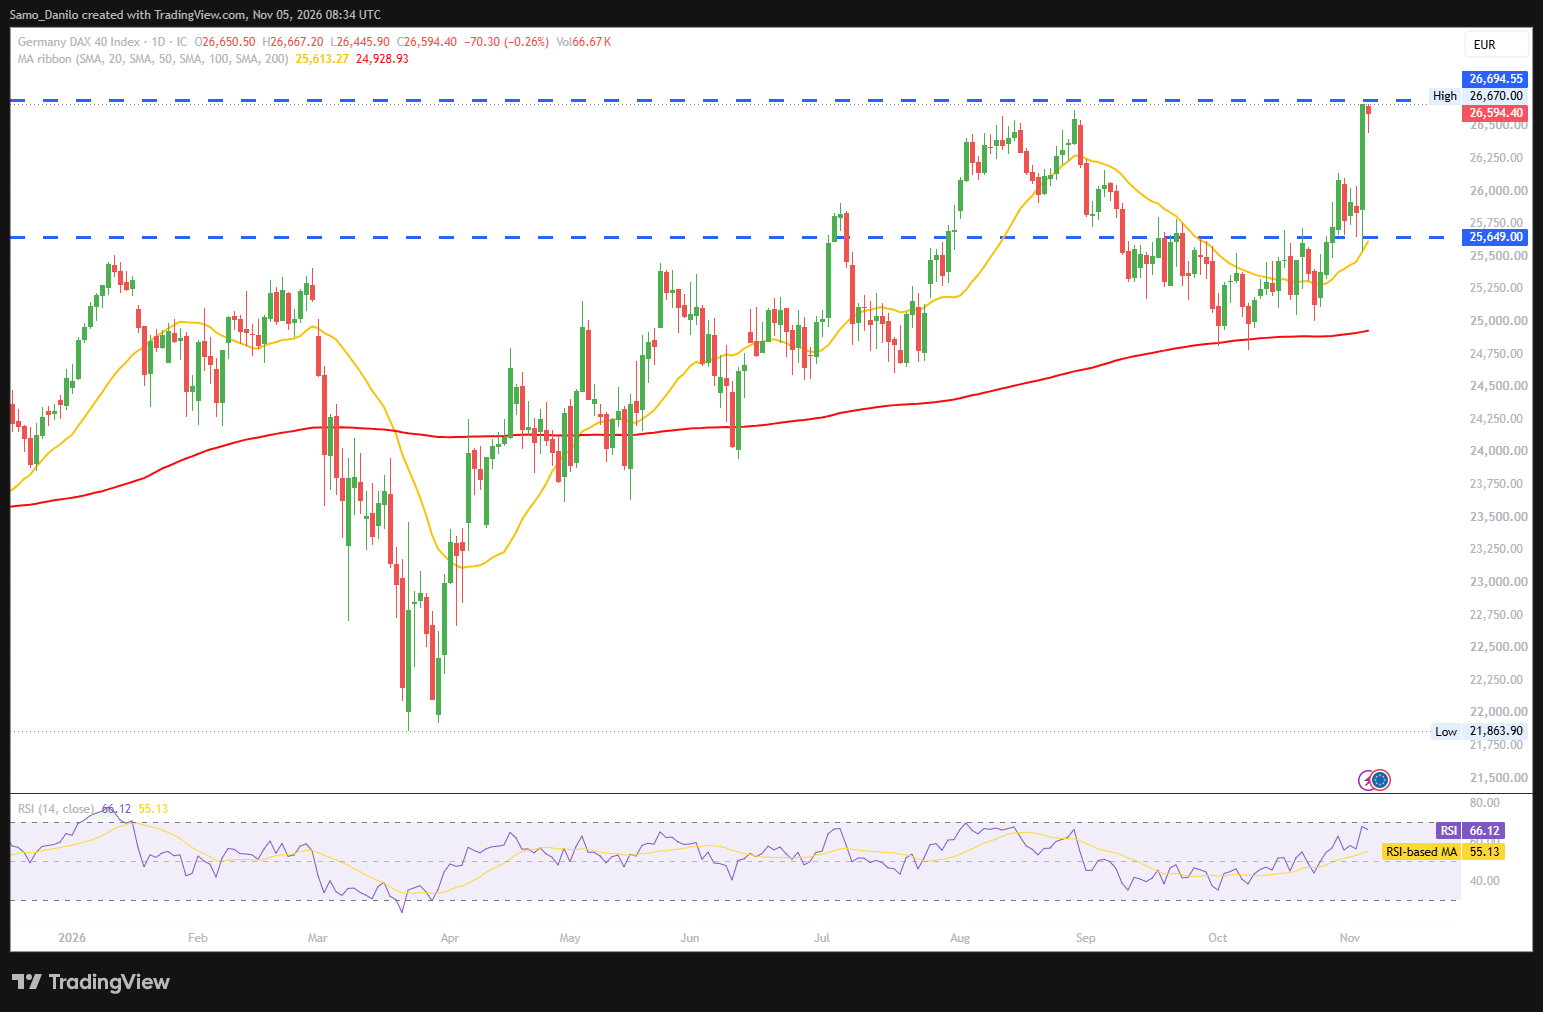
| SMA (20) | Slightly Rising | |
|
| RSI (14) | Rising | | |
| MACD (12, 26, 9) | Rising | | |
Closing statement: Despite Thursday's modest pullback towards 26,590, the DAX 40 retains a cautiously bullish broader outlook following Wednesday's record high. Stronger factory orders and upcoming corporate earnings could provide support, while weaker services activity and expectations of further ECB rate increases may limit additional upside. A recovery towards the recent all-time high would reinforce bullish momentum, whereas continued profit-taking could lead to a deeper correction.