EURUSD
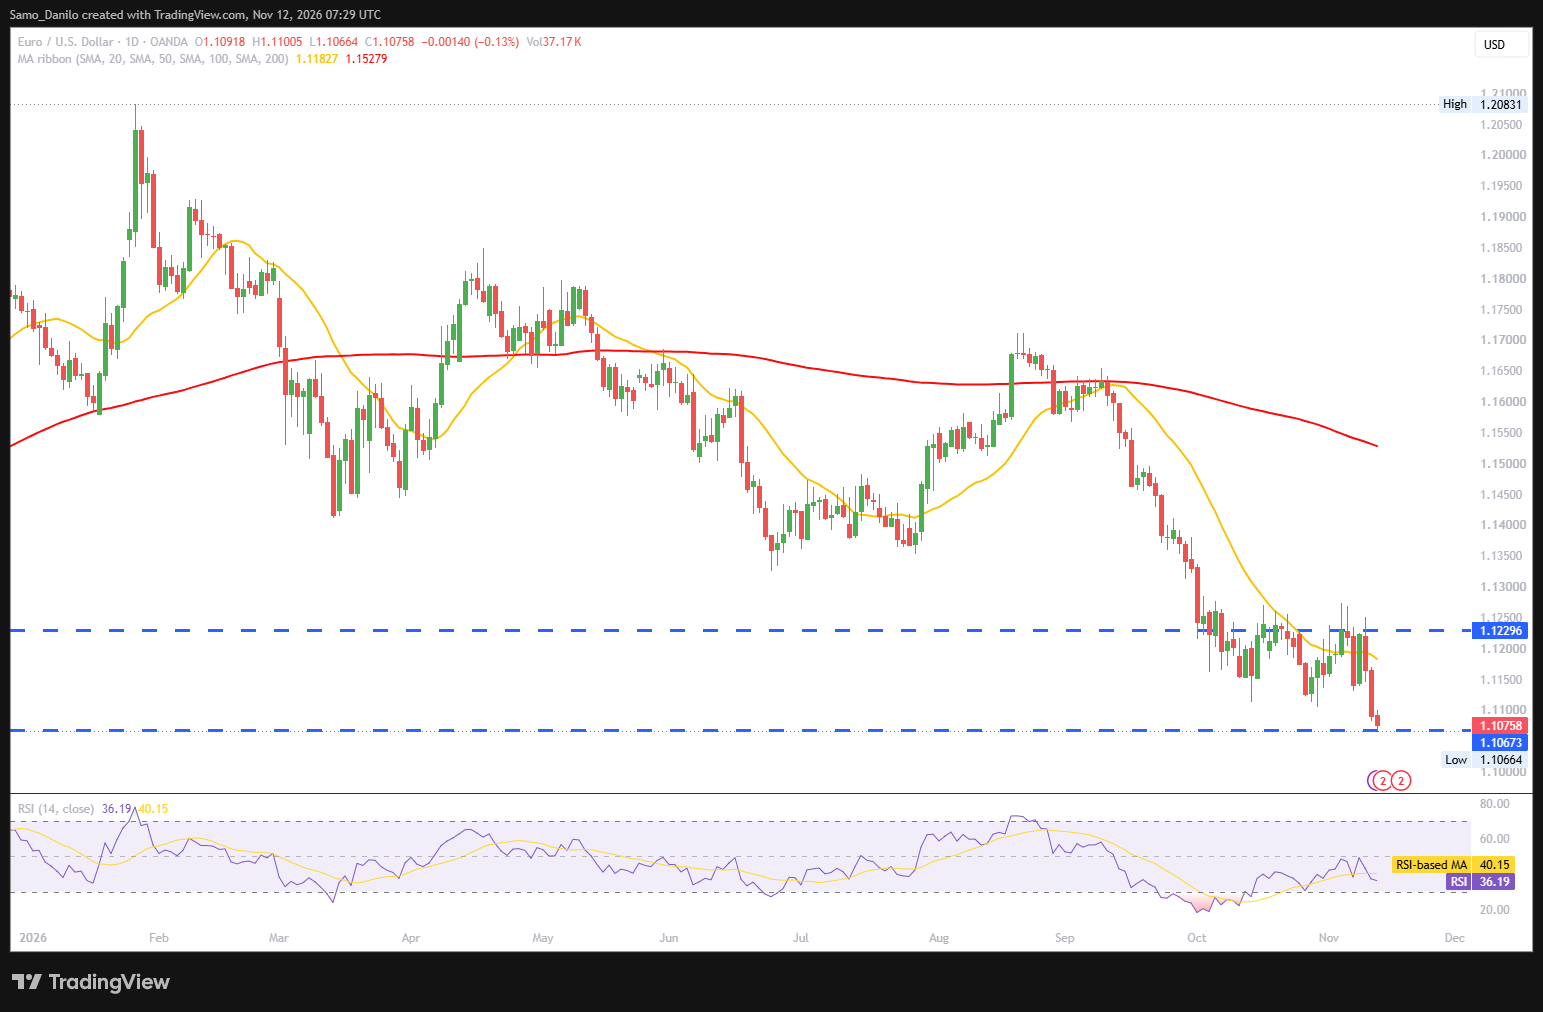
- EUR/USD Price: The EUR/USD pair declined towards the 1.1080 level during early European trading on Thursday.
- ECB's Lane: ECB policymaker Philip Lane noted that energy prices may be declining, but future interest rate decisions will depend on how much the recent increase in fuel costs feeds through to wages and other prices.
- Rabobank outlook: Rabobank considers market expectations for ECB rate increases in 2027 to be too aggressive. The bank also highlights political uncertainty in France, warning that a potential far-right presidency could raise questions about future European Union cooperation and weigh on the Euro in the coming months.
- ECB's Makhlouf: ECB policymaker Gabriel Makhlouf of Ireland stated that price pressures remain largely confined to the energy sector, although upside risks persist.
- Fed's Waller: Fed Governor Christopher Waller said he would support a 25-basis-point rate increase in December, while leaving open the possibility of a 50-basis-point move if inflation data proves worse than expected.
| SMA (20) | Falling |  | |
| RSI (14) | Falling | | |
| MACD (12, 26, 9) | Slightly Falling | |
Closing statement: EUR/USD faces continued downside risks as hawkish Fed expectations support the US Dollar, while uncertainty surrounding the ECB’s future policy path and French political developments weigh on the Euro. A sustained recovery will require stronger support from eurozone fundamentals, while further hawkish signals from the Fed could keep the pair under pressure.
GBPUSD
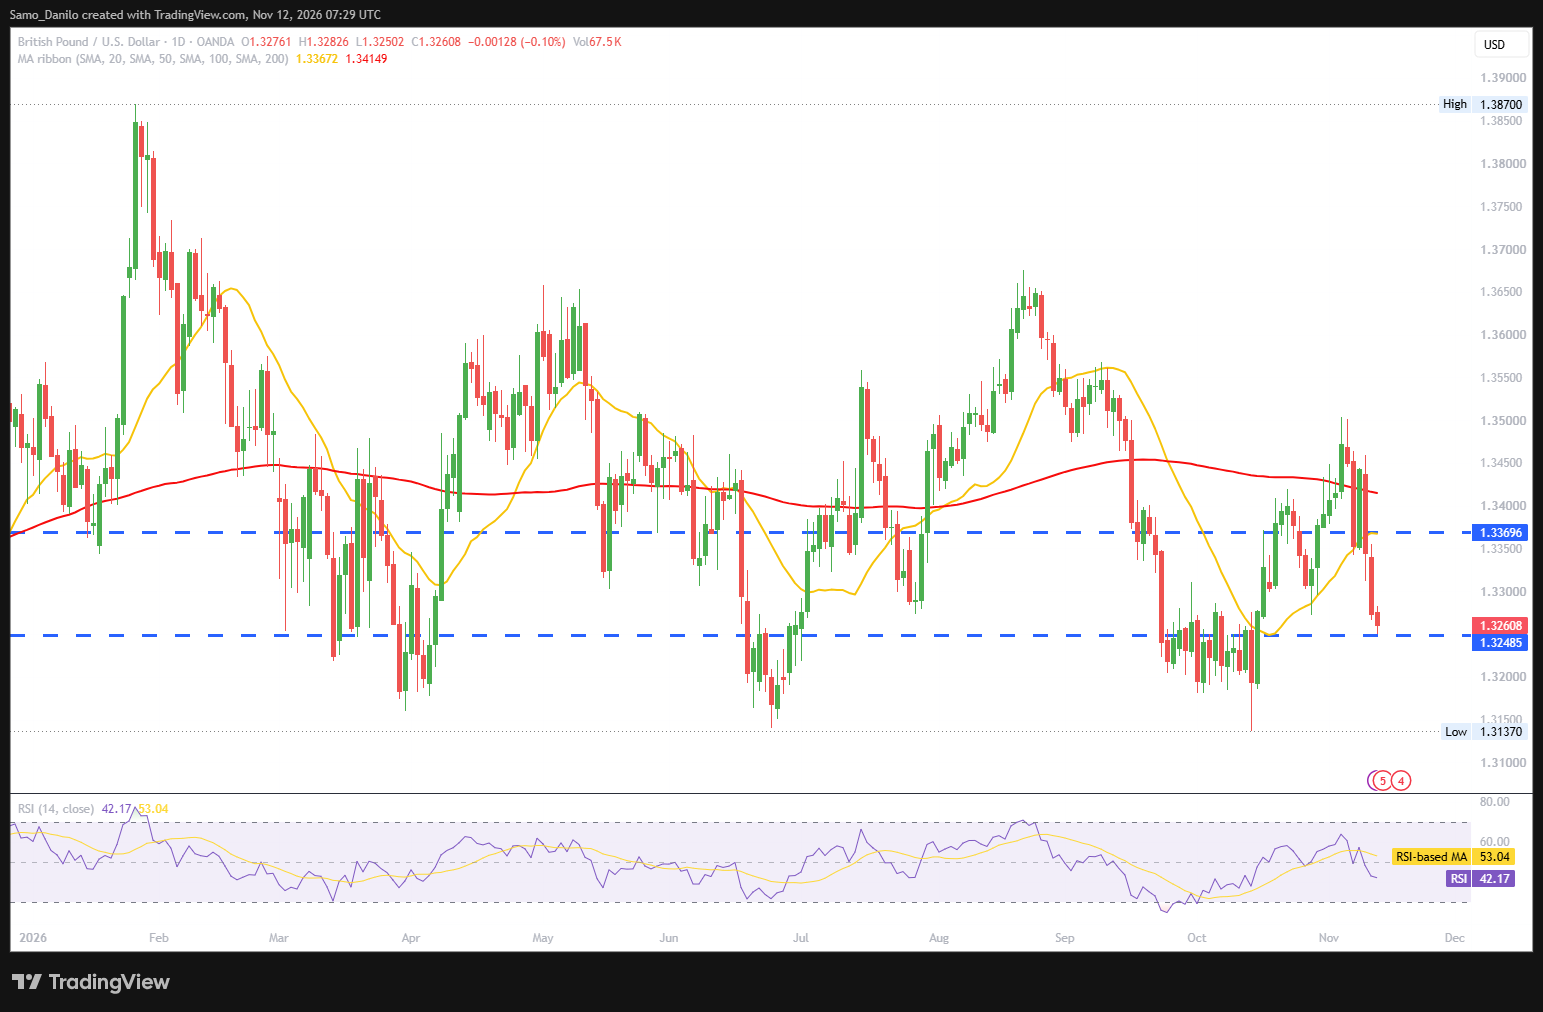
- GBP/USD Price: The GBP/USD pair declined for a third consecutive session, recording losses in five of the previous six trading days and reaching a fresh four-week low during Thursday’s European session. The pair traded just above the mid-1.3200s, reflecting sustained bearish pressure on Sterling.
- UK GDP: The UK economy expanded by 0.7% quarter-on-quarter in the three months to September 2026, following a revised 1% contraction in Q2, compared with the previously reported 0.5% growth. Annual GDP growth reached 1.9%, matching expectations and accelerating from 1.4% in the previous quarter.
- Other data: UK Industrial Production increased by 0.3% month-on-month in September, while Manufacturing Production rose by 0.7% over the same period. Both readings exceeded market expectations, providing additional evidence of resilience in the UK industrial sector.
- US Dollar: Following Tuesday’s stronger-than-expected US inflation figures, hawkish comments from several Federal Reserve officials reinforced market expectations of an imminent interest rate increase.
- Fed officials: Wednesday’s US economic calendar features several Federal Reserve speakers, including John Williams, Beth Hammack, Austan Goolsbee, and Mary Daly.
| SMA (20) | Slightly Rising |  |
|
| RSI (14) | Falling | | |
| MACD (12, 26, 9) | Slightly Rising | |
Closing statement: GBP/USD remains under significant pressure despite stronger-than-expected UK growth and industrial production figures, as hawkish Fed expectations continue to favour the US Dollar. A sustained recovery will require improved Sterling sentiment, while further hawkish signals from Fed officials could keep the pair biased to the downside.
XAUUSD
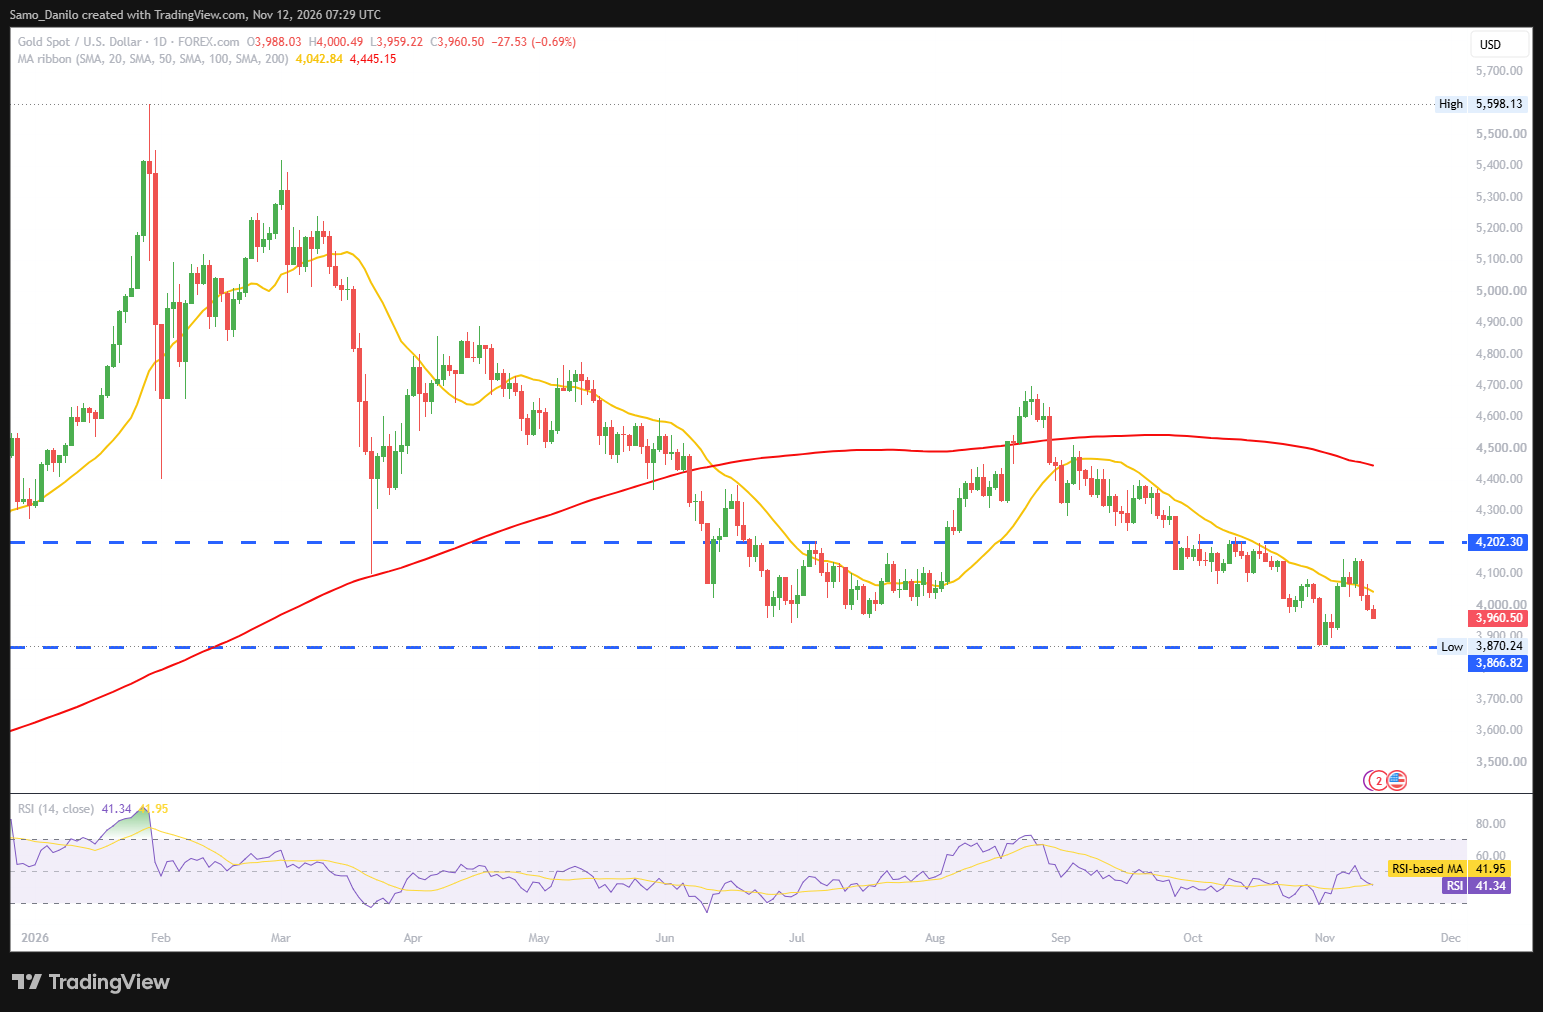
- XAU/USD Price: Gold (XAU/USD) maintained its bearish momentum for a third consecutive session on Thursday, falling below the psychological $4,000 level and trading near a more-than-one-week low recorded during the Asian session. Spot prices were hovering around $3,960, reflecting continued selling pressure on the precious metal.
- Fed rate: Rabobank analysts noted that the market reaction to recent hawkish signals from Federal Reserve officials, including Christopher Waller's comments raising the possibility of a 50-basis-point rate hike, extends beyond the immediate repricing of the monetary policy outlook.
- Diplomatic developments: US representatives Jared Kushner and Steve Witkoff are scheduled to travel to Moscow on Thursday before meeting Ukrainian President Volodymyr Zelenskyy later in Dublin.
- Nvidia again: Nvidia's board is meeting on Thursday to decide whether to oust CEO Jensen Huang following a revealed affair with a suspected Chinese spy. Overnight there were multiple reports on another affair involving Huang and Kimberly Powell, the chipmaker's VP of healthcare. Nvidia's shares dropped sharply in after-hours trading.
- US PPI: Traders are awaiting Friday’s US October Producer Price Index (PPI) report for additional clues about the Federal Reserve’s interest rate outlook. Headline PPI is expected to increase by 6.6% year-on-year, while core PPI is projected to rise by 5.0%, making the release important for assessing underlying inflationary pressures.
| SMA (20) | Slightly Falling | |
| RSI (14) | Slightly Falling | |
| MACD (12, 26, 9) | Slightly Falling | |
Closing statement: Gold remains under strong bearish pressure below $4,000, with hawkish Fed expectations and the prospect of higher interest rates weighing on prices. The $3,960 area is an important near-term reference point, while Friday’s US PPI report could determine whether selling pressure intensifies or the metal finds room for a recovery.
CRUDE OIL
- Crude Oil Price: West Texas Intermediate (WTI), the US crude oil benchmark, traded around $87.30 per barrel during early European trading on Thursday.
- Strait of Hormuz: The standoff between the US and Iran over the Strait of Hormuz continues, with both sides reportedly targeting islands in the strategic waterway in recent days. US forces allegedly carried out strikes on Iran's Qeshm Island, while Tehran attacked ship navigation systems on Oman's Didamar Island, near the entrance to the Persian Gulf, raising concerns about the security of a critical global energy transit route.
- US-Iran: Reports indicate that President Donald Trump is open to allowing Vice President JD Vance to reopen negotiations with Iran and has authorized him to pursue diplomatic efforts. According to the Wall Street Journal, Vance is considering face-to-face talks with Iranian security chief Mohsen Rezaei.
- Ukraine-Russia: Peace negotiations involving Ukrainian, Russian, and US officials in Abu Dhabi concluded on Tuesday, with both sides reporting some progress. Among the developments was an agreement on a prisoner exchange, although broader geopolitical uncertainties remain unresolved.
- Democratic control: Commerzbank analysts noted that oil markets remain volatile as investors assess whether Democratic control of Congress could accelerate diplomatic efforts to end the US-Iran conflict.
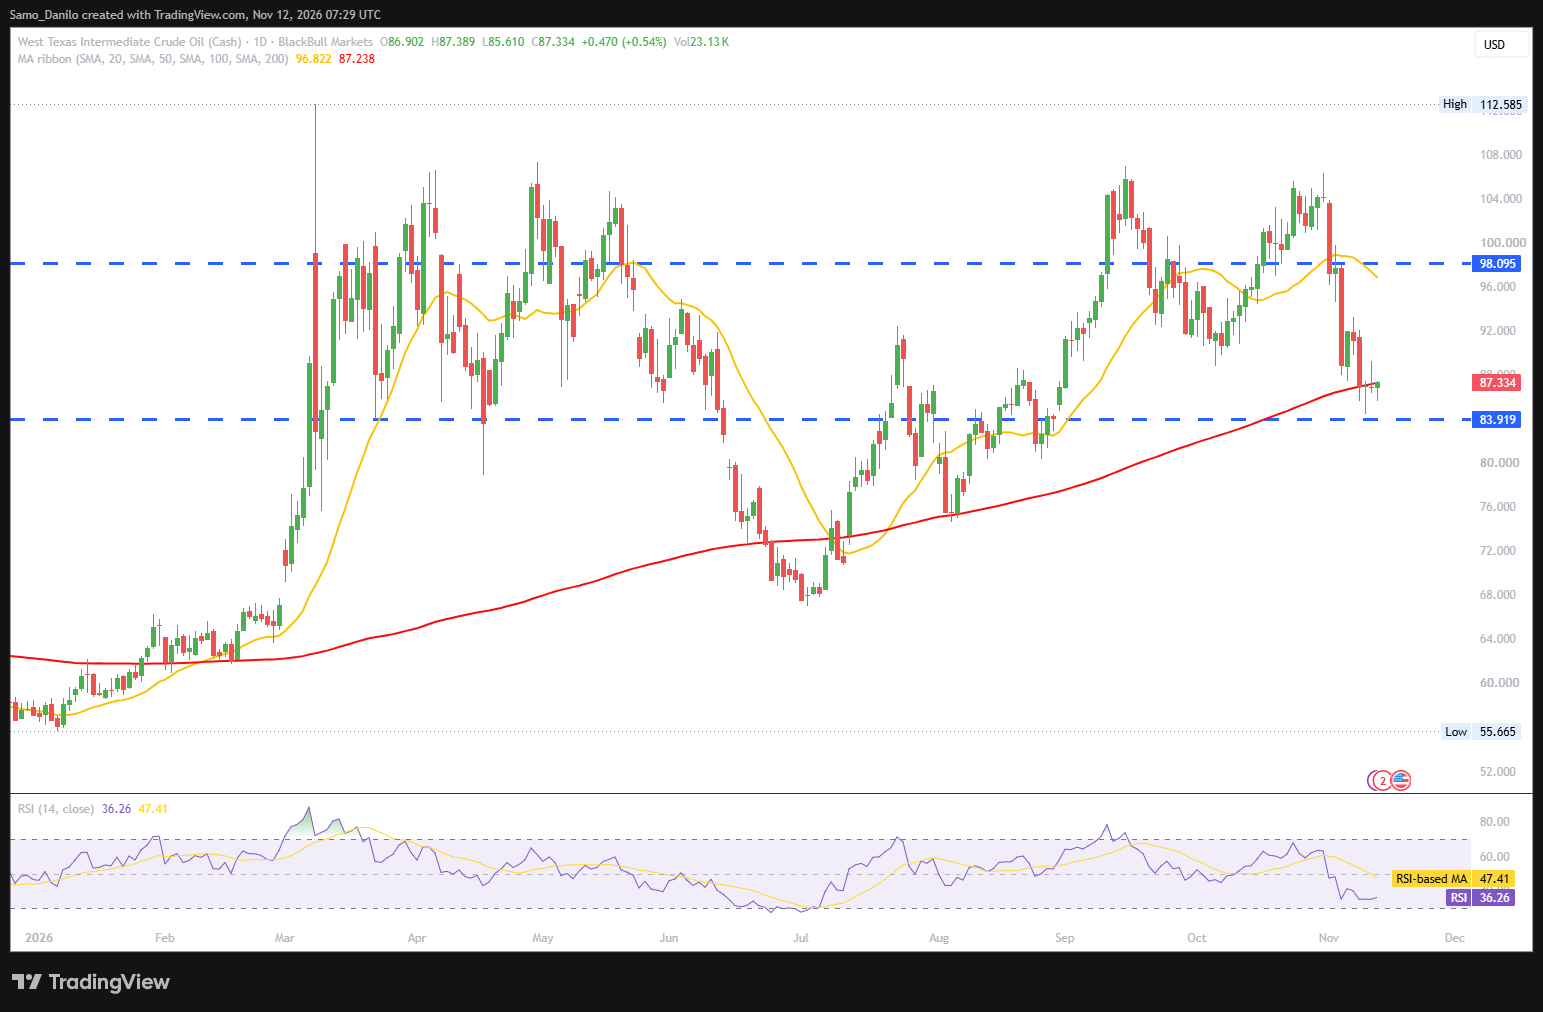
| SMA (20) | Slightly Rising | |
|
| RSI (14) | Falling | | |
| MACD (12, 26, 9) | Slightly Falling | |
Closing statement: WTI remains supported by escalating tensions around the Strait of Hormuz, although the possibility of renewed US-Iran negotiations could limit further gains. The market is likely to remain highly sensitive to geopolitical headlines, with further escalation posing upside risks and diplomatic progress potentially triggering a correction.
DAX
- DAX 40 Price: The DAX 40 is trading higher around the 26,900-point mark on Thursday, setting new all-time highs.
- AAA rating: German Chancellor Friedrich Merz stated that the country must do everything possible to preserve its AAA credit rating, while Finance Minister Lars Klingbeil emphasized that Germany's sovereign rating is not currently at risk.
- Siemens reports: Siemens reported a significant increase in fourth-quarter net profit, rising to €2.16 billion from €1.62 billion a year earlier, supported by record order intake and double-digit revenue growth in its Smart Infrastructure and Digital Industries divisions. The company also achieved record profit in its industrial business, highlighting resilient demand across key operations.
- Merck guidance: German pharmaceutical and technology group Merck KGaA raised its 2026 core profit guidance for the third time this year. The improved outlook reflects stronger underlying business performance, favourable foreign exchange effects, and the acquisition of US-based Bio-Techne.
- Earnings season: The German corporate earnings season is approaching its conclusion, with major DAX constituents Allianz and Munich Re scheduled to report their results. A significant number of additional quarterly reports are also expected from SDAX-listed companies, keeping corporate performance in focus.
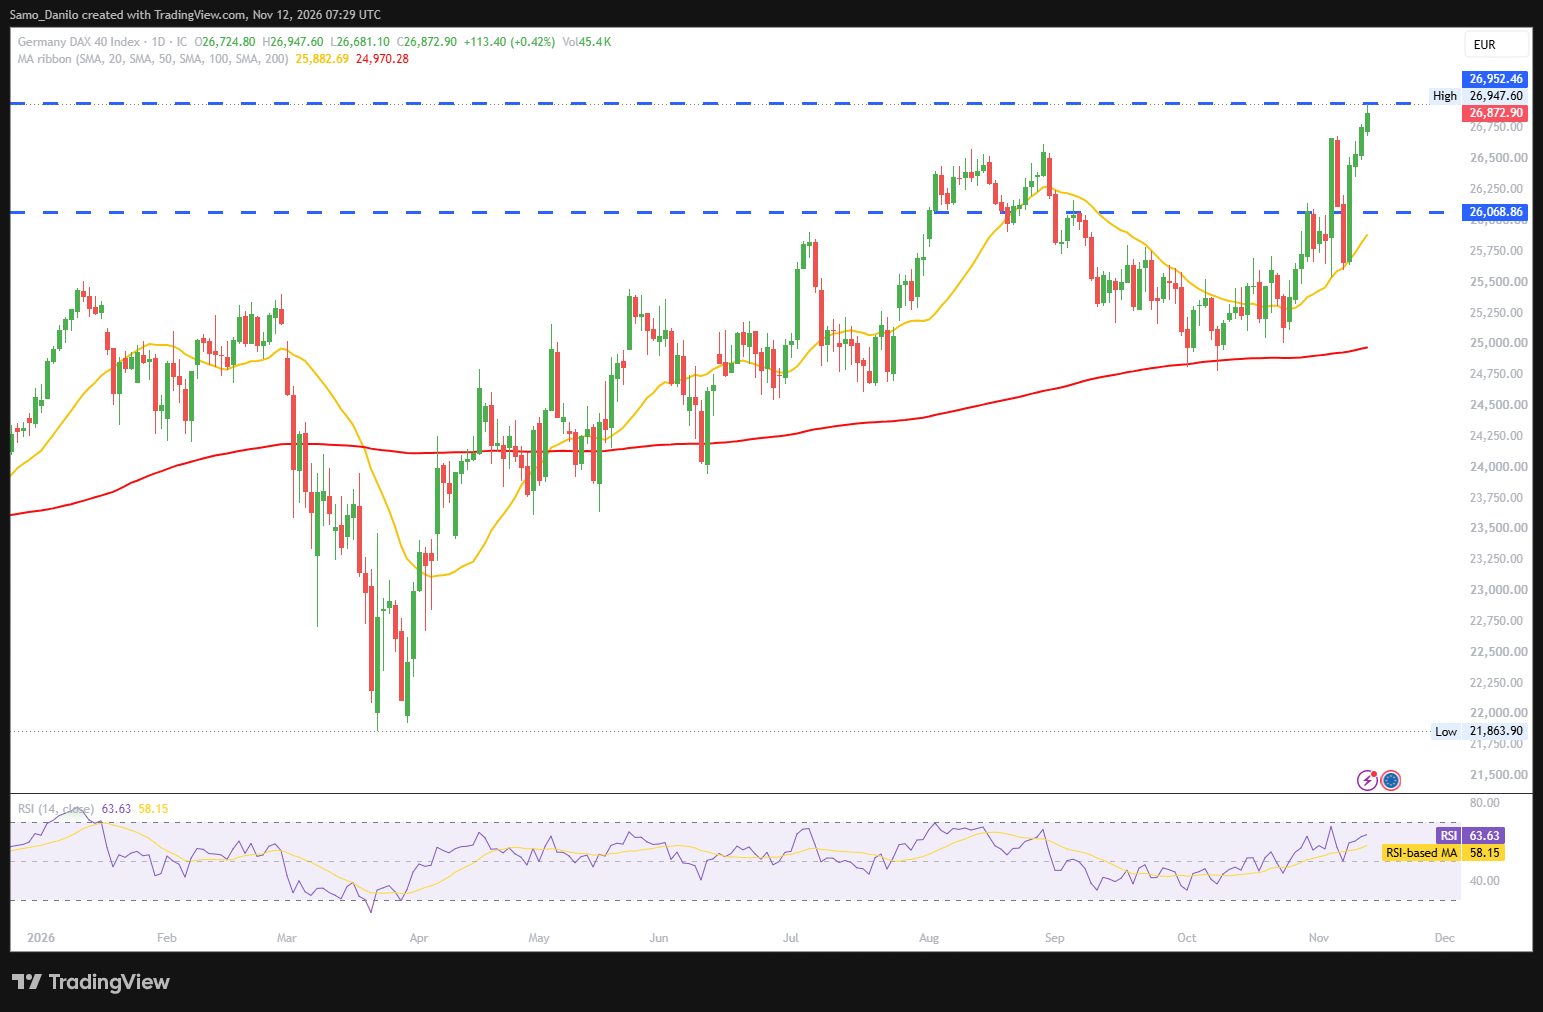
| SMA (20) | Slightly Rising | |
|
| RSI (14) | Rising | | |
| MACD (12, 26, 9) | Rising | | |
Closing statement: The DAX maintains a strong bullish trend near 26,900 points, supported by fresh record highs, encouraging corporate earnings, and positive guidance from major companies. Continued strength in the earnings season could provide further upside momentum, while upcoming results from Allianz and Munich Re may influence the index's next move.