EURUSD
- EUR/USD Price: The EUR/USD pair is attracting sellers and trading around the 1.0970 level during early European trading on Wednesday.
- US Dollar: Stronger-than-expected US inflation reports, combined with hawkish comments from Federal Reserve officials, have reinforced expectations of a December interest rate hike.
- Inflation projections: The European Commission expects euro area inflation to average 3.1% year-on-year in 2027 and 2.1% in 2028, with core inflation projected at 2.6% and 2.1%, respectively.
- ECB's Vujcic: ECB policymaker Boris Vujcic said that market expectations for monetary tightening in 2027 could prove accurate, adding that a December rate hike alone might not be sufficient.
- Inflation data: Investors are awaiting the final October inflation figures for the euro area, which are expected to confirm the preliminary readings of 4.0% year-on-year for headline inflation and 2.5% for core inflation. However, rounding effects could result in a slight upward revision of core inflation to 2.6%, given that the unrounded figure stood at 2.54%.
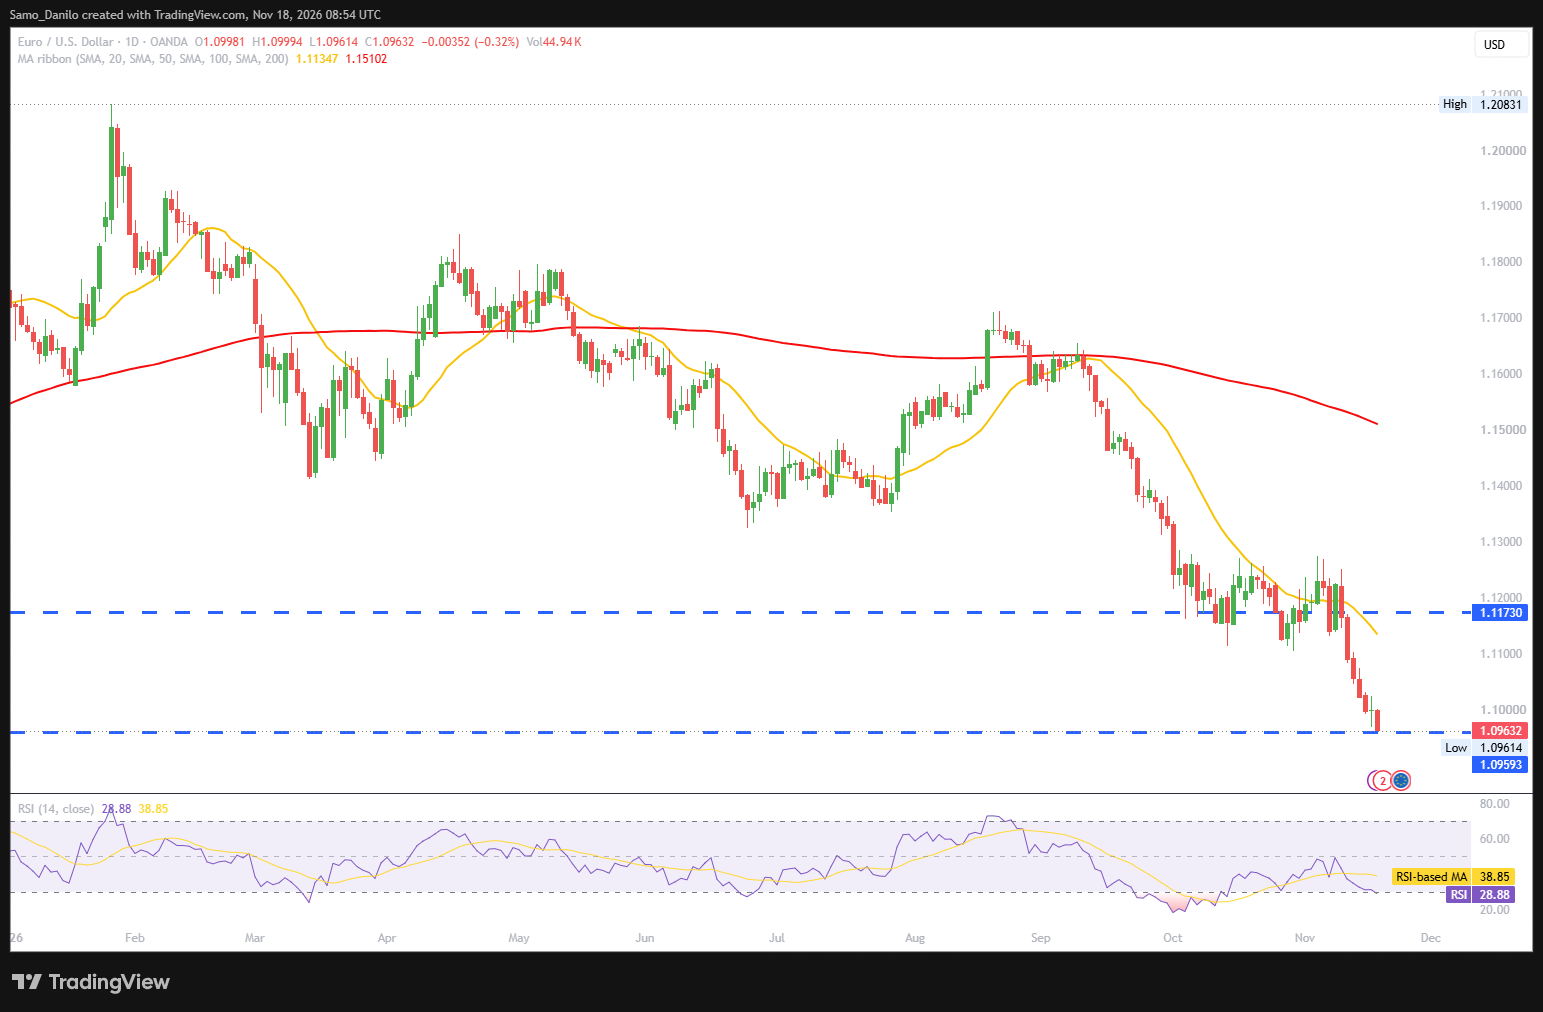
| SMA (20) | Falling |  | |
| RSI (14) | Falling | | |
| MACD (12, 26, 9) | Falling | | |
Closing statement: EUR/USD remains under pressure near 1.0970 as stronger US inflation and hawkish Fed expectations strengthen the dollar. However, expectations of further ECB tightening in 2027, supported by persistent eurozone inflation, could provide some medium-term support for the single currency. The final inflation release will be important for near-term direction, while continued dollar strength could expose the pair to further downside.
GBPUSD
- GBP/USD Price: The GBP/USD pair is trading just a few pips above Tuesday's one-month low of 1.3169, with the year-to-date low of 1.3137 now coming into focus.
- UK inflation: The UK's headline Consumer Price Index (CPI) increased by 3.6% year-on-year in October, up from 3.5% in September, according to data released by the ONS on Wednesday.
- Fed's Musalem: St. Louis Fed President Alberto Musalem said on Tuesday that several interest rate hikes may be necessary to bring elevated inflation under control, emphasizing the need for timely action.
- Retail sales: According to the US Census Bureau, retail sales increased by 0.2% month-on-month in October, compared with a 0.8% rise in the previous month.
- Meeting minutes: The Federal Reserve will release the minutes from its October policy meeting later on Wednesday.
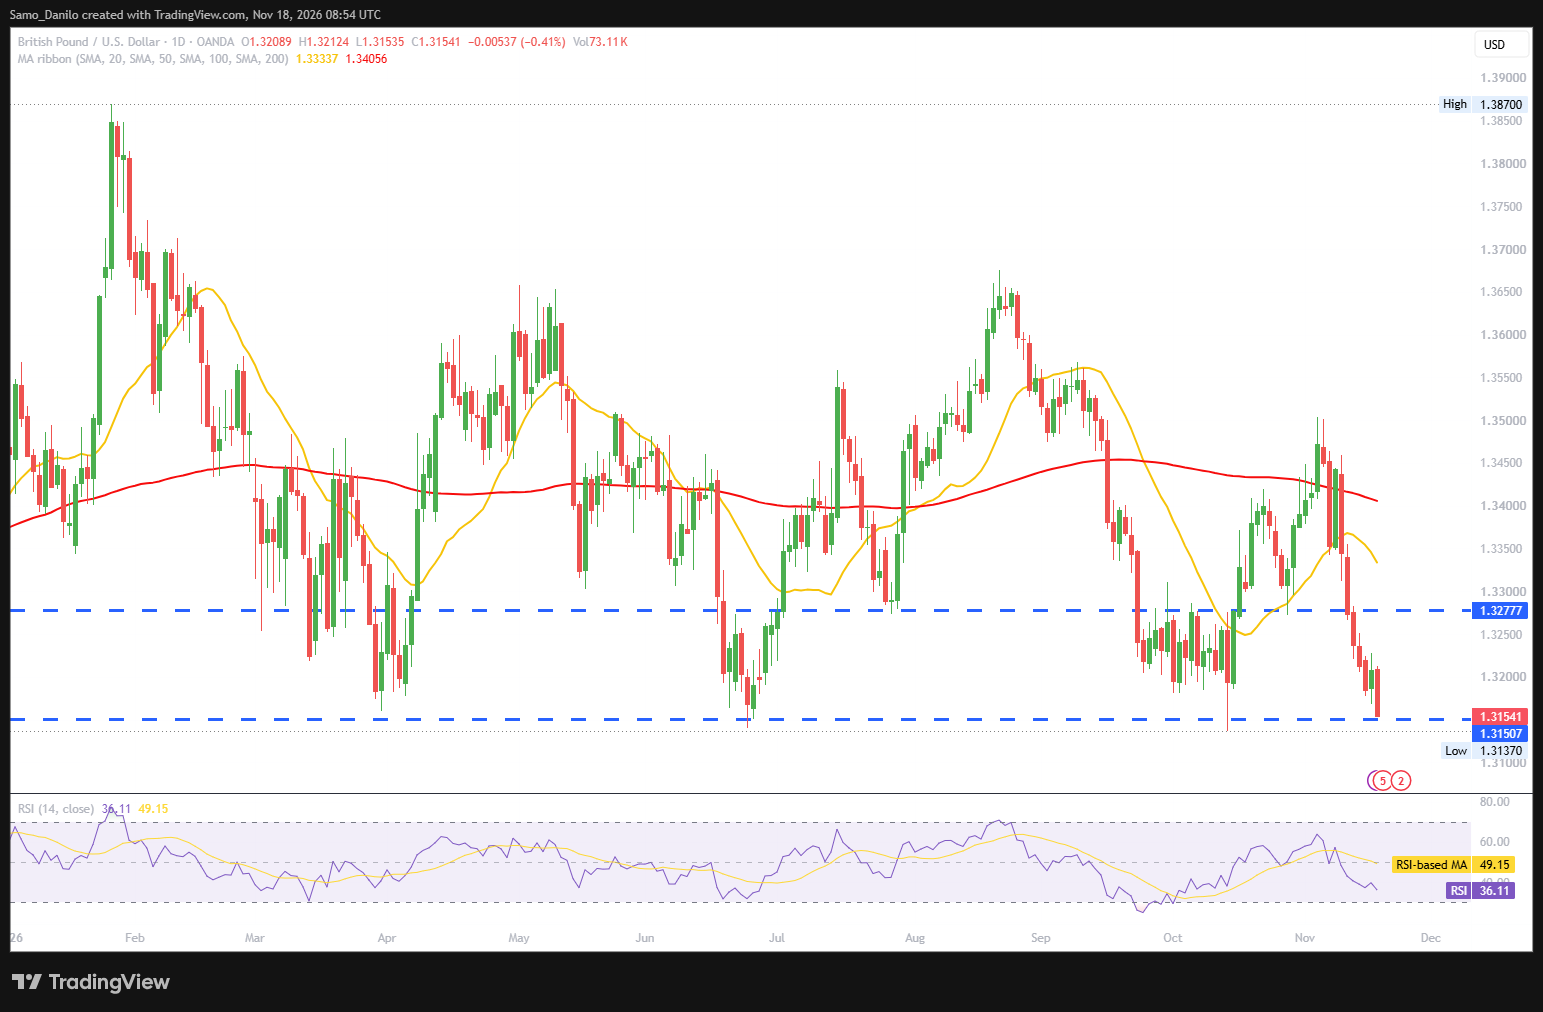
| SMA (20) | Slightly Rising |  |
|
| RSI (14) | Falling | | |
| MACD (12, 26, 9) | Falling | | |
Closing statement: GBP/USD remains under significant bearish pressure near its one-month low of 1.3169, with the year-to-date low of 1.3137 representing the next important downside reference. Although slightly higher UK inflation could offer some support to Sterling, hawkish Fed commentary continues to favour the US dollar. The October FOMC minutes could determine whether the pair extends its decline or attempts a short-term recovery.
XAUUSD
- XAU/USD Price: Gold prices encountered strong selling pressure around the $3,760 level during early European trading on Wednesday.
- Fed's Williams: Federal Reserve official John Williams, a permanent voting member, continued to favour tighter monetary policy while acknowledging that this is not the time for dramatic action. He also reaffirmed the Fed's commitment to bringing inflation back to its 2% target in a timely manner, reinforcing expectations that monetary policy will remain restrictive.
- Rate hike: According to the CME FedWatch tool, markets are pricing in a 95.7% probability of a 25-basis-point rate hike in December, while the odds of a larger 50-basis-point increase stand at 4.3%.
- APEC Summit: Investors are monitoring the APEC Summit taking place on Wednesday and Thursday in China, where a meeting involving Donald Trump, Xi Jinping and Vladimir Putin is expected.
- Nvidia results: Nvidia reported very strong financial results and guidance, with revenue beating expectations and its fourth-quarter outlook exceeding consensus estimates, even without assuming data-centre chip sales to China.
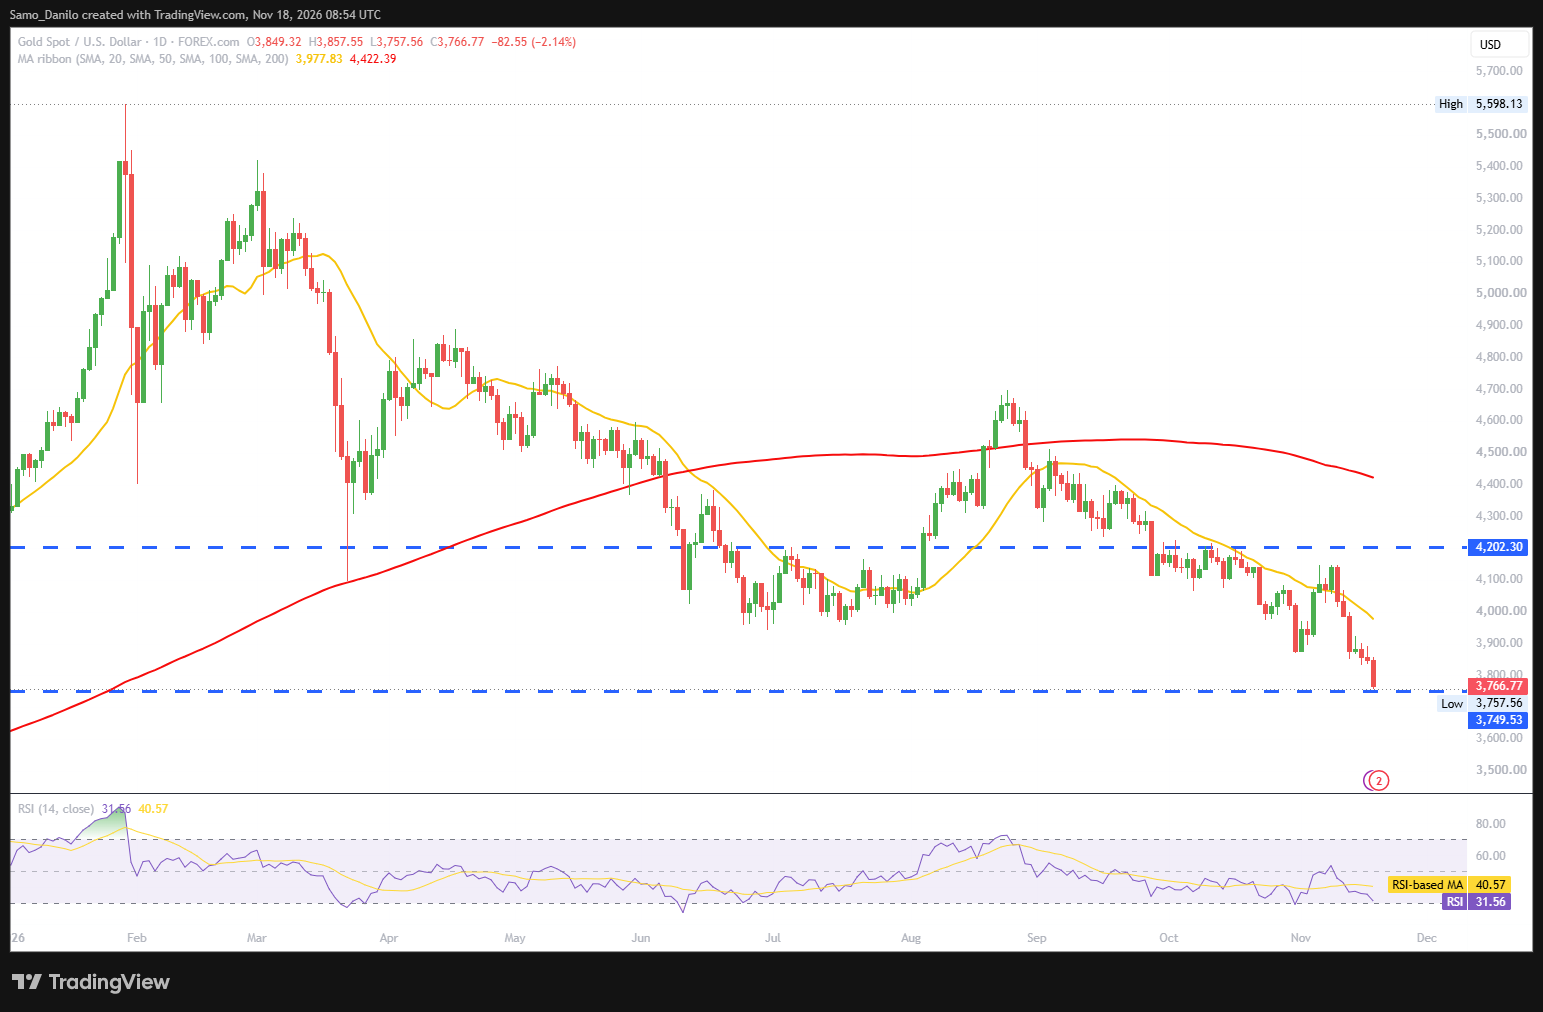
| SMA (20) | Slightly Falling | |
|
| RSI (14) | Falling | | |
| MACD (12, 26, 9) | Slightly Falling | |
Closing statement: Gold remains under bearish pressure near $3,760, with hawkish Fed expectations and the prospect of further monetary tightening limiting demand for the precious metal. The APEC Summit and anticipated high-level diplomatic meeting could influence safe-haven demand, depending on the outcome of discussions. Unless XAU/USD manages to regain upward momentum, the broader outlook remains tilted to the downside.
CRUDE OIL
- Crude Oil Price: West Texas Intermediate (WTI), the US crude oil benchmark, is currently trading near the $84.00 per barrel level.
- US strikes: A US military official confirmed that American fighter aircraft struck an Islamic Revolutionary Guard Corps missile launch site on Qeshm Island.
- Trump signals: US President Donald Trump said he would hold bilateral talks with Russian President Vladimir Putin if the opportunity arises, while confirming that Taiwan would be discussed during his meeting with Chinese President Xi Jinping. Trump also said he would press both leaders to help end the war in Ukraine and suggested that the US could catch up with China in rare earths within ten months.
- Crude inventories: The American Petroleum Institute (API) estimated that US crude oil inventories increased by 5.3 million barrels in the week ending November 13.
- Russian crude: Russia loaded more than 30 million barrels of crude onto tankers last week as Ukrainian drone strikes forced additional oil away from domestic refineries and into export markets. According to Bloomberg vessel-tracking data, 39 tankers carried 30.27 million barrels in the week ending November 15, compared with 23.6 million barrels loaded by 31 vessels the previous week, indicating a significant increase in export flows.
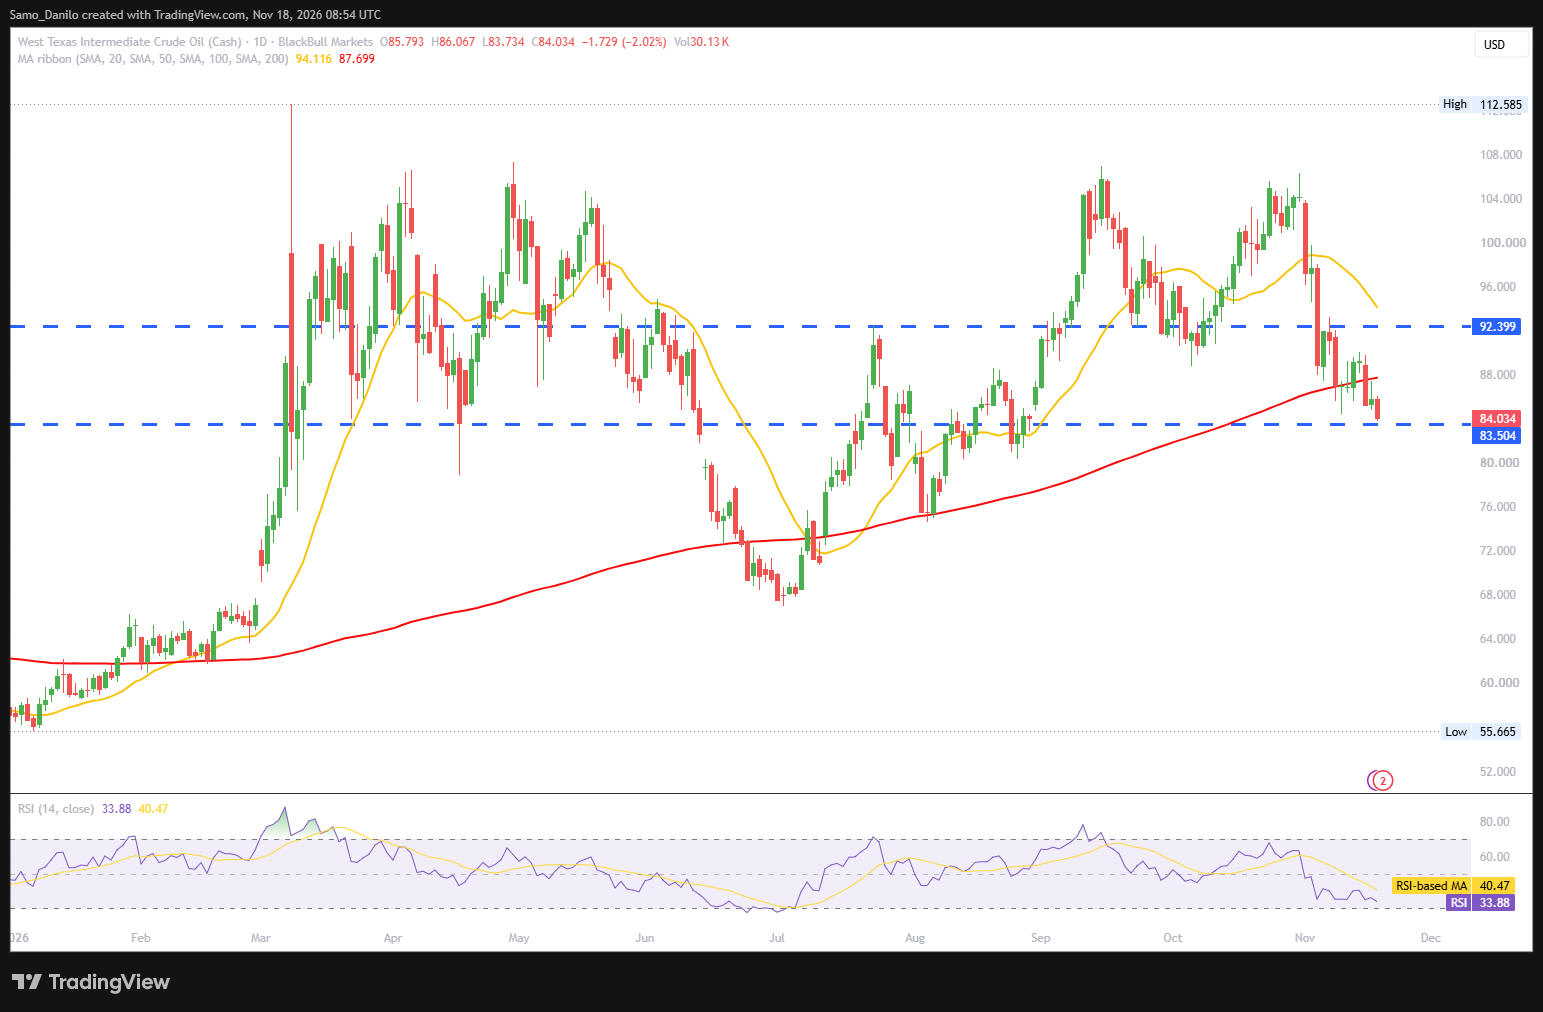
| SMA (20) | Slightly Falling | |
|
| RSI (14) | Falling | | |
| MACD (12, 26, 9) | Falling | | |
Closing statement: WTI remains supported by escalating US-Iran tensions and the potential threat of further supply disruptions, although rising US inventories and increased Russian crude exports represent important bearish factors. The $84.20 area remains a key near-term reference point, with further military developments likely to influence volatility. A sustained escalation could push prices higher, while continued inventory builds and stronger export flows may increase downside pressure.
DAX
- DAX 40 Price: Germany's benchmark index has remained in correction territory since reaching a record high last week, with investors recently showing less appetite for German equities. The index is currently trading around the 26,100-point level, reflecting a more cautious market environment.
- ECB rate: The European Central Bank is widely expected to deliver a final interest rate hike in December, although persistent inflation risks could leave the door open for further tightening.
- ZEW sentiment: Germany's November ZEW survey surprised positively, with the assessment of the current economic situation improving to -33.2 from -35.9, beating expectations of -35.3. Economic expectations also increased to 35.6 from 28.1, significantly above the consensus forecast of 28.8, suggesting growing optimism about the German economic outlook.
- German inflation: Germany's final October CPI figures showed a month-on-month decline of 0.1%, compared with the preliminary estimate of -0.2%. Meanwhile, harmonized CPI inflation was revised upward to 2.9% year-on-year from the preliminary 2.8%, indicating slightly stronger price pressures than initially reported.
- Deutsche Bank: Deutsche Bank shares fell 1.9% in Wednesday's opening trade, extending Tuesday's 6% decline following the leak of a substantial collection of internal records. The reports have renewed scrutiny of the bank's historical dealings with several high-profile clients, including Russian oligarchs, US President Donald Trump and Jeffrey Epstein, with Tuesday's decline marking its largest single-day fall in more than a year.
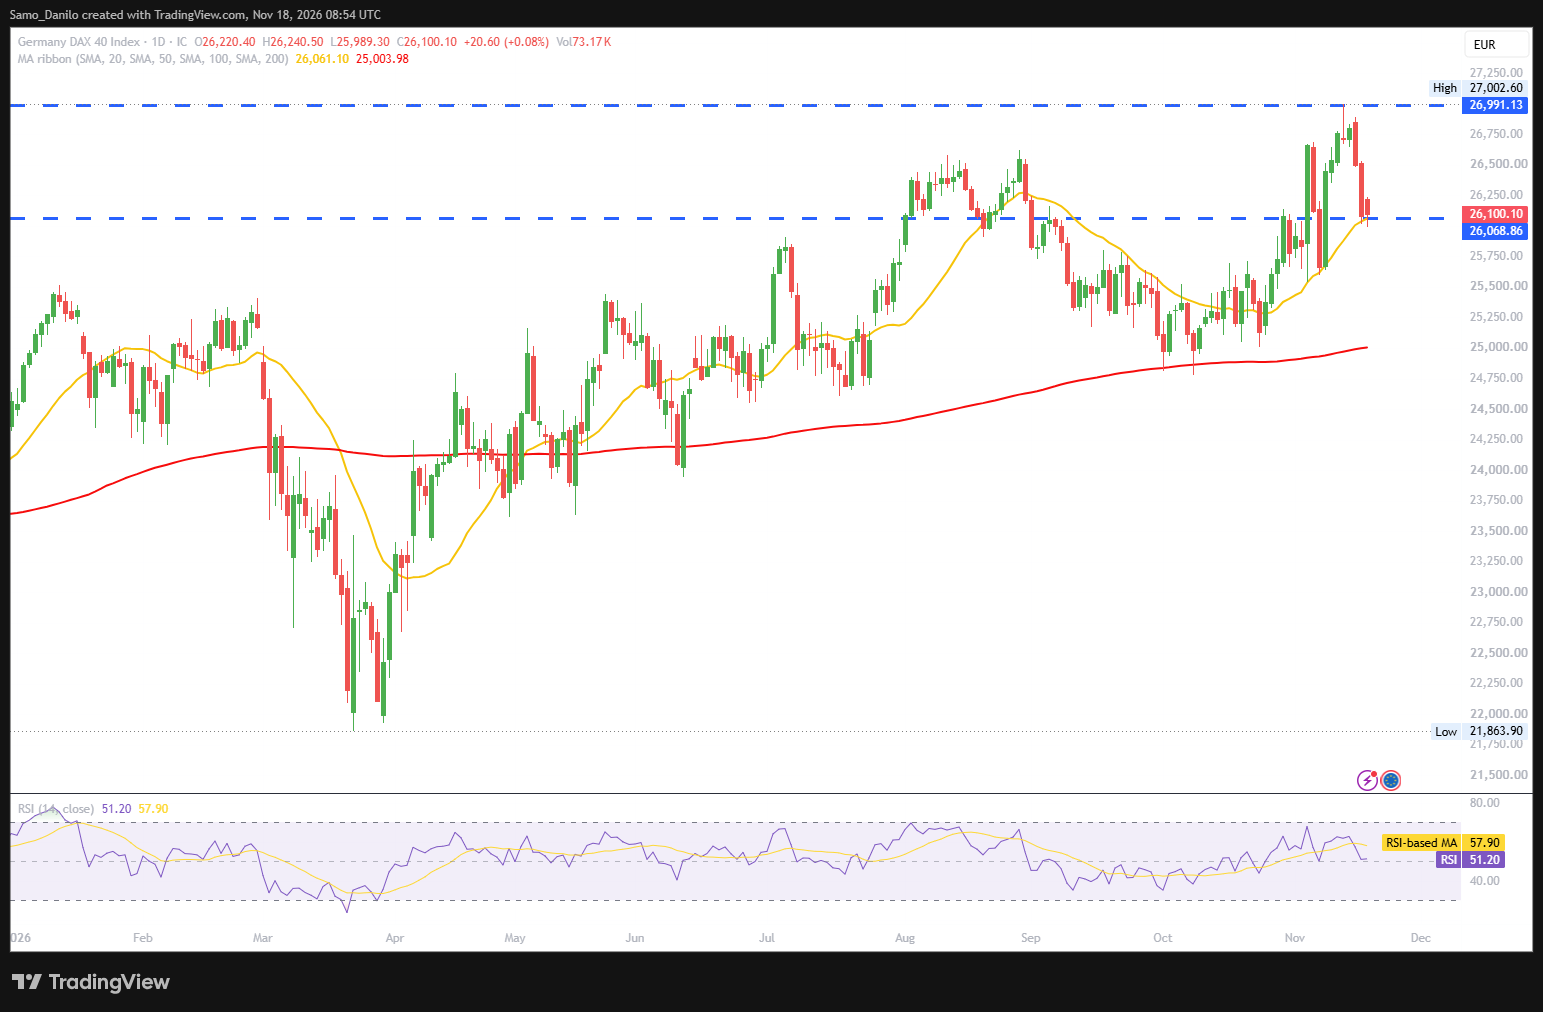
| SMA (20) | Rising | | |
| RSI (14) | Slightly Rising | |
|
| MACD (12, 26, 9) | Slightly Rising | |
Closing statement: The DAX 40 remains under pressure around 26,100 points following last week's record high, while expectations of further ECB tightening and renewed scrutiny of Deutsche Bank weigh on sentiment. However, the stronger-than-expected ZEW survey provides a positive signal for Germany's economic outlook and could help limit further losses. Investors will continue to assess inflation developments and the ECB's policy outlook, with the broader market direction dependent on whether improving economic sentiment can offset monetary tightening concerns.