EURUSD
- EUR/USD Price: The EUR/USD pair remains in positive territory around 1.1475 during the early European session on Tuesday.
- ECB’s Lane: ECB Chief Economist Philip Lane said the European economy should continue to grow at a steady but moderate pace, provided the energy shock does not intensify.
- US-Iran: Markets continue to monitor the possibility of US-Iran talks at the United Nations General Assembly this week. Although Washington and Tehran exchanged threats on Sunday, President Donald Trump said he would be open to meeting Iranian President Masoud Pezeshkian, who is expected to attend the UN General Assembly in New York.
- Consumer confidence: The euro area’s flash consumer confidence indicator for September will be released on Tuesday. Confidence had rebounded during the summer, but the recent increase in energy costs could weigh on household sentiment and limit further improvement.
- Fed Speakers: Several Federal Reserve policymakers are scheduled to speak later on Tuesday, including John Williams, Philip Jefferson and Thomas Barkin.
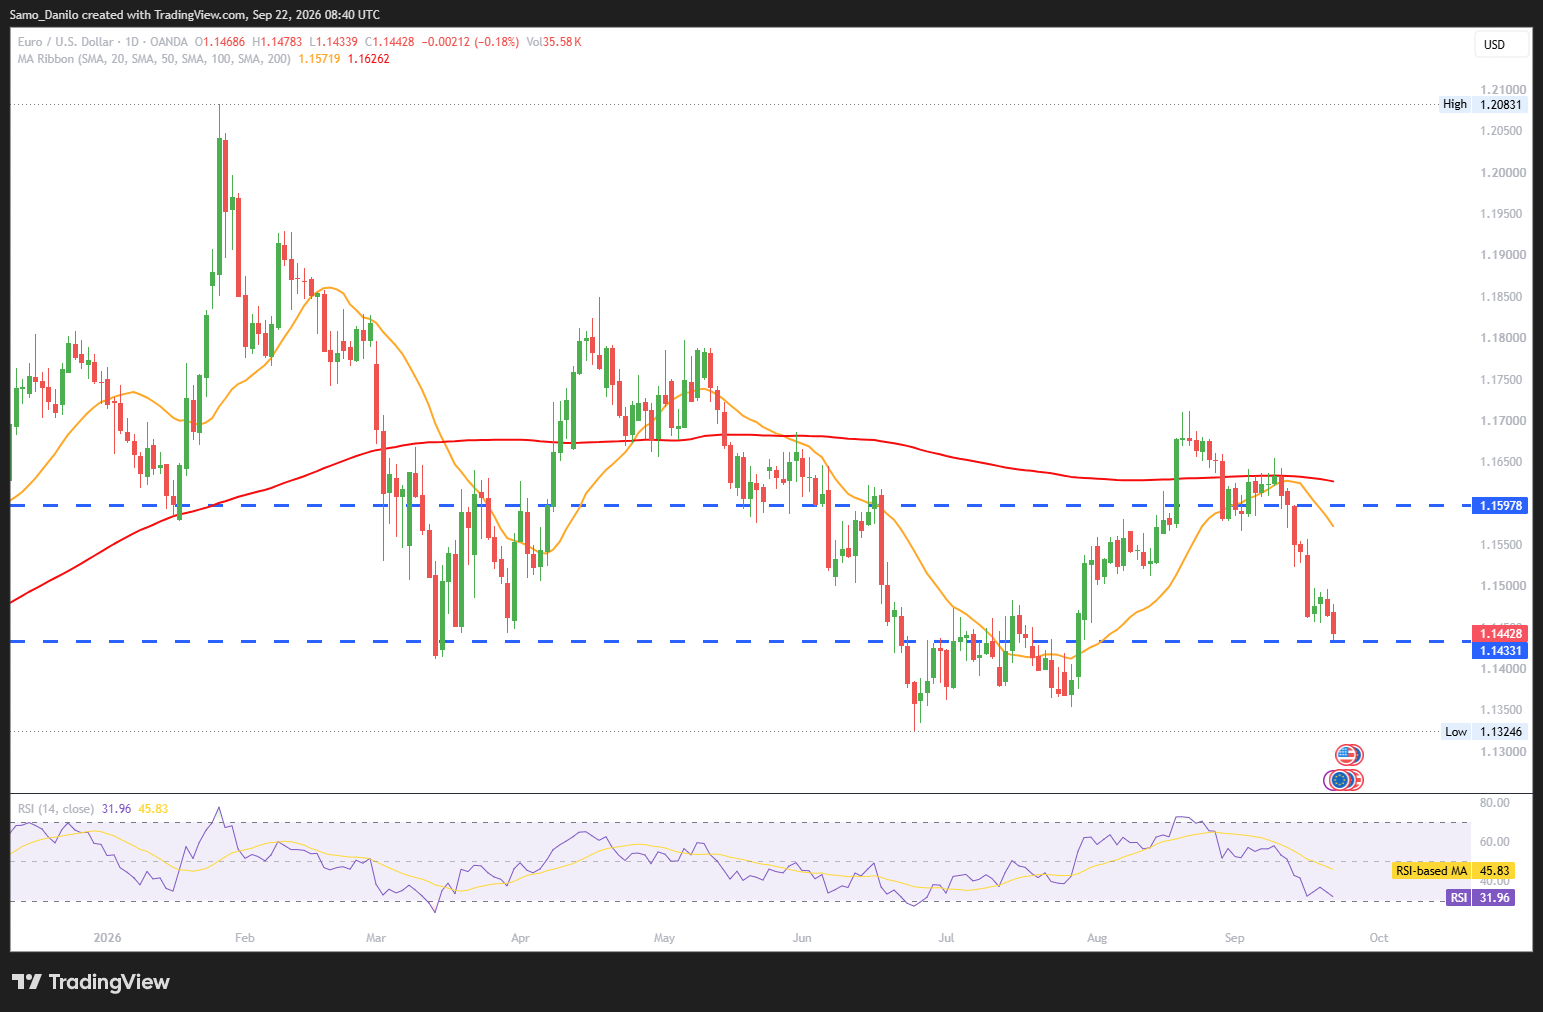
| SMA (20) | Slightly Falling |  |
|
| RSI (14) | Falling | | |
| MACD (12, 26, 9) | Falling | | |
Closing statement: EUR/USD remains supported around 1.1475, while moderate European growth expectations provide some backing for the Euro. However, developments around US-Iran talks, rising energy costs and upcoming Fed commentary could generate volatility and determine the pair’s next short-term move.
GBPUSD
- GBP/USD Price: The GBP/USD pair consolidates above the mid-1.3300s during Tuesday’s European session. The pair remains close to last week’s low, which was its lowest level since July 30, keeping the broader downside pressure in focus.
- Greenland agreement: Attention turns to New York, where the US, Denmark and Greenland are scheduled to sign a new security agreement at 16:30 CEST on the sidelines of the UN General Assembly. Denmark says the agreement will place Arctic security under NATO’s watch, adding another geopolitical development for markets to monitor.
- Fed’s Musalem: Federal Reserve policymaker Alberto Musalem said that, after stripping out supply-related factors, inflation remains too high at up to 3%.
- BoE’s Breeden: Bank of England Deputy Governor Sarah Breeden highlighted difficulties for humans overseeing increasingly autonomous AI systems in real time.
- Government borrowing: The UK government borrowed £18.3 billion in August, almost 20% more than during the same month last year and above market expectations. Persistently higher inflation has contributed to increased government spending, adding to fiscal pressures.
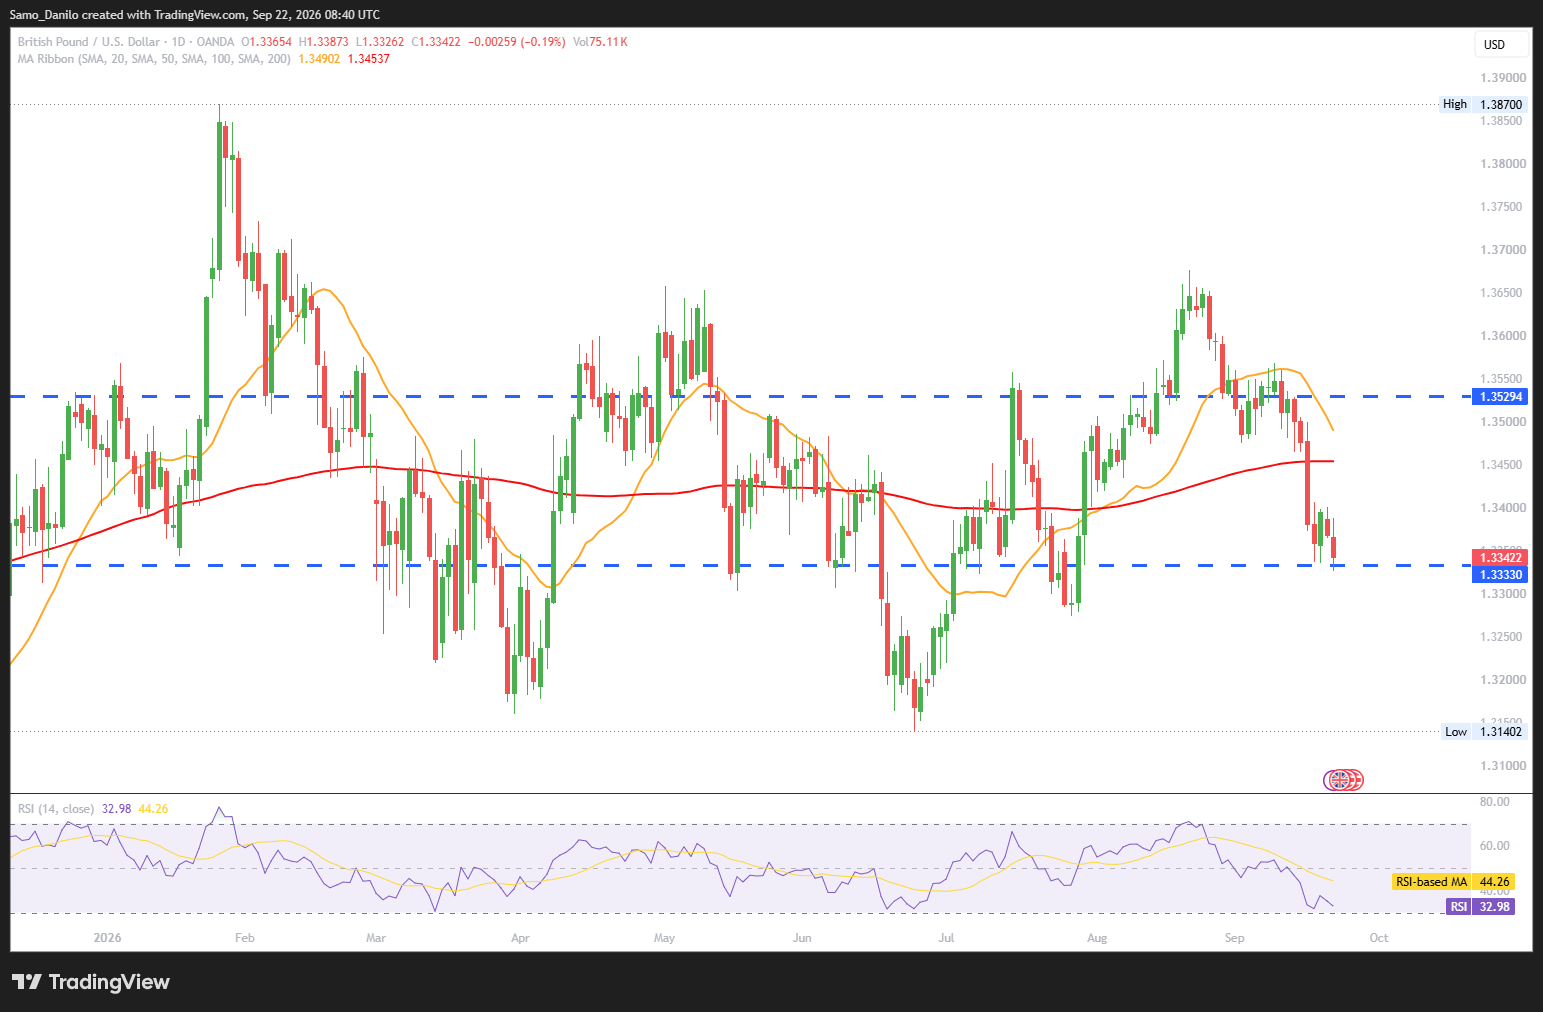
| SMA (20) | Falling | | |
| RSI (14) | Falling | | |
| MACD (12, 26, 9) | Falling | | |
Closing statement: GBP/USD remains under pressure near the mid-1.3300s and close to last week’s multi-week low. Elevated US inflation concerns and higher UK government borrowing create a mixed backdrop, while US and UK policy commentary and geopolitical developments could drive the pair’s next move.
XAUUSD
- XAU/USD Price: Gold (XAU/USD) attracts fresh selling for a second consecutive day, with bears pushing the precious metal further below the $4,300 level during Tuesday’s European session.
- US-China: The PBOC continues to strengthen the Yuan amid positive signals from US and Chinese trade officials. The US has reportedly proposed extending the current trade truce by six months, while China is seeking a longer extension, while Treasury Secretary Bessent is expected to meet with a Chinese delegation in November.
- Fed’s Goolsbee: Federal Reserve policymaker Austan Goolsbee said strong demand may be contributing to elevated US inflation and stressed that there is “no ambiguity” about how the Fed would respond.
- Rate hike: The Federal Reserve’s updated Summary of Economic Projections indicates that officials expect at least one more rate hike this year.
- Iran's warning: Iran’s Islamic Revolutionary Guard Corps warned on Monday that any new military attack would trigger a response involving a different geographical area and different weapons.
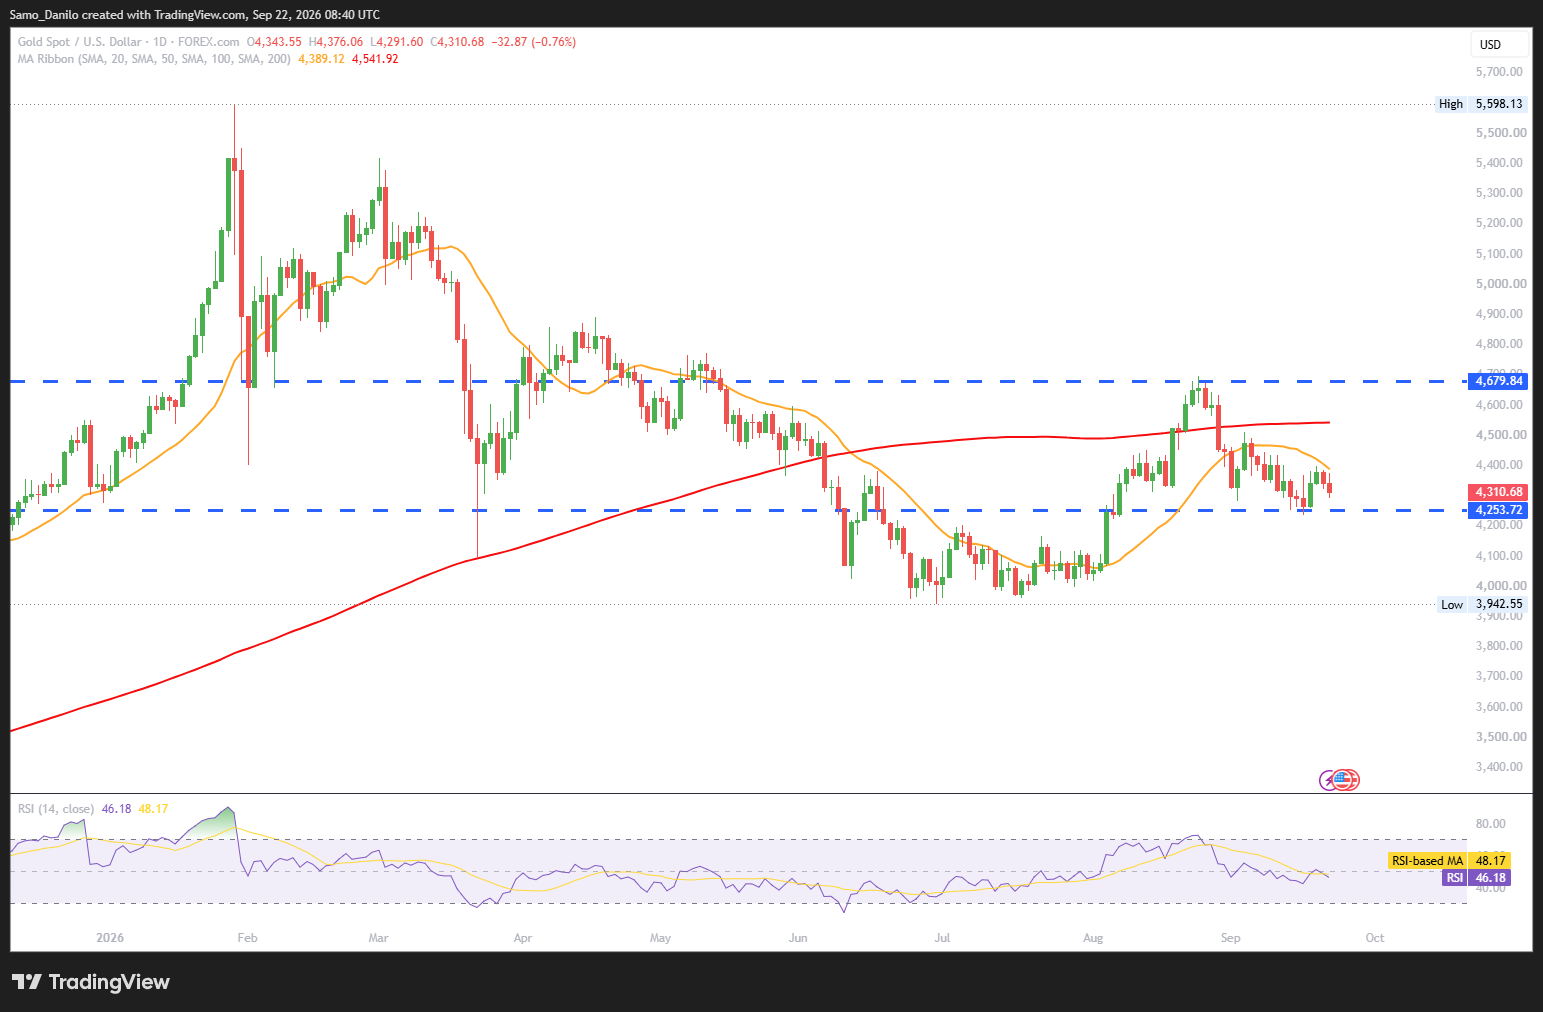
| SMA (20) | Slightly Rising |  |
| RSI (14) | Slightly Rising | |
| MACD (12, 26, 9) | Slightly Falling | |
Closing statement: XAU/USD remains under pressure below $4,300 as stronger US rate expectations and a potentially prolonged period of restrictive monetary policy support the Dollar. Improving US-China trade signals weigh on safe-haven demand, while renewed tensions involving Iran remain a potential source of volatility for gold.
CRUDE OIL
- Crude Oil Price: West Texas Intermediate (WTI) turns higher during Tuesday’s European session, climbing toward the $96.30 region.
- Oil flows: Saudi oil shipments through the Strait of Hormuz have risen to around 2.9 million barrels per day in recent days, up sharply from approximately 700,000 barrels per day in August. However, risks surrounding Red Sea shipping routes and continued Houthi activity remain a source of uncertainty for global energy markets.
- Fuel prices: US diesel prices reached another record last week, exceeding $6.50 per gallon, while fuel prices in Europe continue to surge amid growing supply concerns. Limited global refining capacity is making it difficult to compensate for the loss of Middle Eastern and Russian barrels, with no immediate solution available.
- Russian diesel: Russia announced last week that it would extend its diesel export ban until the end of October as Ukrainian drone attacks on Russian refineries continued.
- India's imports: India’s purchases of discounted Russian crude have come under increased scrutiny following the passage of a new US sanctions bill targeting Russia’s energy sector.
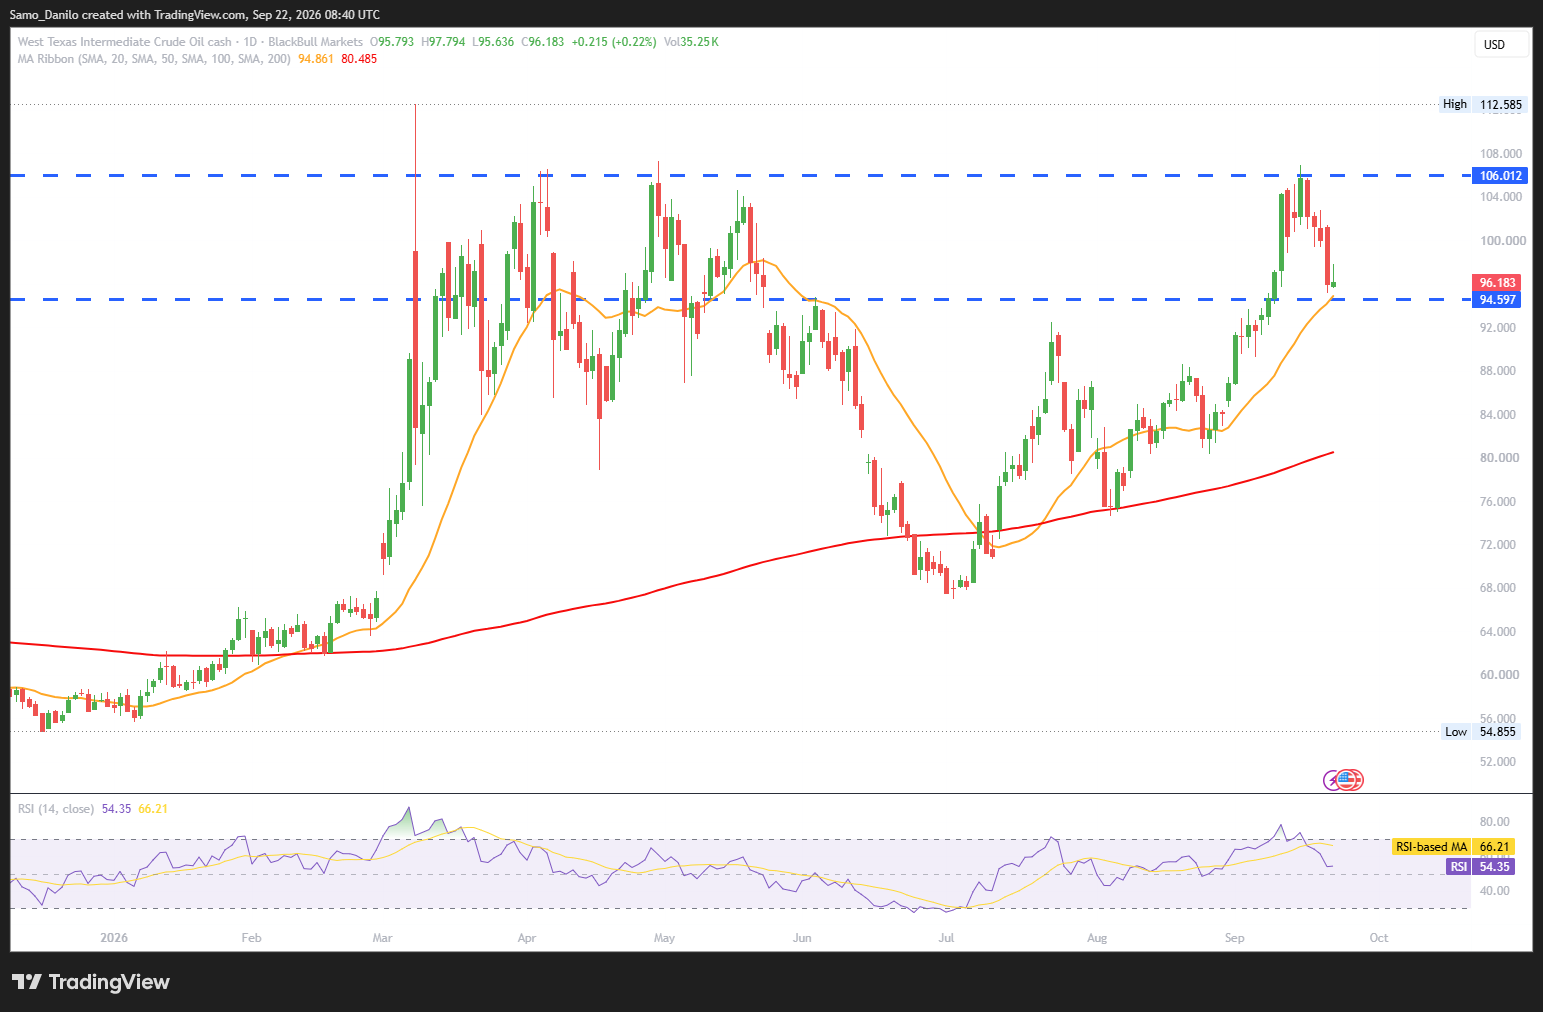
| SMA (20) | Rising | | |
| RSI (14) | Falling | | |
| MACD (12, 26, 9) | Rising | | |
Closing statement: WTI rebounds toward $96.30 as persistent refining constraints, Russian diesel restrictions and geopolitical risks continue to support the energy market. However, the sharp recovery in Saudi shipments through the Strait of Hormuz could ease some immediate supply concerns and limit further upside pressure.
DAX
- DAX 40 Price: The DAX 40 trades back below the 25,500-point level during Tuesday’s European morning session.
- Political uncertainty: The far-right Alternative for Germany (AfD) finished first in state elections in northeastern Germany on Sunday, while Chancellor Friedrich Merz’s conservative party suffered a significant regional setback.
- Relief measures: Euro-area governments are again considering fiscal measures to cushion the impact of higher energy costs. Germany agreed to a €2.5 billion relief package, including a temporary fuel-tax cut, while Italy plans to abolish its vehicle ownership tax at an estimated cost of around €2 billion, although funding for the measure remains unclear.
- Bundesbank report: The German Bundesbank’s latest monthly report projects slight economic growth in the third quarter, followed by a recovery in the fourth quarter.
- Property funds: Deutsche Bank’s asset-management unit DWS is reportedly considering emergency measures to address liquidity risks at three German property funds.
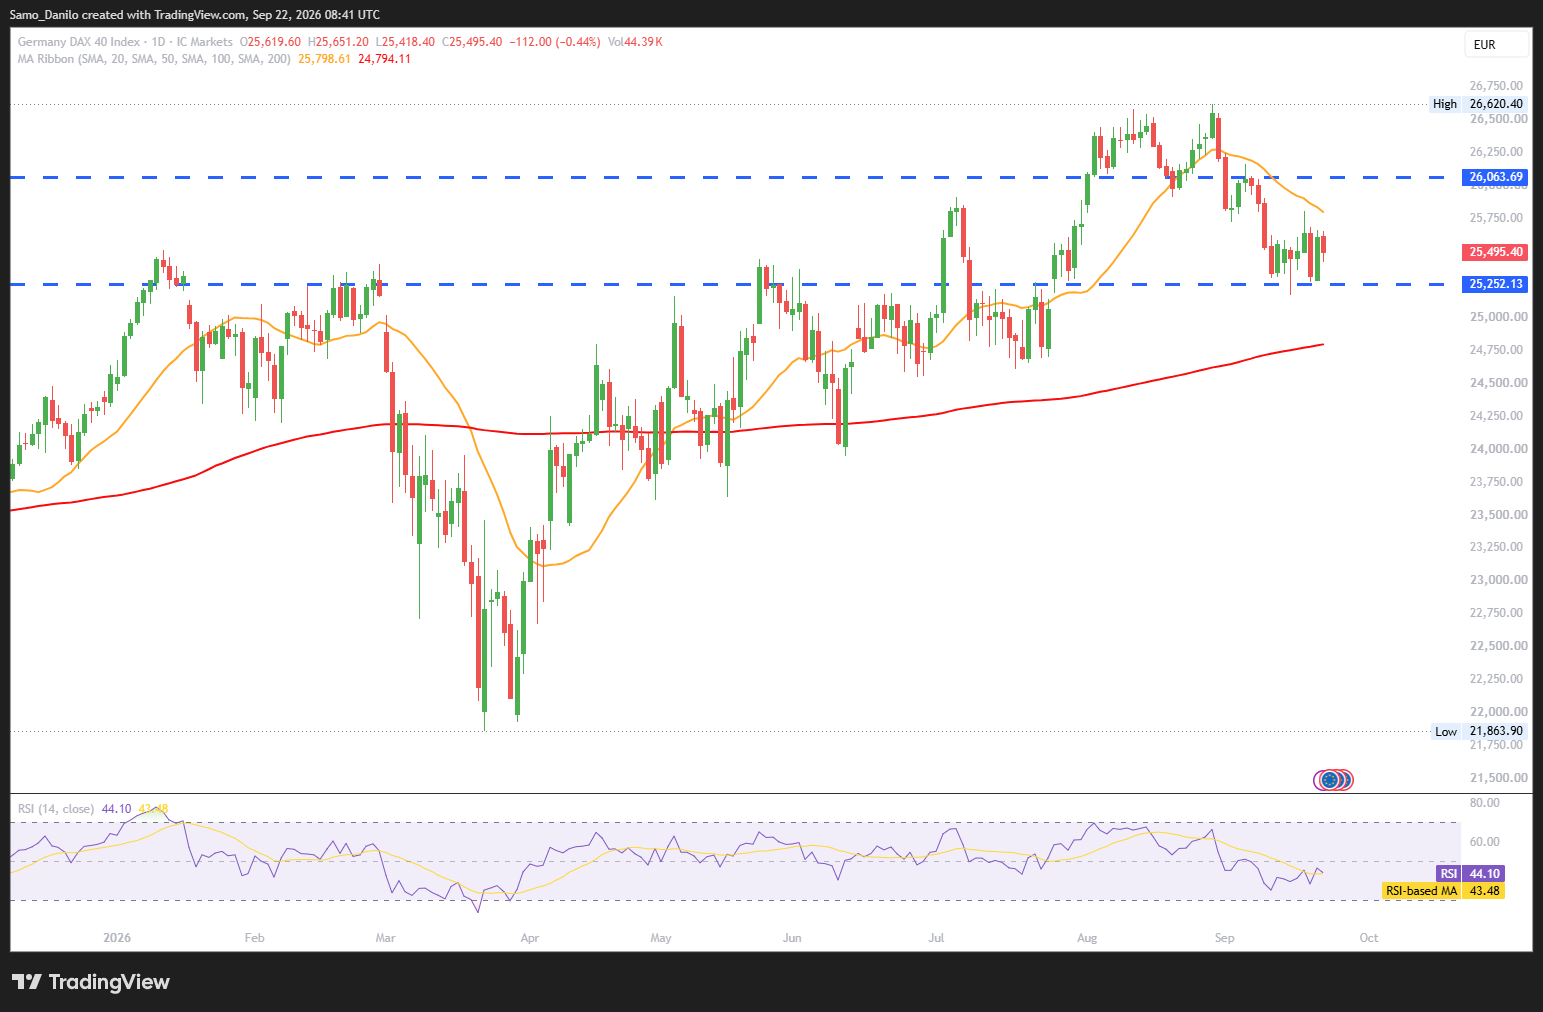
| SMA (20) | Slightly Falling | |
| RSI (14) | Slightly Rising | |
| MACD (12, 26, 9) | Slightly Falling | |
Closing statement: The DAX 40 remains below 25,500 as German political uncertainty and property-market concerns weigh on sentiment. At the same time, expectations for a gradual economic recovery and government measures to ease energy costs could provide some support, leaving the index sensitive to both domestic developments and broader euro-area conditions.