EURUSD
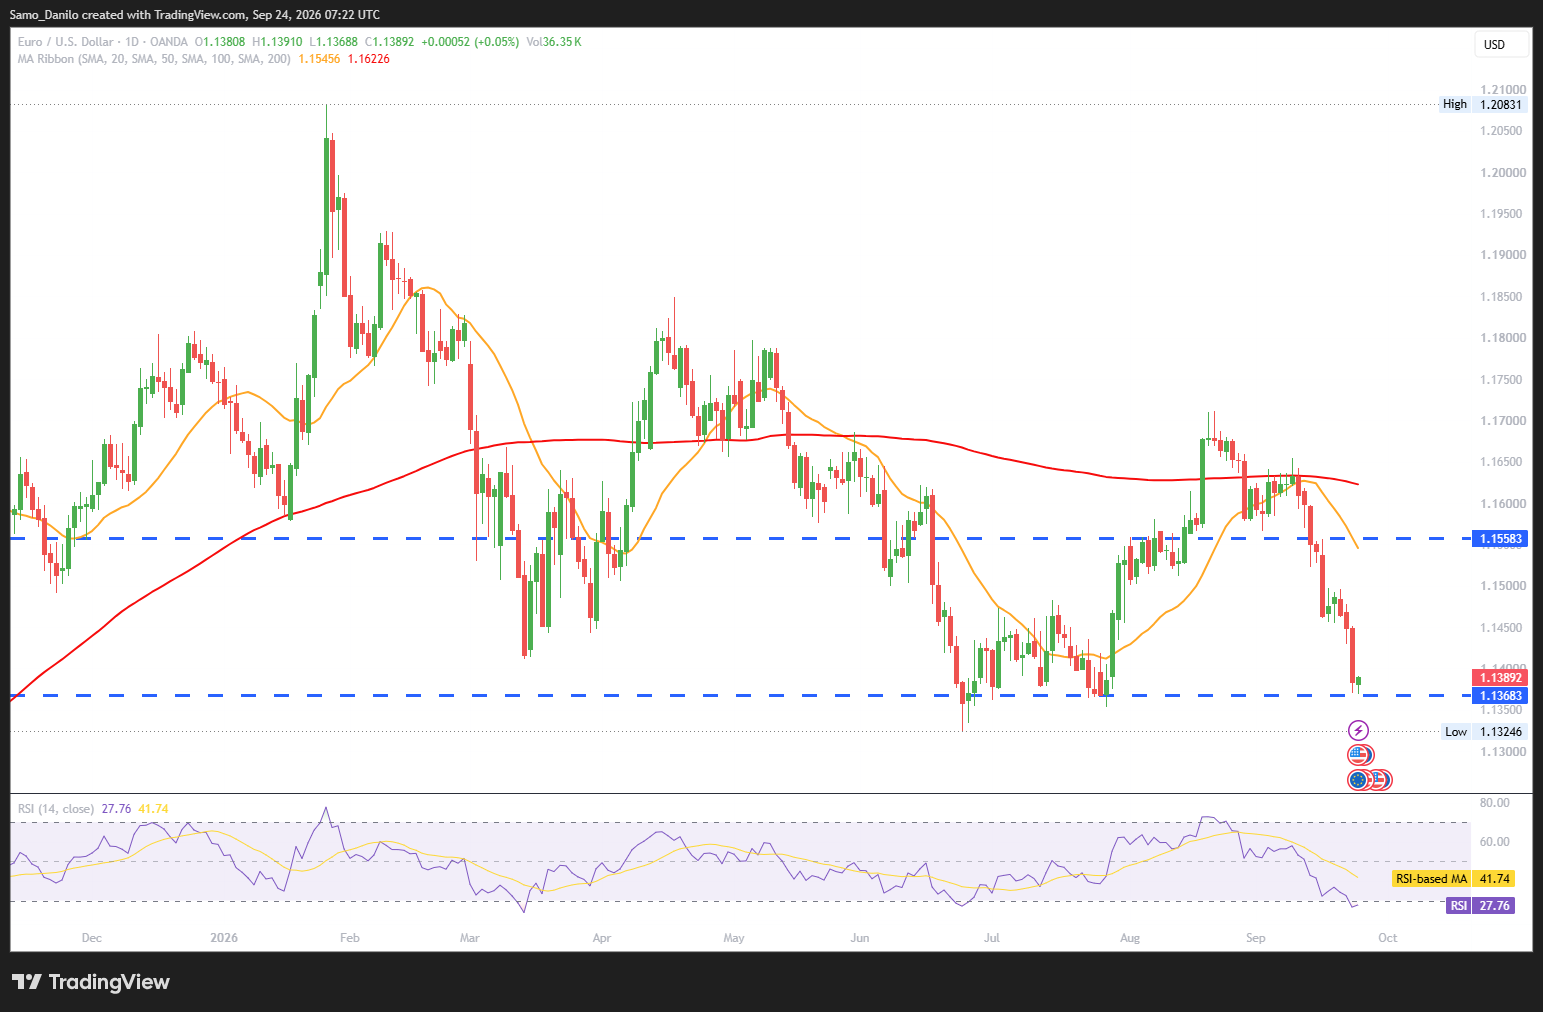
- EUR/USD Price: The EUR/USD pair extends its decline for a third consecutive day, reaching a fresh low since July 28 during the Asian session on Thursday.
- Eurozone PMI: The eurozone composite PMI rose to 53.1 in September, significantly above expectations of 51.7 and August’s 52.0, reaching its highest level in more than three years. Services led the improvement at 53.0, while manufacturing remained stable at 52.7, pointing to continued resilience across the region’s private sector.
- Rate hike: The stronger-than-expected flash PMI data have put a potential October ECB rate hike back on the table. Bundesbank President Joachim Nagel has also not pushed back against the possibility, reinforcing expectations that stronger economic momentum could influence the ECB’s policy outlook.
- Nordic CBs: Norges Bank is expected to leave its policy rate unchanged at 4.25%, while potentially signalling that further hikes could be required. Meanwhile, Sweden’s Riksbank is expected to keep rates at 1.75% but adopt a more hawkish stance compared with its June monetary-policy report.
- SNB rate: The Swiss National Bank is expected to maintain its policy rate at 0%, in line with market expectations and current pricing. No rate hike is anticipated over the coming year, as the recent increase in energy prices is not expected to generate broad-based inflationary pressure.
| SMA (20) | Falling |  | |
| RSI (14) | Falling | | |
| MACD (12, 26, 9) | Falling | | |
Closing statement: EUR/USD remains under pressure near 1.1380 after three consecutive sessions of declines, although the absence of stronger follow-through selling leaves room for consolidation. Strong eurozone PMI data and renewed expectations for an October ECB hike could provide support to the Euro, potentially limiting further downside if the market continues to reassess the ECB’s policy outlook.
GBPUSD
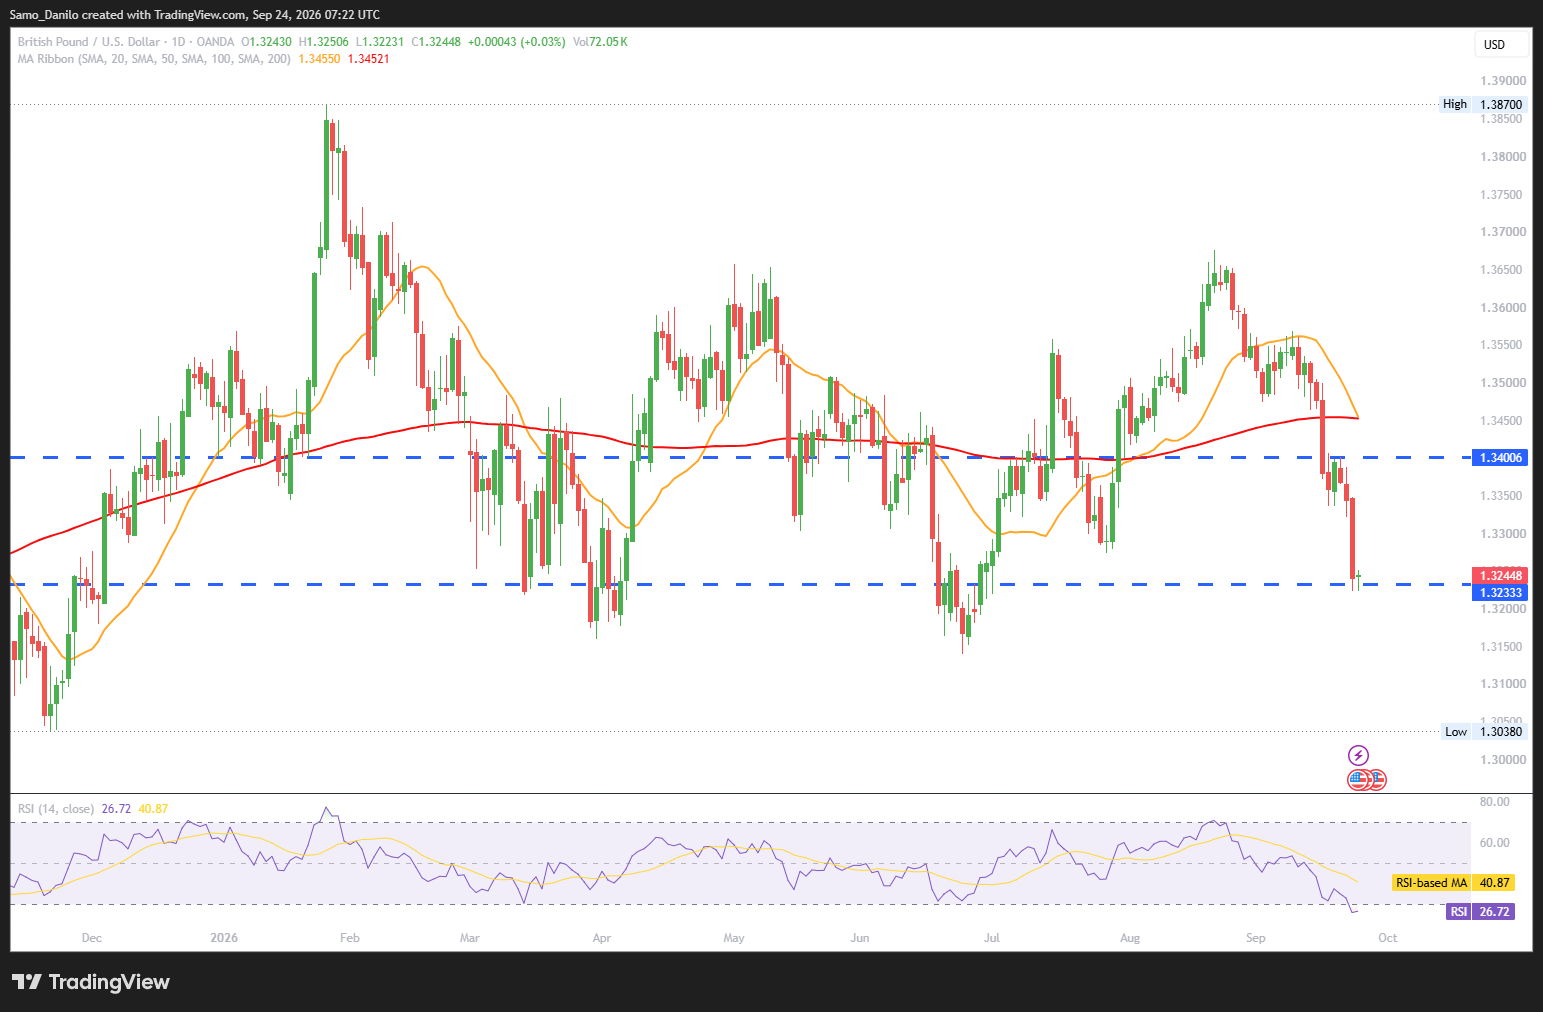
- GBP/USD Price: The GBP/USD pair posts modest gains around 1.3240 during the early European trading session on Thursday.
- UK PMI: The UK composite PMI weakened in September, with the services component falling to 51.7 from 52.5 and signalling slower expansion in the dominant part of the economy. Manufacturing, however, improved slightly from 51.7 to 52.0, providing a partial offset to the weaker services reading.
- OECD outlook: The OECD said on Wednesday that the Bank of England does not need to raise interest rates, arguing that current monetary policy is sufficiently restrictive to keep inflation under control. The assessment contrasts with expectations for further tightening and adds to the uncertainty surrounding the BoE’s future policy path.
- BofA outlook: Bank of America Global Research expects the Bank of England to raise interest rates twice over the next six months. Higher energy prices are seen as increasing the risk that inflation remains persistent, potentially creating additional pressure on the BoE to tighten monetary policy.
- Fed officials: Federal Reserve policymakers John Williams, Beth Hammack and Christopher Paulson are scheduled to speak, with all three serving as voters this year. Hammack has been among the strongest advocates for earlier rate increases and already supported a hike in July, making her comments particularly relevant for expectations around US monetary policy.
| SMA (20) | Falling | | |
| RSI (14) | Falling | | |
| MACD (12, 26, 9) | Falling | | |
Closing statement: GBP/USD remains modestly supported near 1.3240, although weaker UK services activity highlights some loss of economic momentum. Diverging expectations for BoE policy and upcoming comments from voting Fed officials could drive volatility, with the Pound sensitive to changes in both UK inflation expectations and the US rate outlook.
XAUUSD
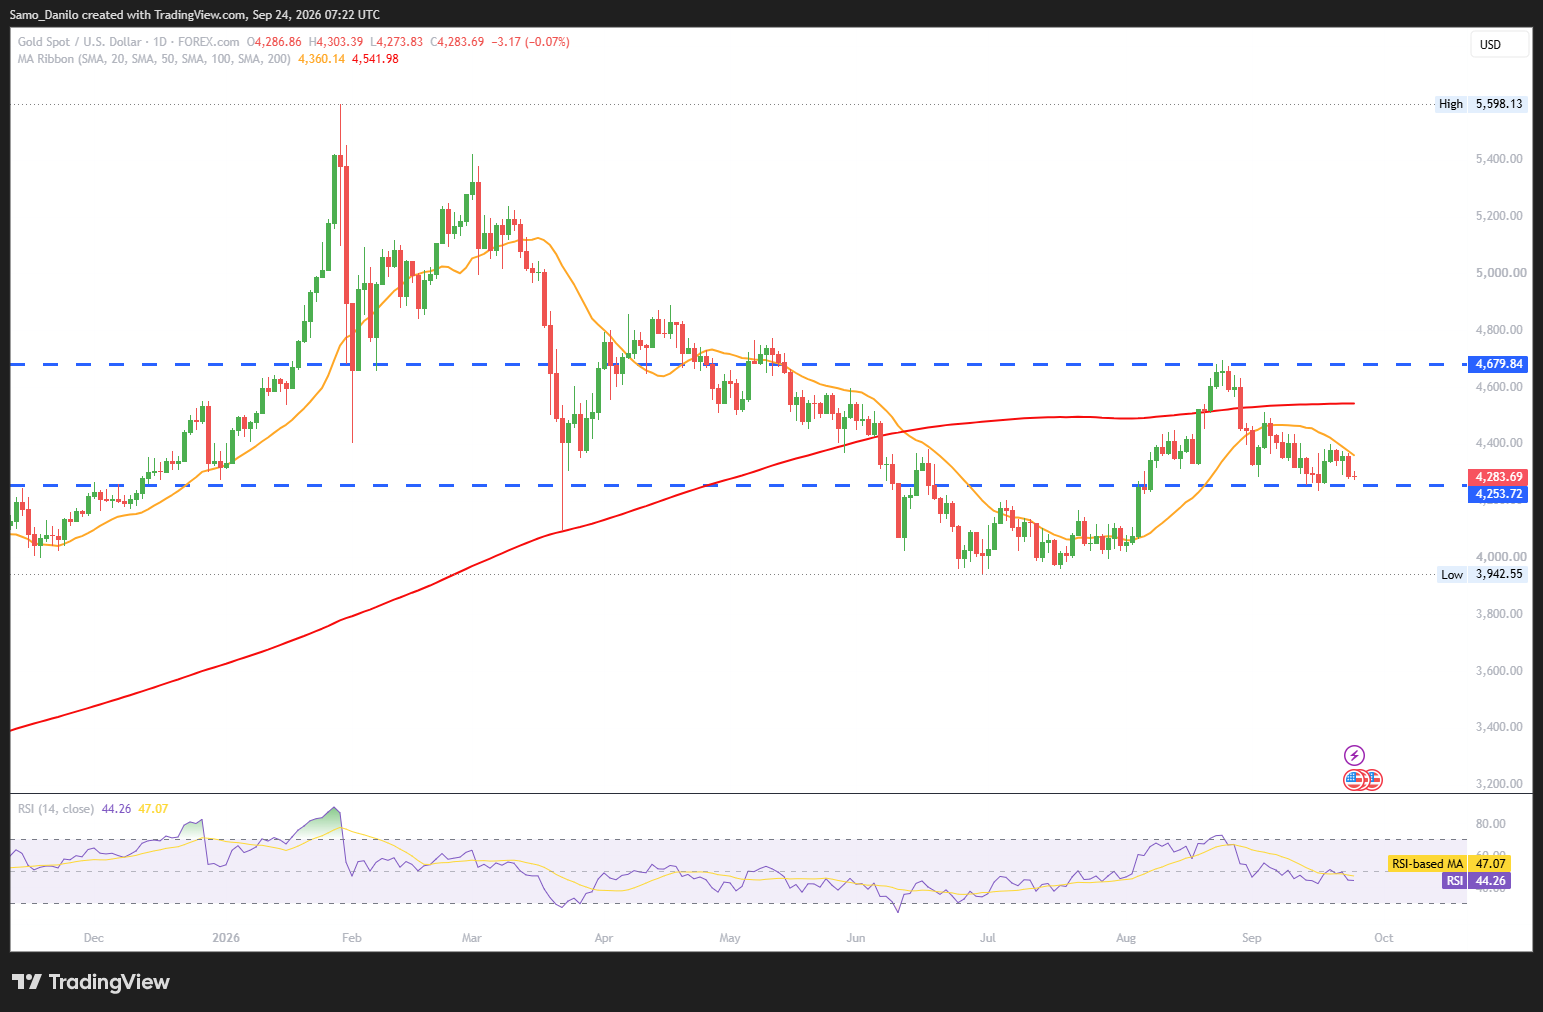
- XAU/USD Price: Gold (XAU/USD) remains under pressure below the $4,300 level, trading near a one-week low reached earlier on Thursday.
- Trump-Xi Summit: Chinese President Xi Jinping is meeting US President Donald Trump in Washington for their second summit of the year. An extension of the existing trade truce and discussions on AI governance are expected to feature prominently, with the outcome potentially influencing broader market sentiment and demand for safe-haven assets.
- US-Iran: Tensions between the US and Iran remained a major focus at the United Nations General Assembly after President Trump said Iran faces a choice between diplomacy and total destruction.
- US PMI: US flash PMI data came in well above expectations, with the composite index rising to 58.4 in September from 56.0 in August. Manufacturing increased to 57.0 from 53.9, while services climbed to 58.7 from 56.5, with stronger new orders, output and employment pointing to resilient US economic activity.
- Fed's Barr: Federal Reserve policymaker Barr said further rate increases are likely needed to ensure inflation returns to the 2% target in a timely manner. He also noted that risks to the inflation target have increased while labour-market risks have eased, adopting a firmer tone that could reinforce expectations for tighter US monetary policy.
| SMA (20) | Slightly Rising |  |
| RSI (14) | Slightly Falling | |
| MACD (12, 26, 9) | Slightly Falling | |
Closing statement: XAU/USD remains depressed below $4,300 as strong US economic data and increasingly hawkish Fed commentary weigh on the non-yielding asset. However, elevated US-Iran tensions and the Trump-Xi summit could continue to generate safe-haven demand, leaving geopolitical developments as an important source of volatility.
CRUDE OIL
- Crude Oil Price: West Texas Intermediate (WTI), the US crude oil benchmark, trades around $96.40 during the early European session on Thursday.
- Strait of Hormuz: Iran’s President told the United Nations that the Strait of Hormuz cannot remain freely accessible while sanctions remain in place, while US Secretary of State Rubio said Iran had fired at commercial ships.
- US Crude Inventories: US crude inventories increased by 2.969 million barrels in the week ending September 18, according to the EIA, reversing the previous week’s 640,000-barrel decline.
- Kenya refinery: Kenya is set to break ground on September 30 on the Dangote-backed East Africa Oil Refinery in Lamu. The project is estimated at $17 billion by Kenyan officials and $20 billion by Aliko Dangote and is designed to process up to 700,000 barrels of crude oil per day at Lamu’s deep-water port.
- Oil flows: Middle Eastern oil exporters are increasingly relying on pipelines and ship-to-ship transfers to bypass the heavily constrained Strait of Hormuz. Saudi Arabia’s East-West pipeline restart has eased some market concerns, although regional exports remain well below pre-war levels and sharply higher shipping costs continue to disrupt global flows.
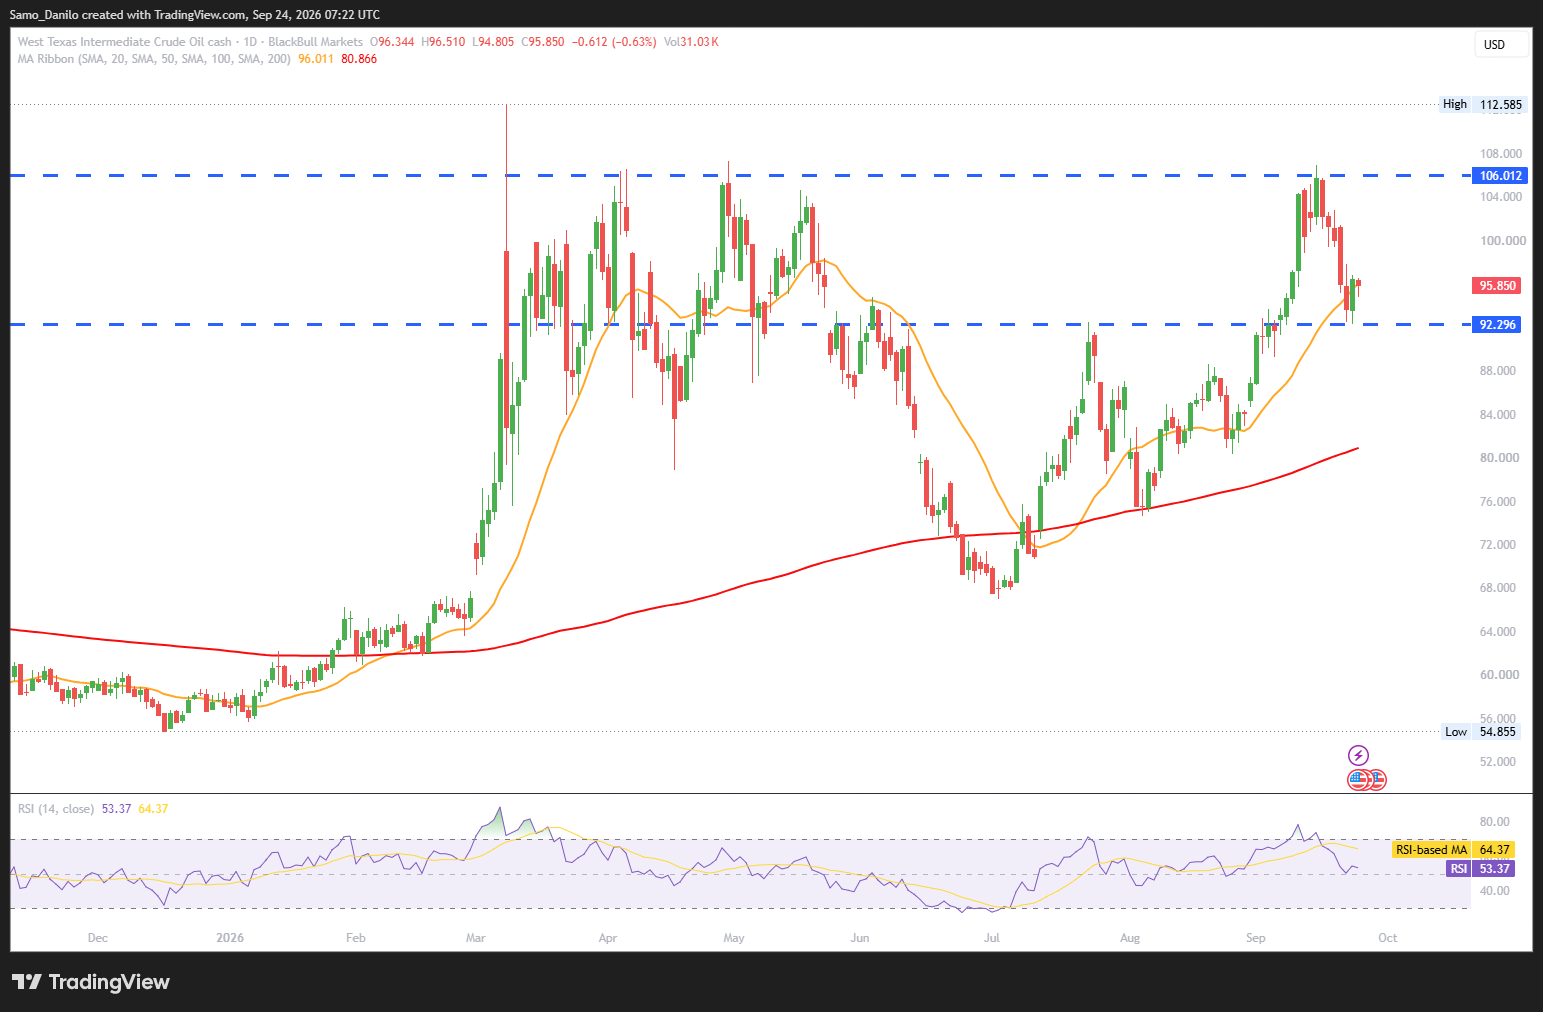
| SMA (20) | Rising | | |
| RSI (14) | Slightly Rising | |
|
| MACD (12, 26, 9) | Slightly Rising | |
Closing statement: WTI remains around $96.40 as restrictions around the Strait of Hormuz and disrupted regional exports continue to support crude prices. However, the unexpected increase in US inventories and the gradual development of alternative export routes could limit further upside, leaving the market highly sensitive to geopolitical and supply-flow developments.
DAX
- DAX 40 Price: The DAX 40 trades below the 25,400-point level during the early European session on Tuesday.
- German PMI: Germany’s September composite PMI jumped to 53.8 from 51.8, marking its strongest reading since last October and coming two points above consensus. Services returned to expansion at 52.9 after five months below 50, while manufacturing remained strong at 53.8 and employment increased for a second consecutive month.
- Mercedes-Benz: Mercedes-Benz plans to cut around €800 million ($910.64 million) in labour costs in Germany, according to WirtschaftsWoche, citing three people familiar with the matter. The reported cost-saving plan highlights continued efforts by German manufacturers to improve efficiency and manage rising operating pressures.
- MTU shares: MTU shares received a clear boost after Citigroup reversed its previous rating on the German aircraft-engine maker. Citi sees potential for a marked improvement in cash flow through 2030, which could reduce the impact of MTU’s previous cash-conversion weakness and uncertainties surrounding its GTF engine.
- Business climate: Germany’s Ifo business climate indicator for September is due later on Tuesday. The current-assessment component is expected to improve significantly following the stronger-than-expected PMI data, while expectations may remain unchanged as higher energy costs continue to weigh on the outlook.
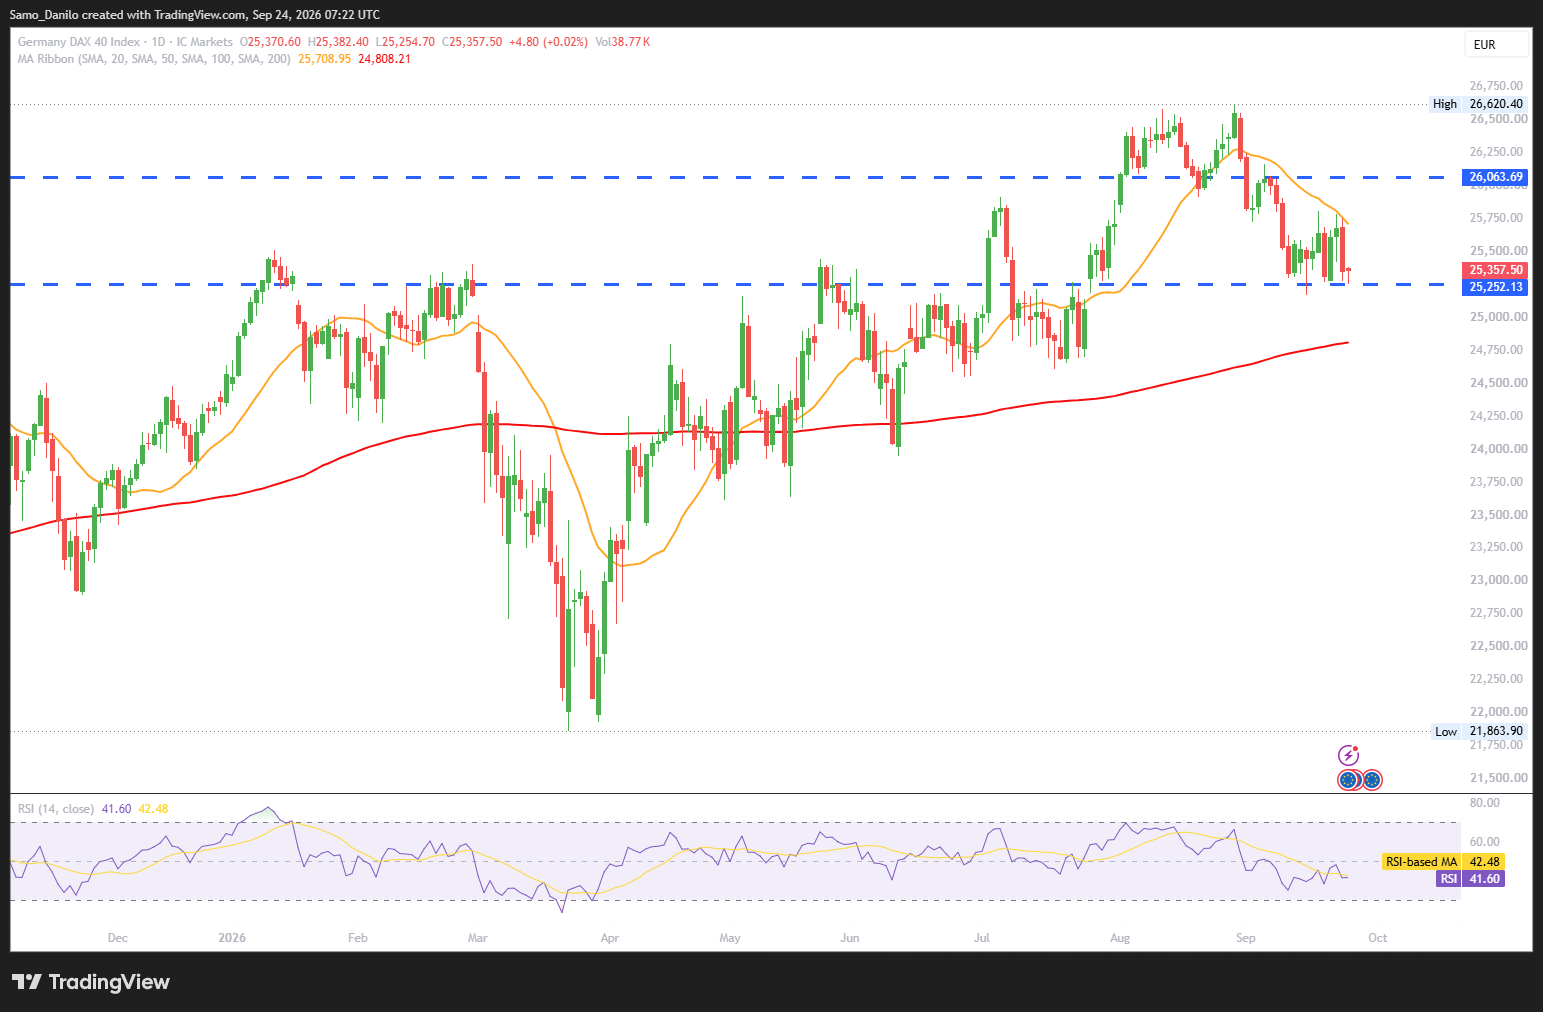
| SMA (20) | Slightly Falling | |
| RSI (14) | Slightly Falling | |
| MACD (12, 26, 9) | Slightly Falling | |
Closing statement: The DAX 40 remains below 25,400 despite stronger-than-expected German PMI data, with investors awaiting the Ifo business climate indicator for further clues about the economic outlook. At the same time, corporate developments at Mercedes-Benz and MTU are likely to keep the German industrial sector in focus, potentially influencing broader sentiment around the index.