EURUSD
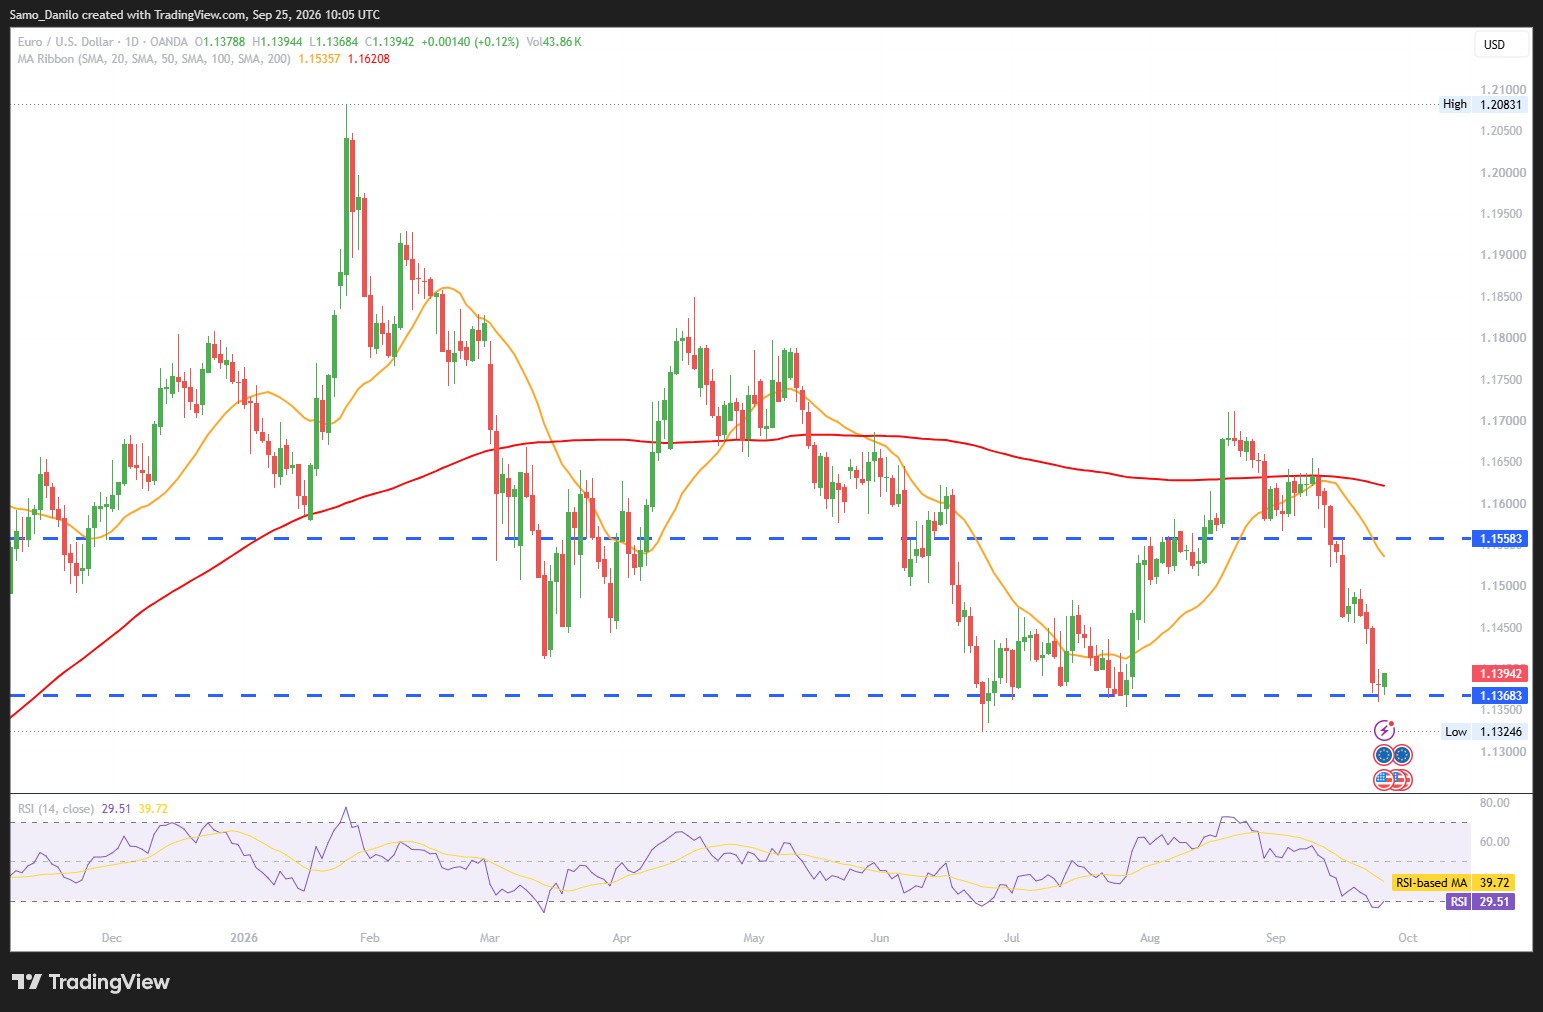
- EUR/USD Price: The EUR/USD pair trades marginally higher around 1.1385 during early European trading on Friday. However, the pair remains within Thursday’s trading range.
- Fed's Barr: Federal Reserve Governor Michael Barr said that “further policy adjustments are likely to be needed” to ensure inflation returns to target in a timely manner. His comments reinforce expectations that the Fed could maintain a restrictive stance and potentially tighten policy further if inflationary pressures persist.
- Nordic CBs: Sweden’s Riksbank kept its policy rate unchanged at 1.75% but revised its rate path higher, now including a hike before year-end. Meanwhile, Norges Bank raised its rate by 25 basis points to 4.50% in a slightly dovish move, while signalling that another hike remains possible if required.
- SNB rate: The Swiss National Bank maintained its policy rate at 0%, in line with expectations, while raising its inflation forecasts for 2026 and the first half of 2027. However, the longer-term forecast was largely unchanged, supporting expectations that the SNB will not raise rates over the coming year.
- Data ahead: Preliminary US durable goods orders for August are due later on Friday, with core capital goods orders particularly important for assessing investment activity. The data could indicate whether the recent strength seen in manufacturing surveys is translating into stronger underlying economic activity.
| SMA (20) | Falling |  | |
| RSI (14) | Falling | | |
| MACD (12, 26, 9) | Falling | | |
Closing statement: EUR/USD remains broadly range-bound near 1.1385, while a more hawkish tone from the Federal Reserve could provide support to the US Dollar. The upcoming US durable goods data will be important for assessing the strength of investment activity and could determine whether the pair breaks out of its current range.
GBPUSD
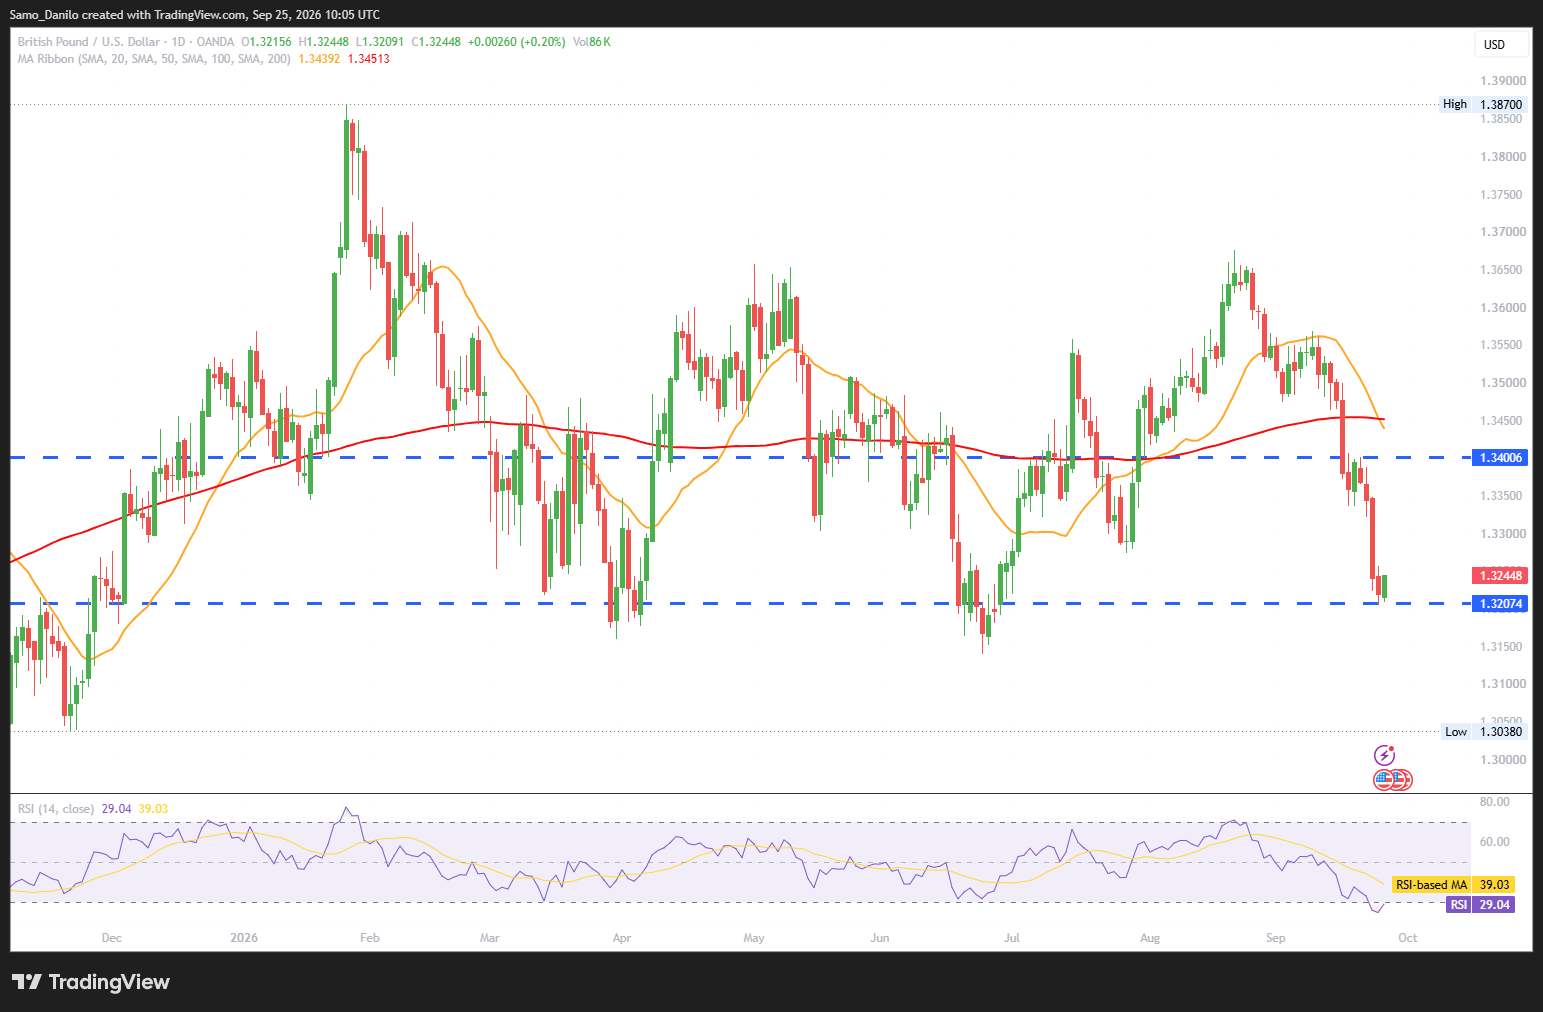
- GBP/USD Price: The GBP/USD pair trades in negative territory around 1.3210 during the early European session on Friday.
- Public borrowing: UK public sector borrowing reached £18.27 billion in August, significantly above the market forecast of £15.35 billion and the £2.04 billion recorded in July. The larger-than-expected borrowing figure highlights continued pressure on the UK’s public finances and could weigh on sentiment toward the Pound.
- UK tariffs: The European Union is urging the UK to raise tariffs on Chinese cars to reduce the risk of vehicles being redirected to the British market because of existing trade barriers in Europe.
- Jobless claims: US continuing jobless claims stood at 1.719 million in the week to September 12, below the 1.745 million market consensus and close to the revised previous reading of 1.717 million.
- Fed’s Paulson: Federal Reserve voter Christopher Paulson said September inflation was a key factor behind the latest rate hike and warned that rates may need to rise again to address persistent price pressures.
| SMA (20) | Falling | | |
| RSI (14) | Falling | | |
| MACD (12, 26, 9) | Falling | | |
Closing statement: GBP/USD remains under pressure near 1.3210 as elevated UK public borrowing weighs on the Pound, while relatively stable US labour-market data and hawkish Fed commentary support the Dollar. Further signals on US inflation and monetary policy are likely to remain important for the pair’s next directional move.
XAUUSD
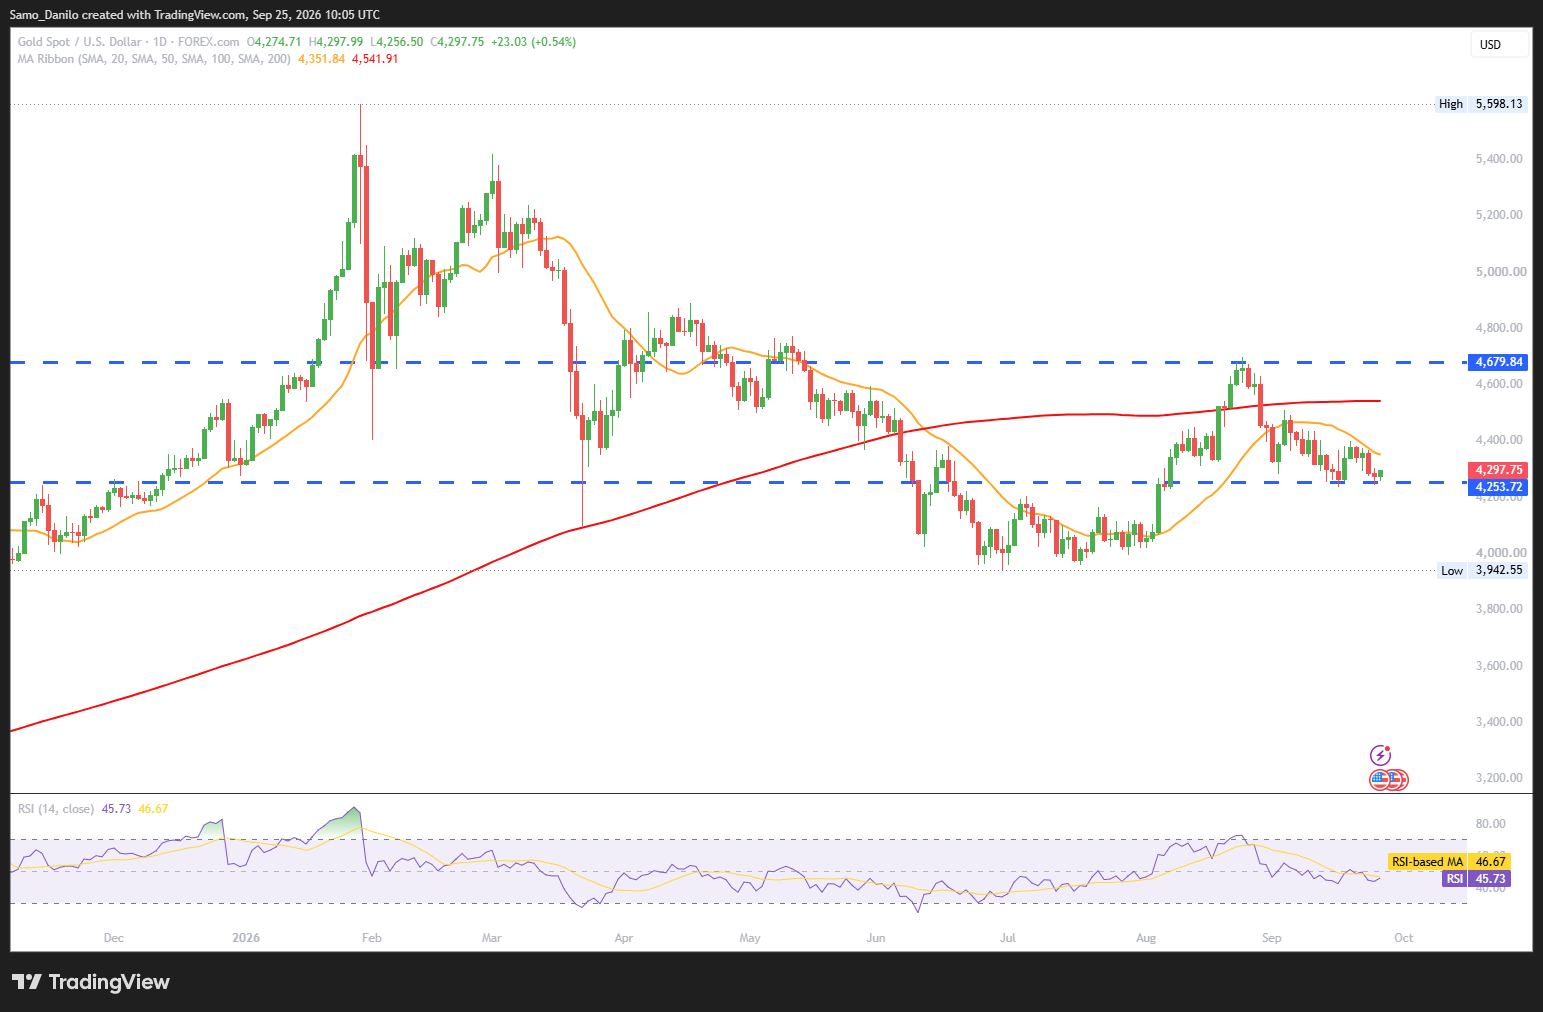
- XAU/USD Price: Gold (XAU/USD) remains confined to a narrow range near its weekly low during the early European session on Friday.
- Trump-Xi discussions: Chinese state media Xinhua reported that President Xi Jinping urged US President Donald Trump to change Washington’s official language on Taiwan from saying it “does not support” independence to saying it “opposes” independence.
- Yuan policy: Trump has previously expressed concerns about weakness in the Chinese yuan, including in March 2025. Since then, the People’s Bank of China has supported a stronger yuan, although recent signs suggest the central bank may be becoming less comfortable with expectations of continued one-way CNY appreciation.
- Fed's Hammack: Federal Reserve voter Beth Hammack said price stability remains a central responsibility of monetary policymakers and noted that inflation is still elevated amid solid output and demand.
- Fed's Williams: New York Fed President John Williams said on Thursday that another interest-rate hike this year would be a reasonable expectation.
| SMA (20) | Slightly Falling | |
| RSI (14) | Slightly Falling | |
| MACD (12, 26, 9) | Slightly Falling | |
Closing statement: XAU/USD remains under pressure near $4,295 as hawkish Federal Reserve commentary and expectations for another rate hike weigh on the non-yielding asset. At the same time, developments surrounding US-China relations and Taiwan could increase geopolitical uncertainty and provide an offsetting source of safe-haven demand.
CRUDE OIL
- Crude Oil Price: West Texas Intermediate (WTI), the US crude oil benchmark, trades around $96.50 during the early European session on Thursday.
- US-Iran talks: Reports from the New York afternoon indicated that the US and Iran were discussing a phased agreement to reopen the Strait of Hormuz and end the blockade. More recent reporting from the Financial Times suggested that Iran has offered a seven-day ceasefire proposal, potentially reducing some of the immediate supply-disruption risks.
- India oil: India’s Oil Minister Hardeep Singh Puri said there is currently no shortage of crude oil and that the country has no plans to reduce fuel-product exports. The comments suggest that India does not currently see a need for emergency measures to secure additional domestic fuel supplies.
- European security: Denmark warned that Russia could launch a limited attack against a NATO country within months, according to the Financial Times.
- Reserve release: French President Emmanuel Macron said that a coordinated release of strategic oil reserves could potentially be considered. Such a move could increase available crude supplies and help ease some market pressure if governments decide to respond collectively to disruptions.
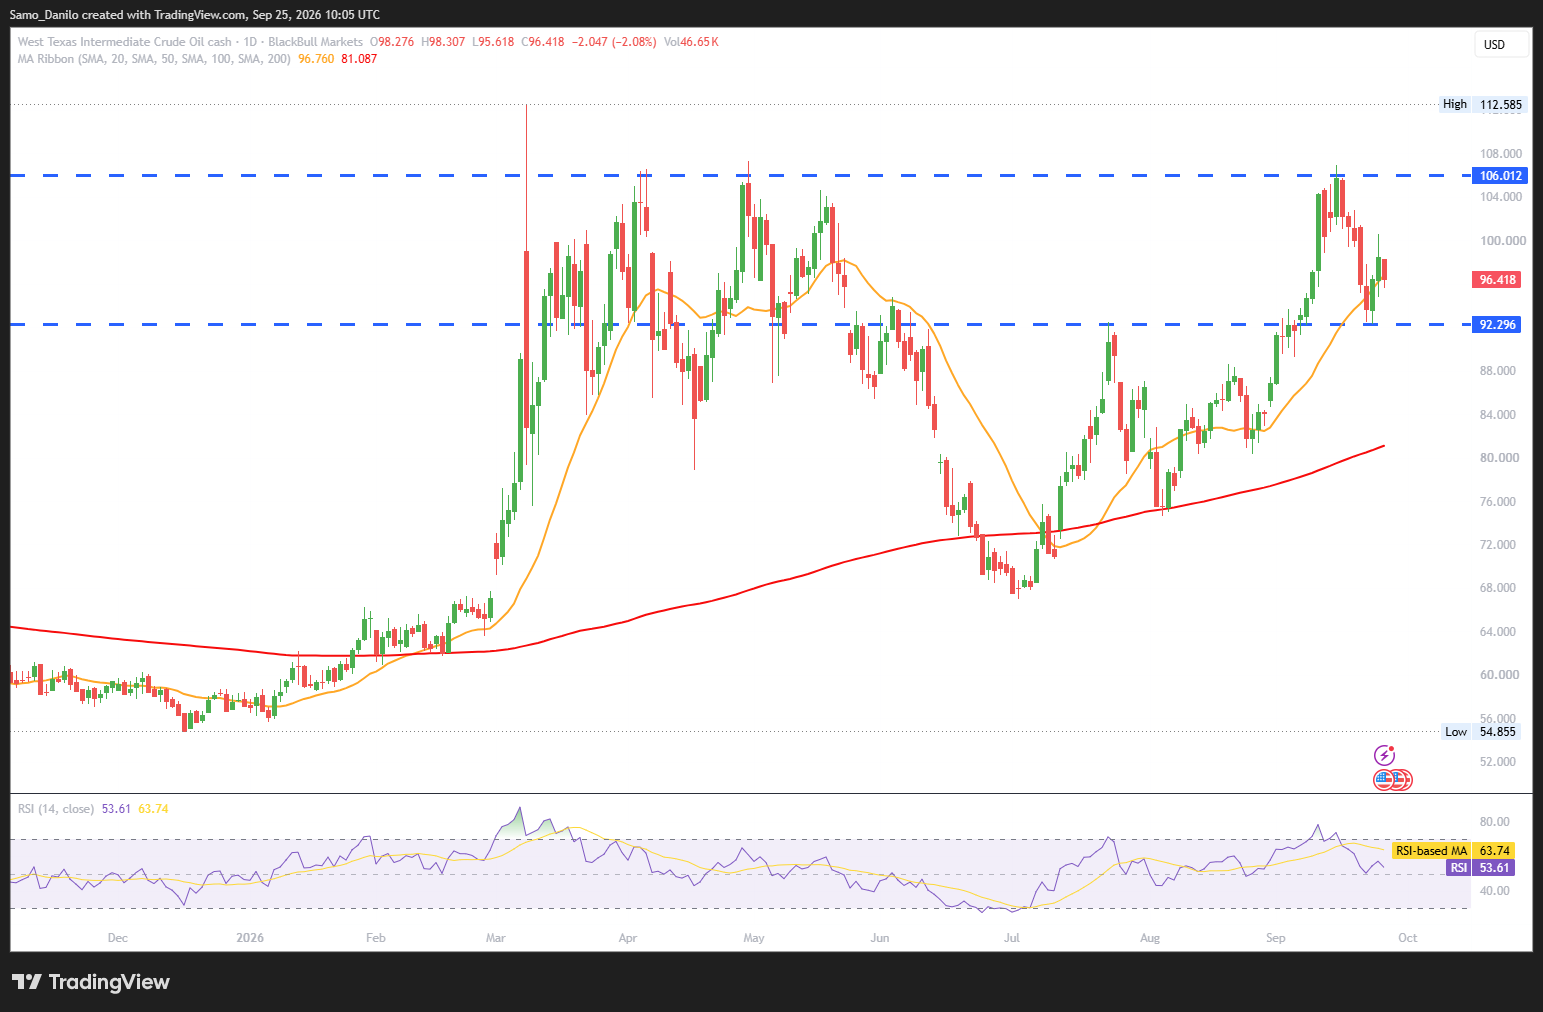
| SMA (20) | Rising |  | |
| RSI (14) | Slightly Rising | |
|
| MACD (12, 26, 9) | Slightly Rising | |
Closing statement: WTI remains elevated near $96.50, but reports of US-Iran negotiations and a potential seven-day ceasefire could reduce some of the immediate risk premium linked to the Strait of Hormuz. At the same time, the possibility of coordinated strategic-reserve releases and assurances from India that crude supplies remain sufficient could limit further upside pressure on oil prices.
DAX
- DAX 40 Price: The DAX 40 trades around the 25,470-point level during the early European session on Tuesday.
- Ifo data: Germany’s Ifo business climate report came in stronger than expected in September, following the solid PMI readings earlier this week. The current assessment rose to 89.5 from 88.5, above the 89.0 consensus, while expectations increased to 90.4 from 89.0 and exceeded the 89.3 forecast despite recently higher energy costs.
- ECB's Radev: ECB policymaker Radev said the latest rate hike does not place the central bank on a predetermined policy path. He highlighted that inflation risks are tilted to the upside, while growth risks remain skewed to the downside, leaving the future policy trajectory dependent on incoming economic data.
- Xi-Trump meetings: The meetings between Chinese President Xi Jinping and US President Donald Trump in Washington have so far produced few concrete results.
- Beiersdorf rating: JPMorgan maintained its “Neutral” rating on Beiersdorf, with analyst Celine Pannuti drawing a cautiously optimistic conclusion from the US bank’s Global Beauty Conference on Friday.
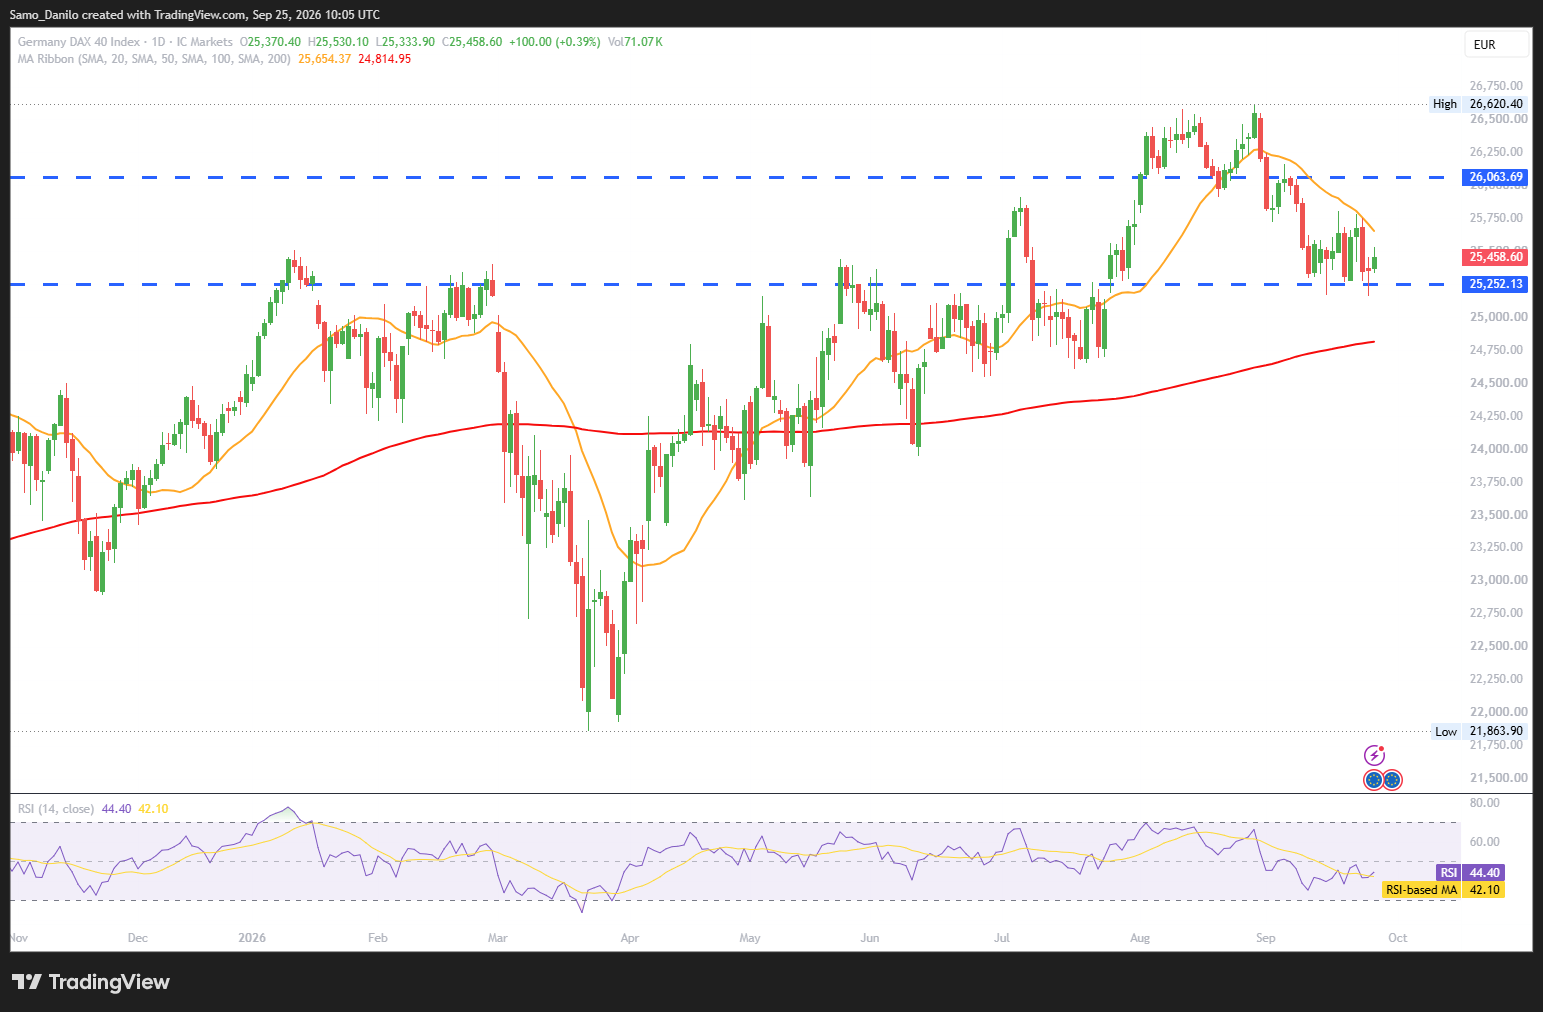
| SMA (20) | Falling | | |
| RSI (14) | Slightly Falling | |
|
| MACD (12, 26, 9) | Falling | | |
Closing statement: The DAX 40 trades near 25,470 as stronger German Ifo data reinforce signs of improving domestic business sentiment. However, shifting ECB policy expectations and uncertainty surrounding the outcome of the Xi-Trump meetings remain important factors for the index, while corporate developments such as Beiersdorf’s outlook could influence individual stocks.