EURUSD
- EUR/USD Price: The EUR/USD pair remains under selling pressure for a third consecutive day, trading around 1.1330 during the European session on Wednesday.
- ECB's Lagarde: ECB President Christine Lagarde’s dovish-leaning comments on Tuesday pushed back against expectations for another rate hike in October.
- Price expectations: Firms’ selling-price expectations in the euro area remained relatively stable in September despite higher energy costs. Expectations continued to decline in both retail trade and services, suggesting that businesses are not yet fully passing higher energy costs on to consumers or seeing broader inflationary pressure in the services sector.
- Inflation data: September flash inflation figures from Germany, France and Italy will be released, providing early indications of where the broader euro-area inflation reading could land on Friday.
- CB speakers: ECB Executive Board member Isabel Schnabel and Federal Reserve policymaker Thomas Barkin are scheduled to speak on Wednesday. Markets will also receive minutes from the Riksbank’s September meeting, adding further insight into the monetary-policy outlook across major European economies.
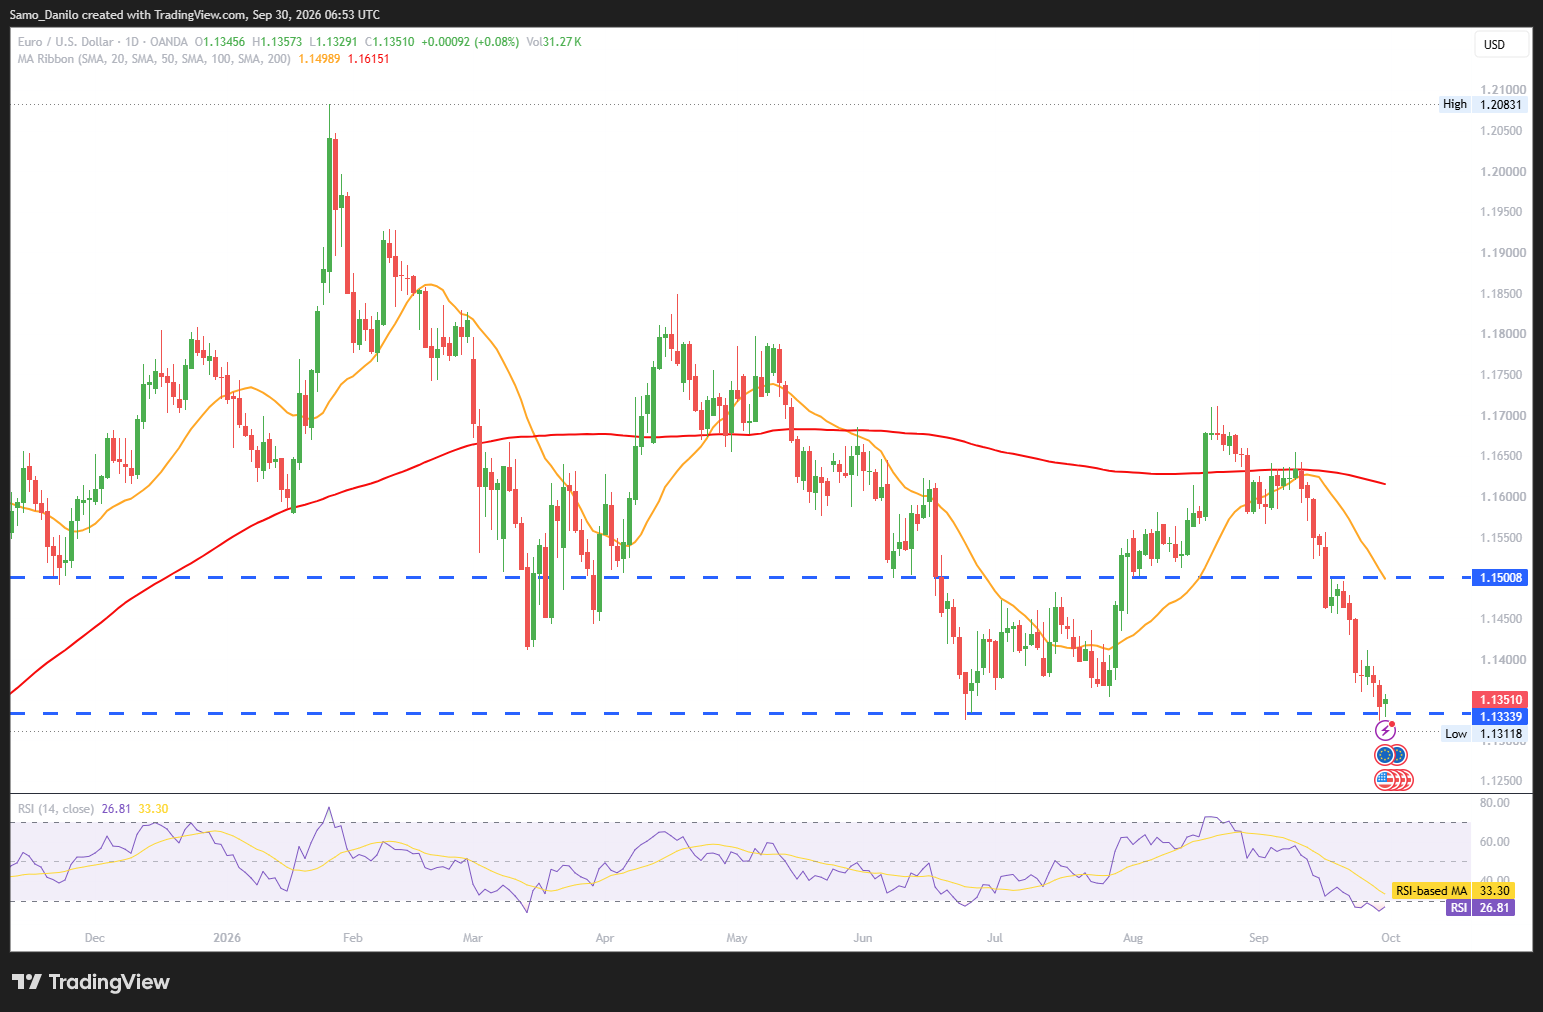
| SMA (20) | Falling |  | |
| RSI (14) | Falling | | |
| MACD (12, 26, 9) | Falling | | |
Closing statement: EUR/USD remains under pressure near 1.1330 as dovish ECB signals and contained euro-area price expectations reduce expectations for further tightening. Upcoming inflation data from the region and comments from ECB and Fed officials will be key catalysts, with renewed inflation pressure potentially altering the current policy outlook.
GBPUSD
- GBP/USD Price: The GBP/USD pair loses momentum and trades around 1.3225 during the early European session on Wednesday.
- Q2 GDP: The UK economy grew by 0.5% quarter-on-quarter in the second quarter, compared with the preliminary estimate of 0.4%, according to the latest ONS data.
- Pension policy: UK Prime Minister Burnham said the government will honour its commitment to maintaining the pension triple lock for now, while indicating that the state pension will be adjusted in April 2030 to help fund the National Care Service.
- US data: US job openings and consumer confidence both came in well below expectations, pointing to some weakening in the US economic outlook. August job openings declined to 7.079 million from 7.335 million, below the 7.225 million market forecast, potentially reducing pressure for further Fed tightening.
- Geopolitical news: Hopes for a diplomatic solution to the US-Iran conflict weakened after US President Donald Trump rejected a seven-day ceasefire proposal from Iran.
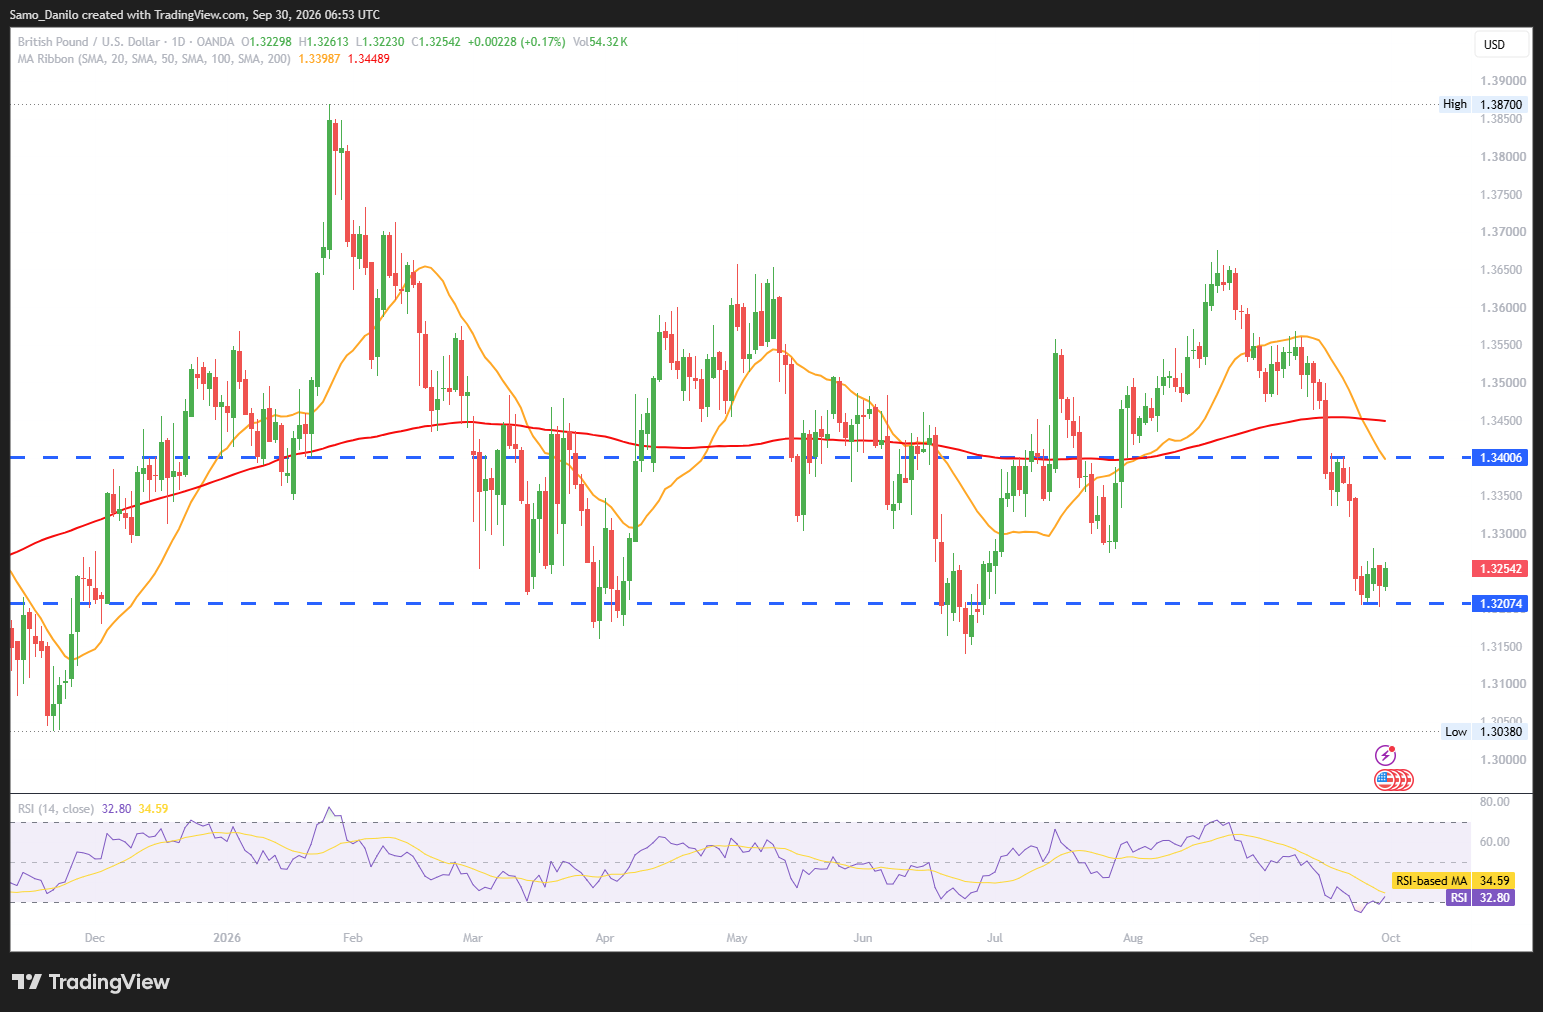
| SMA (20) | Falling | | |
| RSI (14) | Falling | | |
| MACD (12, 26, 9) | Falling | | |
Closing statement: GBP/USD remains around 1.3225 despite stronger-than-expected UK Q2 GDP, while weaker US labour-market and consumer data could limit support for the Dollar. However, continued uncertainty surrounding the US-Iran conflict remains an important source of volatility for the Pound and broader currency markets.
XAUUSD
- XAU/USD Price: Gold (XAU/USD) moves slightly lower during the Asian session on Wednesday, giving back part of the previous day’s modest recovery.
- Rate expectations: The initial market reaction to New York Fed President John Williams’ comments that the central bank does not need to rush its next move proved short-lived. Traders continue to price in more than a 90% probability of a rate hike by the end of the year, keeping monetary-policy expectations as a key headwind for gold.
- Consumer confidence: US consumer confidence fell significantly to 81.9 in September, well below the 89.2 consensus forecast and August’s 88.6 reading. The August figure was also revised lower, pointing to a weaker assessment of the US economic outlook among consumers.
- Chinese manufacturing: China’s official manufacturing PMI increased to 50.1 in September from 49.8 in August, moving back above the 50 threshold and ending two consecutive months of contraction. The independent RatingDog PMI also improved to 52.1 from 51.5, indicating stronger manufacturing activity and potentially supporting demand for commodities.
- PCE Inflation: Markets are awaiting the release of the US August Personal Consumption Expenditures (PCE) inflation data later on Wednesday. Headline inflation is expected to have increased from July’s 0.2% monthly and 3.7% annual readings, partly due to higher energy prices during August.
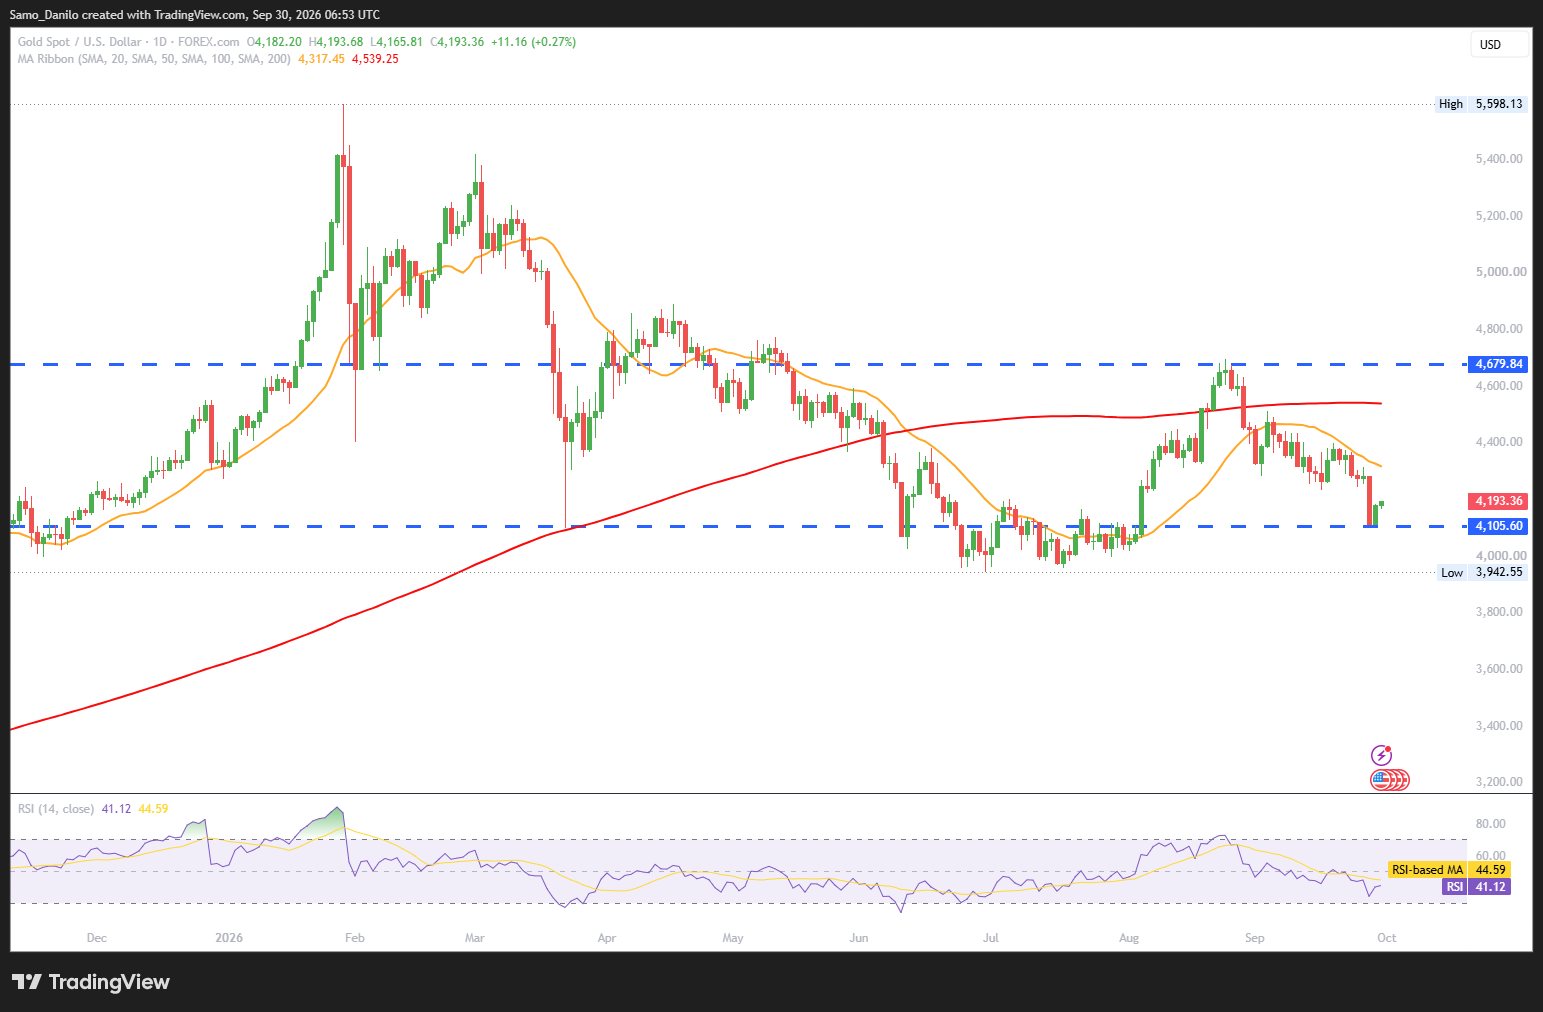
| SMA (20) | Slightly Falling | |
| RSI (14) | Slightly Falling | |
| MACD (12, 26, 9) | Slightly Falling | |
Closing statement: XAU/USD remains under modest pressure as elevated expectations for a Fed rate hike continue to weigh on the non-yielding asset, despite weaker US consumer confidence. The upcoming PCE inflation report will be the key catalyst, while stronger Chinese manufacturing activity could provide additional support to gold through improved commodity-market sentiment.
CRUDE OIL
- Crude Oil Price: West Texas Intermediate (WTI), the US crude oil benchmark, trades around $92.30 during the early European session on Thursday.
- Persian Gulf: According to Bloomberg, crude oil flows from the Persian Gulf have returned to pre-war levels, suggesting that the disruption to crude exports has largely eased.
- SPR release: The US Energy Department announced a new release of 40 million barrels from the Strategic Petroleum Reserve (SPR). Reports that Washington is also pressuring the EU to release strategic diesel stockpiles point to continued efforts to increase available energy supplies.
- Export ban: The Trump Administration continues to debate a possible ban on US diesel exports ahead of the November mid-term elections. Such a measure could alter regional refined-product flows and increase uncertainty around diesel supply conditions.
- Fed signals: Chicago Fed President Austan Goolsbee warned that inflation remaining above the Fed’s target represents a dangerous situation that may require policy action. Meanwhile, Fed Governor Michael Barr said further rate increases will likely be necessary to slow inflation, reinforcing expectations for tighter monetary policy.
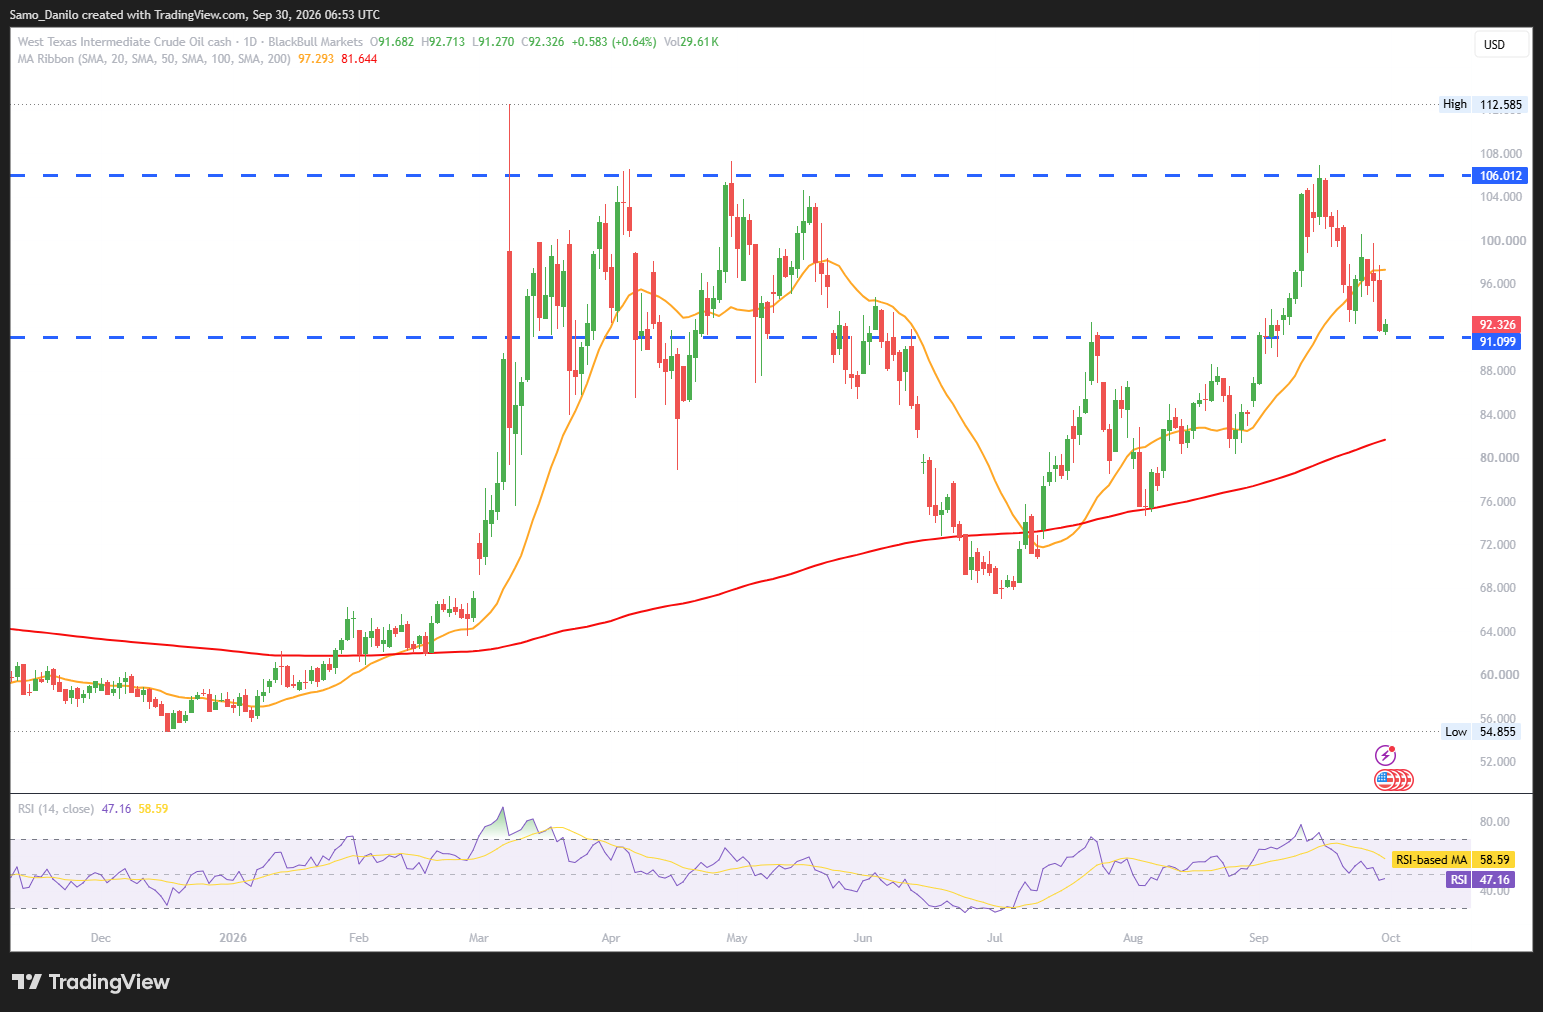
| SMA (20) | Rising |  | |
| RSI (14) | Slightly Falling | |
|
| MACD (12, 26, 9) | Slightly Rising | |
Closing statement: WTI remains around $92.30 as the recovery of Persian Gulf crude flows and additional strategic stockpile releases point to improving supply conditions. However, continued disruption in refined-product exports and uncertainty surrounding a potential US diesel-export ban remain important factors, while hawkish Fed commentary could weigh on demand expectations.
DAX
- DAX 40 Price: The DAX 40 trades around the 25,460-point level during Wednesday’s European morning session.
- Retail sales: Germany’s retail sales increased by 1.3% month-on-month in August, slightly below the 1.5% market expectation, according to Destatis. The weaker-than-expected increase points to somewhat softer consumer spending momentum than anticipated.
- Import prices: German import prices rose by 1.0% month-on-month in August, exceeding the 0.7% expected increase. The stronger reading could add to concerns about imported cost pressures within the German economy.
- Trade restrictions: China’s Commerce Ministry said Beijing would respond resolutely if the European side continues introducing discriminatory restrictions on Chinese companies or products. The comments highlight ongoing trade tensions between China and the EU, which could remain relevant for German exporters and industrial companies.
- Windfall tax: The EU Energy Commissioner said there are currently no plans for an EU-wide windfall tax, arguing that any such measure would be better implemented at the national level.
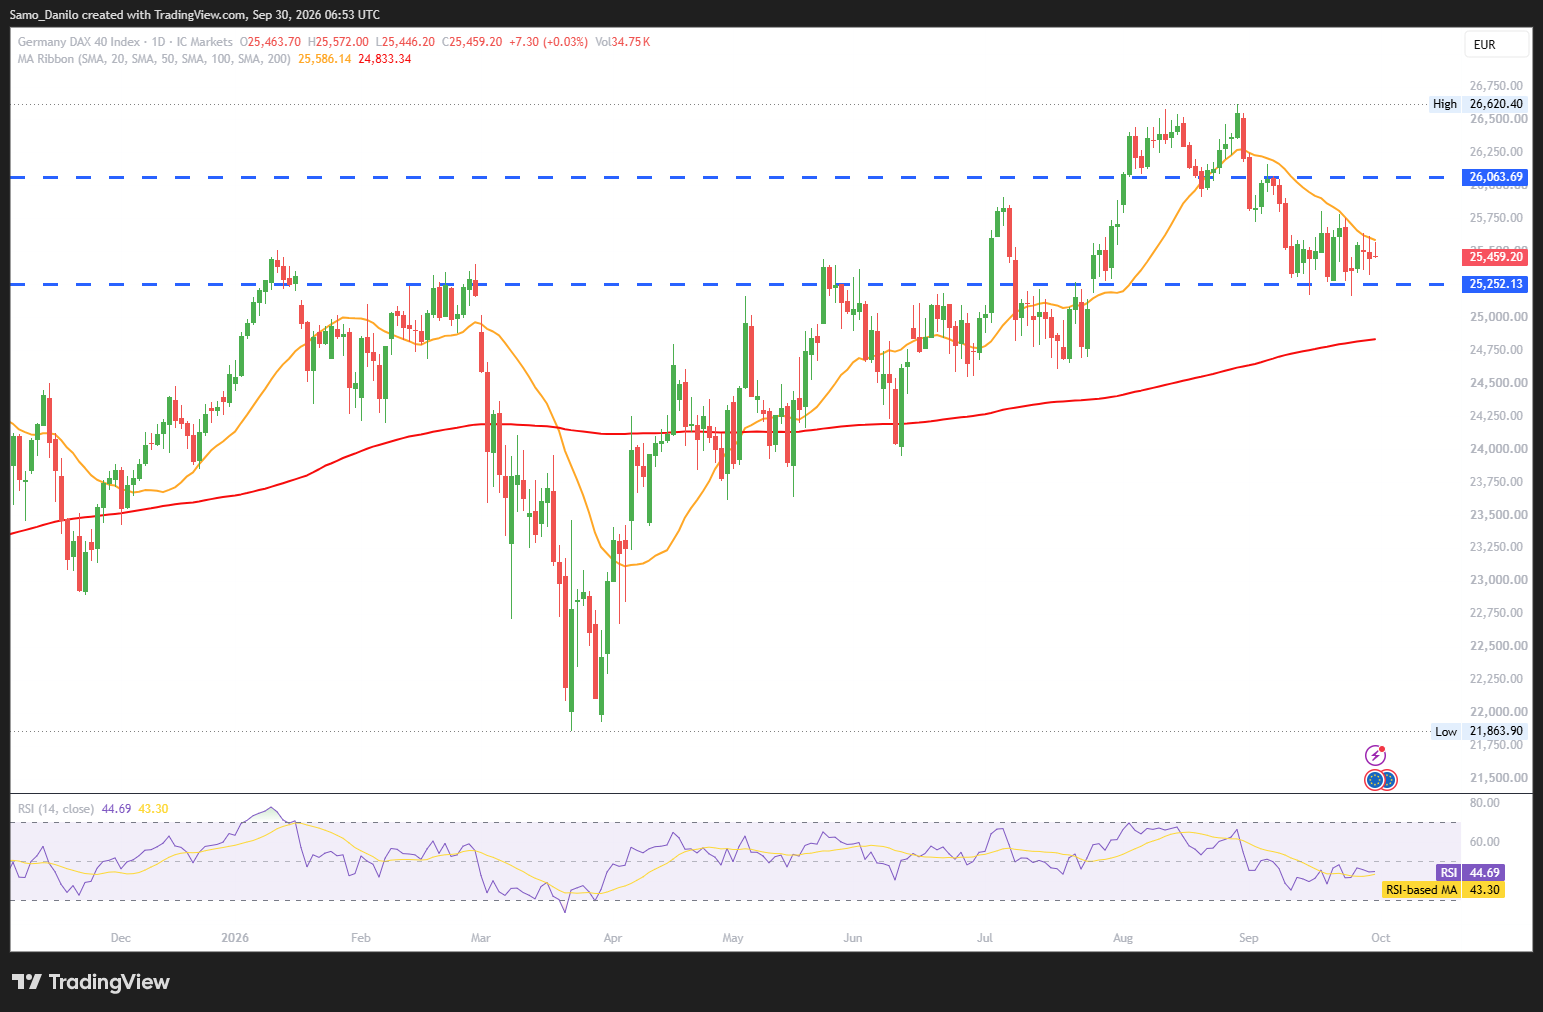
| SMA (20) | Slightly Falling | |
| RSI (14) | Slightly Falling | |
| MACD (12, 26, 9) | Slightly Falling | |
Closing statement: The DAX 40 remains around 25,460 as investors assess mixed German economic data and ongoing EU-China trade tensions. Softer retail sales contrast with higher import prices, while the absence of plans for an EU-wide windfall tax provides some clarity for the energy sector.